Tronox Misses As Price Gains Lift EBITDA, But A Weaker Q4 Outlook And Negative Full-Year Cash Flow Undercut The Recovery
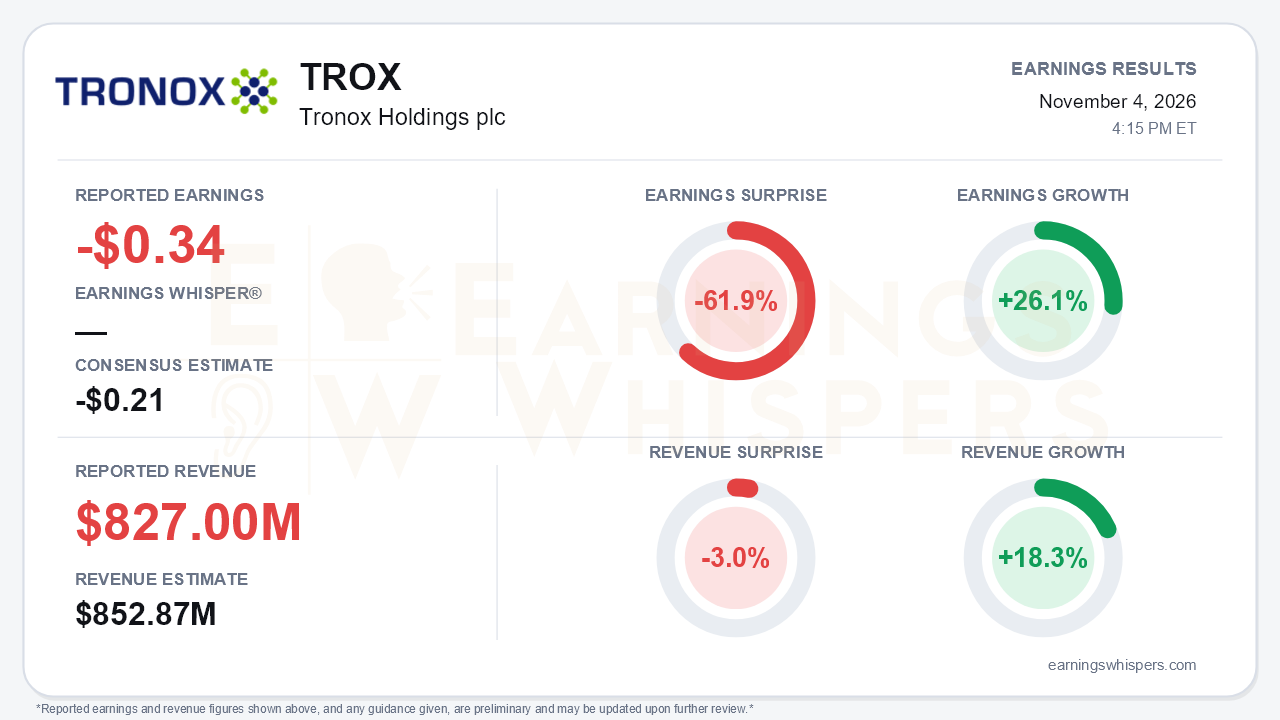
Tronox reported an adjusted loss of $0.34 per share for the third quarter, missing the consensus estimate of a $0.21 loss by 61.9%. Revenue rose 18.3% year over year to $827.0 million but fell 3.0% short of the $852.87 million consensus. Earnings improved 26.1% from a year ago, as the adjusted loss narrowed from $0.46, and the GAAP loss nearly halved to $0.34 from $0.63. That is the case for improvement. The more important development is that the second-half earnings recovery management described earlier in the year has largely disappeared. The Middle East conflict cut into demand and raised input costs, and full-year free cash flow guidance moved from a meaningful source of cash to a use of $25 million to $50 million.
The quarter split cleanly between price and volume. Adjusted EBITDA rose 38% sequentially to $101 million, and margin expanded to 12.2% from 8.4% in the second quarter. That result landed within guidance and was driven by TiO2 prices rising 4% sequentially, the third straight quarterly gain, with surcharges largely converted into base price. Volume moved the other way. TiO2 volumes fell 11% sequentially and zircon volumes dropped 13%, so total revenue declined 5% from the second quarter. Below EBITDA, the improvement thins out. Operating income was only $12 million against $56 million of interest expense. Free cash flow was just $5 million. Net leverage rose to 10.5 times trailing EBITDA from 9.0 times at year-end.
The call made the change in tone hard to miss. Earlier in the year, management talked about an inflection point, sold-out pigment and triple-digit EBITDA quarters in the back half. This time the language shifted to focusing on what the company can control and not banking on a recovery. The fourth-quarter outlook reflects that:
- **EBITDA:** guided to $80 million to $90 million, below the third quarter's $101 million.
- **TiO2 volumes:** expected to decline by a high-single to low-double-digit percentage, with weakness in Europe and Asia Pacific on top of normal seasonality.
- **TiO2 pricing:** expected to hold flat, ending three quarters of sequential gains.
- **Input costs:** natural gas, sulfur and sulfuric acid are expected to add $15 million to $20 million in costs.
- **Operations:** the Yanbu plant had unplanned downtime after Saudi Arabia's East-West gas pipeline closed. The site is back up and running.
On the cash side, the expected working-capital inflow was trimmed to $65 million to $89 million from more than $100 million, and capex was cut by $30 million.
The longer-term catalysts did advance. India reinstated anti-dumping duties, and management expects the volume benefit to arrive in the first half of 2027 as Chinese pre-buy inventory is used up. Other trade measures also moved forward:
- The UK made a preliminary duty recommendation of roughly 48%.
- Japan opened an investigation.
- The EU launched an anti-absorption probe that could raise duties around mid-first-half 2027.
The new JX Advanced Metals partnership puts real structure around the rare earths strategy. The two companies will split roughly $32 million in study funding, though production is years away, with the Australian facility targeted for late 2030. The cost program is now expected to exceed $175 million in run-rate savings by year-end, and similar targets are planned for 2027 and 2028. Bears still have legitimate ammunition. Chinese chloride TiO2 exports are up about 50%, former Venator capacity is restarting, and inventories are low heading into the seasonal first-quarter working-capital build.
The market setup is more complicated than the miss implies. Shares have fallen 45.3% since opening at $6.49 after the August report, to $3.55, and sit 46.4% below the 200-day moving average of $6.62. Price trend and AVWAP readings both remain negative. Investor sentiment, however, swung sharply, from deeply negative (-0.64) to modestly positive (+0.12). That suggests some investors view the collapse as having already priced in the cash-flow reset, and they are leaning on pricing discipline and trade protection. The balance sheet gives Tronox time but not much margin for error. Liquidity is $509 million, there are no significant maturities until 2029, and the term debt carries no financial covenants. Still, leverage near 10.5 times leaves equity holders highly exposed to any further slippage in EBITDA.
The bottom line is that Tronox showed it can raise prices, but not that it can earn its way out of its capital structure. Third-quarter EBITDA recovered, yet the per-share miss and a step-down in fourth-quarter guidance push any real earnings inflection into 2027. That inflection now depends on trade duties actually converting into volume and on input-cost relief. Improved sentiment and a deeply depressed share price give the stock room to react to good news. Weak free cash flow and double-digit leverage keep the burden of proof firmly on management.
Read our earnings preview for Tronox Holdings plc: https://www.earningswhispers.com/article/TROX/21955
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Oct-27 | |
| Oct-05 | |
| Sep-29 | |
| Aug-10 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| Jul-29 | |
| Jul-08 | |
| Jun-11 | |
| May-06 |
