Sabre Beats On Profit And Raises EBITDA Outlook Again, But Negative Air Bookings Keep The Growth Story In Question
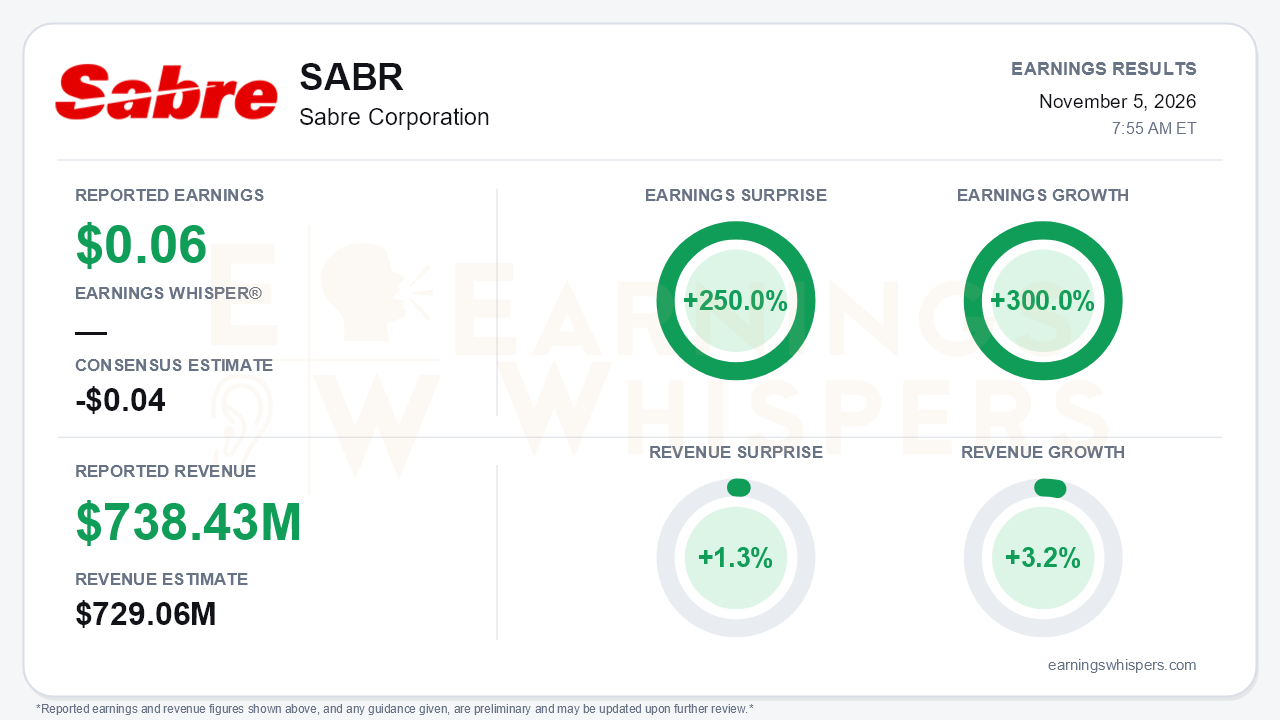
Sabre delivered a clean headline beat for the third quarter, reporting earnings of $0.06 per share against a consensus estimate calling for a $0.04 loss. That is a 250.0% surprise, and earnings grew 300.0% year over year. Revenue of $738.43 million topped the $729.06 million consensus by 1.3% and grew 3.2% from a year ago. Management also raised its full-year EBITDA and free-cash-flow guidance for a second straight quarter. Beneath that, the top line kept losing speed. Revenue growth slowed from 8% in the first quarter to 4% in the second and 3% now. Air marketplace bookings, the core of Sabre's franchise, turned negative. That is the central tension: margin and cost discipline are carrying the earnings story while volume growth stalls.
The quality of the beat deserves scrutiny. Sabre's press release was only a notice that materials were posted, so the operating detail comes from the call and accompanying disclosures. Normalized adjusted EBITDA reached $170 million, up 13% year over year. It was the fifth straight double-digit quarter and comfortably ahead of the $155 million management had guided for in August. EBITDA margin improved to about 23% from 21.2% in the second quarter. Part of that upside, however, came from lower technology spending and a tax refund. Neither is a durable source of earnings power. Cash generation also remains a work in progress. Third-quarter free cash flow was negative $48 million, weighed down by about $15 million in refinancing fees and $40 million of accrued interest.
The operating trends split sharply by segment:
- **Air marketplace:** bookings fell 1% after gains of 1% in the second quarter and 6% in the first. Total marketplace bookings were flat.
- **Middle East and fuel:** the 300-400 basis-point headwind persisted unchanged from the second quarter. Earlier in the year, management had assumed it would normalize by the fourth quarter.
- **Leisure demand:** softness spread across EMEA and APAC.
- **Industry outperformance:** Sabre cited 400-500 basis points year to date, down from roughly 600 basis points in the second quarter.
- **Hotel:** revenue growth accelerated to 14% from 11% and 10% in the prior two quarters, with attach rates above 35%.
- **Payments:** gross spend rose 27% to roughly $26 billion annualized, supporting a revenue run-rate near $60 million.
- **Airline technology:** revenue grew 3% to $144 million, recovering from a year-over-year decline in the second quarter, helped by a Kenya Airways Mosaic win and four implementations completed or underway.
The forward-looking picture combines real balance-sheet progress with muted demand expectations. Sabre refinanced $1.35 billion at 9.875%, down from 11.8% previously. That extends maturities to 2032 and leaves no large maturities until the third quarter of 2029, which materially lowers near-term refinancing risk for a highly levered company. The renewal of United Airlines' distribution agreement, including NDC content access, removes a key customer overhang. Management lifted its 2026 outlook on several fronts:
- pro forma adjusted EBITDA to about $610 million, from about $600 million in the second quarter and about $585 million in the first;
- free cash flow to about negative $50 million, from negative $65 million;
- gross margin to about 57%;
- capital spending to about $95 million.
Revenue and bookings guidance, by contrast, was merely reaffirmed at low-to-mid single digits, below the mid-single-digit target originally set for the year. Management reiterated mid-single-digit volume and revenue growth for 2027 and pointed to sequential improvement in fourth-quarter-to-date bookings. It also signaled no robust external recovery into next year. That leaves the 2027 target resting heavily on share gains, hotel, payments, and airline IT rather than market tailwinds. The November 17 Investor Day, with multi-year projections, becomes the next credibility test.
Investors entered the report in a skeptical mood. Earnings Whispers sentiment deteriorated meaningfully, sliding from roughly neutral at -0.03 to -0.20. The stock fell 13.9% from the open following the August report to $1.74. The price action was volatile. Shares hit a 52-week high of $2.50 in mid-September, then collapsed to a $1.46 low in late October. They have since rebounded about 19% to sit exactly on the 200-day moving average, still roughly 30% below the September peak. The Earnings Whispers trend signals are mostly negative, with price, sequential growth, and AVWAP readings weak, though momentum has turned positive alongside the late-October bounce.
The bottom line is that Sabre is executing well on what it controls: costs, margins, refinancing, and adjacent growth in hotel and payments. The core air marketplace, however, is moving the wrong way. The earnings beat and higher EBITDA guide give bulls something tangible, while bears have legitimate ammunition in negative air bookings, decelerating revenue, a lower-quality component to the beat, and still-negative free cash flow. With sentiment soured and shares parked at their 200-day average, the Investor Day will need to show a credible path to volume growth, not just margin expansion, to change the setup.
Read our earnings preview for Sabre Corporation: https://www.earningswhispers.com/article/SABR/22180
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 8 hours | |
| 8 hours | |
| Oct-28 | |
| Oct-15 | |
| Oct-05 | |
| Oct-01 | |
| Sep-25 | |
| Sep-24 | |
| Sep-24 | |
| Sep-22 | |
| Sep-21 | |
| Sep-16 | |
| Sep-15 | |
| Sep-15 |
