Redwire Edges Past EPS Estimate, But A 13% Revenue Miss Leaves A Back-End-Loaded Guide Hanging On Q4 Deliveries
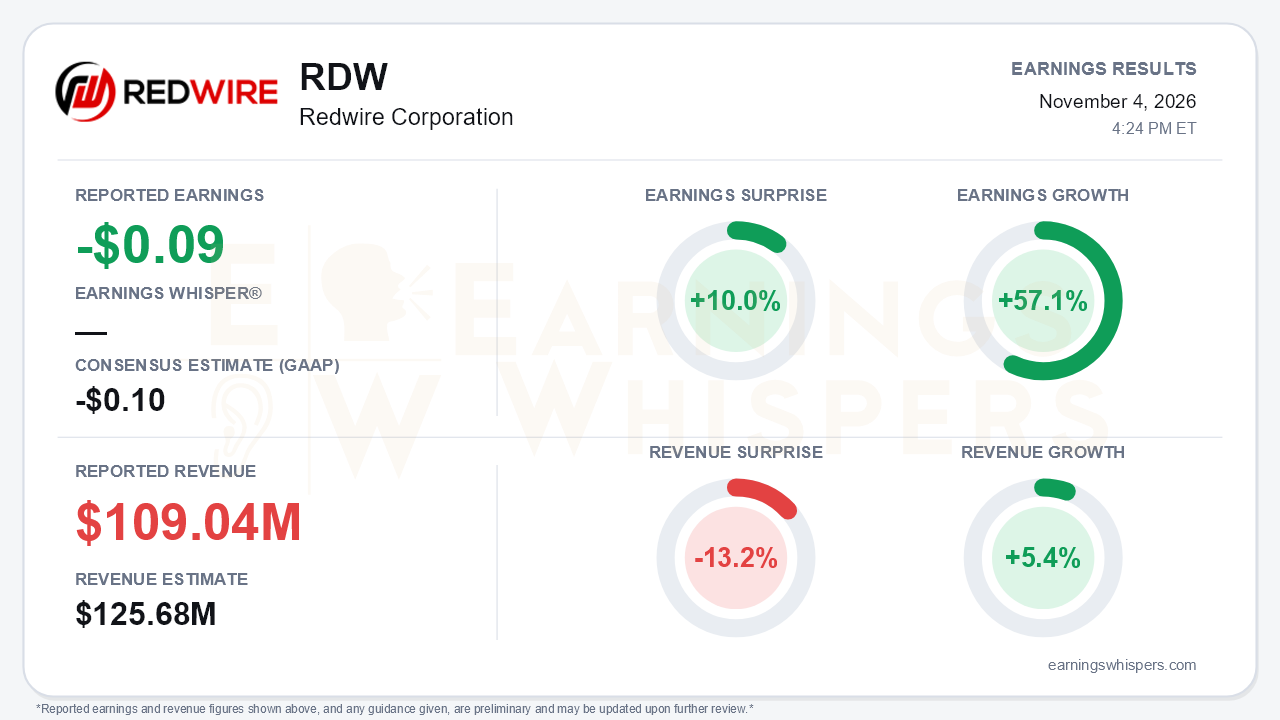
Redwire (NYSE: RDW) delivered a split quarter. The record margins and backlog are real, but they are being undercut by revenue that keeps slipping to the right. The company reported a GAAP loss of $0.09 per share, beating the -$0.10 consensus by 10.0%, and earnings improved 57.1% from a year ago as the net loss narrowed to $23.2 million from $41.2 million. Revenue of $109.04 million, however, missed the $125.68 million consensus by 13.2%. Growth of just 5.4% marks a sharp deceleration from the 57.9% pace in the first quarter, and revenue fell sequentially from roughly $117 million in Q2. Management reaffirmed its $450 million to $500 million full-year revenue forecast for the third straight call. That reaffirmation now carries much more weight than it did.
The quality of the EPS beat deserves scrutiny. Gross margin jumped to a record 32.3% from 16.3%, but the year-ago figure absorbed an $11.2 million purchase-accounting inventory charge from the Edge Autonomy deal. On an adjusted basis, the improvement was a more modest move from 27.1% to 32.3%. That is still genuine progress, with Space margins rising to about 18% from 4% and Defense Tech reaching about 50%. Below the gross line, the beat leaned on several other factors:
- **Net interest:** it swung to $2.7 million of income from $6.3 million of expense.
- **Equity compensation:** it fell by roughly half.
- **Share count:** weighted shares rose to 250 million from 146 million, which shrinks the per-share loss.
Adjusted EBITDA actually worsened to -$5.3 million from -$2.6 million a year ago. Management attributes this to research and development spending, which rose 87% to $14.4 million. The figure has improved from -$9.2 million in Q1, but management declined to lay out a path to breakeven.
Demand is the clearest bright spot. Q3 bookings of $188.7 million produced a 1.73 book-to-bill, up from 1.42 in Q2, with Space at 1.96. Backlog rose for a sixth straight quarter to a record $619.7 million, up about 75% year over year. Defense Tech backlog has more than doubled since year-end to $240.1 million. New wins supported the trend:
- a $20 million DARPA award for a second very-low-Earth-orbit SabreSat flight, which management said arrived earlier than expected;
- $15 million of ELSA solar arrays to AscendArc;
- an Axiom follow-on order for Roll-Out Solar Array (ROSA) wings;
- a $13.8 million Stalker order from the National Guard.
The problem is conversion. Defense Tech revenue fell about 16% year over year to $47.8 million, which management blamed on unmanned aircraft shipment timing during the Block 30-to-40 and Penguin Mk3 transitions, plus export-control and supplier delays.
That is the central tension. With $323.1 million booked through nine months, Redwire needs roughly $127 million to $177 million in Q4, or about $152 million at the midpoint, compared with $109 million in Q3. Management is relying on $46.8 million of Defense Tech work-in-process and finished-goods inventory converting in the fourth quarter. The call's tone shifted from Q2's emphasis on delivering growth to more defensive explanations about timing. The cash statement shows the cost of that build:
- Inventory climbed to $99.8 million from $55.8 million at year-end.
- Contract assets nearly doubled.
- Q3 free cash flow was -$66.4 million, versus -$27.8 million a year earlier.
- Liquidity fell to $538.9 million from $607.8 million in Q2.
The balance sheet remains well funded thanks to $566.7 million of equity raised this year, which also explains the dilution. Political risks also emerged on the call: a post-midterm shift to a Democratic Congress, a possible continuing resolution, and uncertainty over Golden Dome.
The market had already priced in considerable doubt. Shares at $7.72 are down 36.9% since the open following the August report and sit about 30% below the $11.04 200-day moving average. Investor sentiment remained negative but improved modestly, to -0.079 from -0.128. That suggests expectations were low rather than hopeful heading into the print. The Earnings Whispers trend readings are mixed, with sequential growth and momentum positive while price and AVWAP remain negative. That split mirrors the gap between improving operating metrics and a stock that has been sold steadily.
The bottom line is that Redwire's underlying business looks stronger than its revenue line. Margins are expanding, bookings are accelerating, and backlog is at a record. But the company has turned the fourth quarter into a credibility test. Bulls can point to a record order book and inventory staged for shipment. Bears have legitimate ammunition in decelerating revenue, worsening adjusted EBITDA, heavy cash burn and an outlook that requires the strongest quarter in company history. Until those orders convert into shipped revenue, the narrow EPS beat matters far less than whether Q4 delivers.
Read our earnings preview for Redwire Corporation: https://www.earningswhispers.com/article/RDW/22519
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-30 | |
| Oct-29 | |
| Oct-26 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 |
