Prospect Capital Beats On NII, But Shrinking Income, Shareholder Dilution And Another NAV Drop Overshadow Cleaner Credit
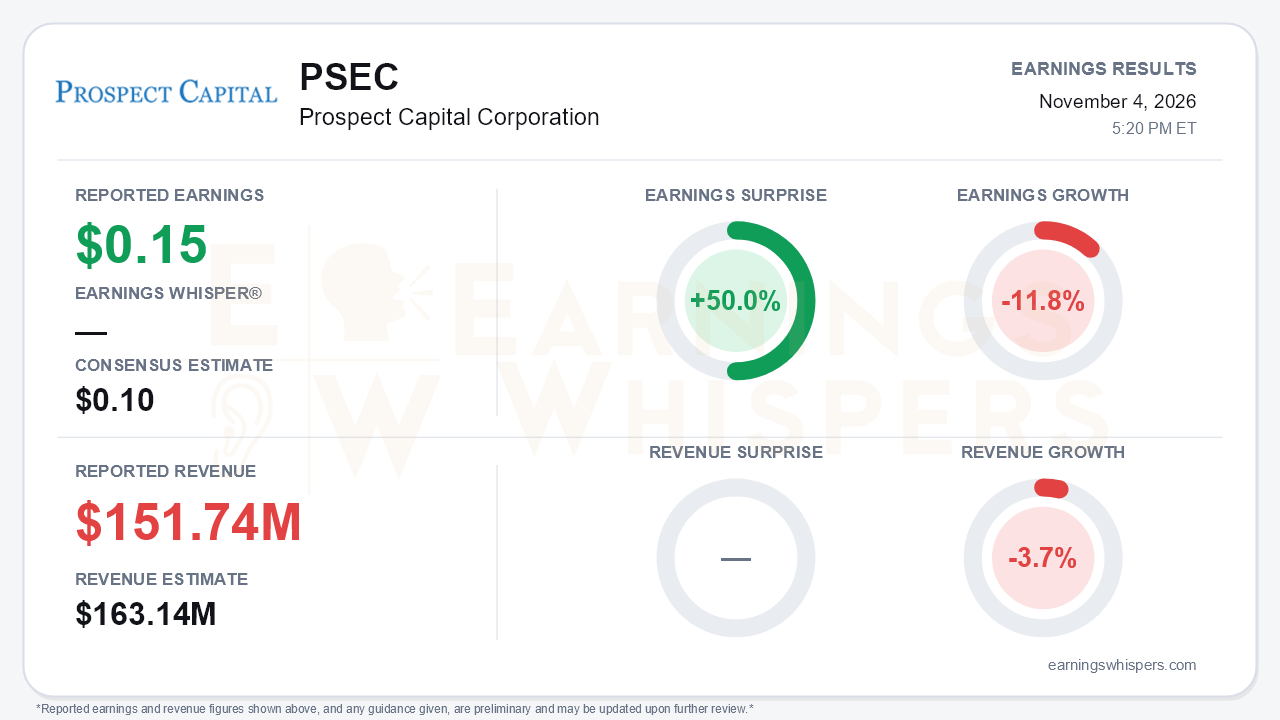
Prospect Capital (NASDAQ: PSEC) delivered a headline beat that does little to change the larger story. Net investment income of $0.15 per share topped the $0.10 consensus by 50.0%. But earnings still fell 11.8% from a year ago. Revenue of $151.74 million missed the $163.14 million consensus by 7.0% and declined 3.7% year over year. On a GAAP basis, the company swung from net income of $0.10 per common share a year ago to a net loss of $0.10, wider than the prior quarter's $0.08 loss. NAV per share fell to $5.36 from $5.71, a roughly 6% sequential drop. That is the central tension: Prospect is getting safer and smaller, but it is not yet getting more valuable per share.
The quality of the beat deserves scrutiny. Cash interest income excluding PIK fell to $116.2 million from $137.0 million a year earlier. Interest's share of total investment income dropped to 87.4% from 96.7%. Several items filled the gap:
- Other income, almost entirely from control investments, jumped to $13.7 million from $1.7 million.
- PIK interest rose to $16.5 million.
- A $3.25 million administrative expense reimbursement lowered net expenses.
Those are not the building blocks of a durable earnings base. Coverage of the common payout is also thinner than the $0.15 headline implies. According to the NAV rollforward, about $0.05 per share went to preferred holders. That left roughly $0.10 against $0.11 of common distributions in the quarter, even after the payout had already been cut. Prospect held the monthly distribution at $0.035 for November through January.
The NAV decline had two drivers. Net realized and unrealized losses cost $0.20 per share. A $131.6 million realized gain on control investments, largely tied to the $328 million Valley Electric sale, was overwhelmed by $203.2 million of realized losses on non-control positions and $239.6 million of unrealized depreciation in control investments. Common stock transactions subtracted another $0.15 per share. The share count rose to 536.3 million from 512.7 million, and management's footnotes point to preferred conversions and other issuance as part of that bucket. NPRC's embedded unrealized gain also kept shrinking, to $159 million from $185 million last quarter and $270 million two quarters ago. That removes some of the cushion investors have counted on from real estate exits.
The balance-sheet repair is real.
- **Debt:** Prospect cut outstanding debt principal by $341.4 million, or 18%. Net-of-cash debt to total assets fell to 25.0% from 28.6%.
- **Liquidity:** Cash plus undrawn revolver capacity rose to $1.87 billion.
- **Refinancing:** The company called all $263.2 million of its November 2026 notes and priced $300 million of 2031 notes.
- **Credit:** Non-accruals dropped to 1.8% of cost from 4.7% and 0.2% of fair value from 0.7%.
- **Mix:** Post-quarter second-lien repayments of $69.4 million bring pro forma second-lien exposure to 10.0% of cost.
Part of the non-accrual improvement, however, appears to have come through exits and realized losses rather than credits healing in place.
The operating trends point to contraction. Originations slowed to $90.5 million from $166.3 million. Repayments and sales of $257.4 million produced $166.9 million of net runoff. The portfolio shrank to $5.94 billion at fair value, and the number of portfolio companies fell to 85 from 91. Funding costs keep inching up, with the weighted average cost of unsecured debt at 4.84%. The call analysis also shows average cash interest coverage at portfolio companies slipping to 211% from 223%. That contrasts with Prospect's own interest coverage, which improved to 375% as borrowings came down. The call itself was scripted, with no analyst questions. The AI value-creation message emphasized last quarter was dropped from the call, even though it remains in the release.
The new catalyst is a $200 million repurchase authorization. At $1.44, the stock trades at roughly 27% of NAV, so buybacks would be meaningfully accretive per share if executed at scale. That would also partly offset the dilution that hurt NAV this quarter. Whether management deploys the authorization aggressively is the key open question.
The market has been unforgiving. Shares are down 37.4% from the $2.30 open after the August report and sit 38.8% below the $2.35 200-day moving average. The Earnings Whispers trend signals are uniformly negative, reflecting persistent price and sequential-growth deterioration. Investor sentiment of 0.15 is only mildly positive, which suggests caution rather than capitulation.
The bottom line is that Prospect's quarter showed a cleaner, less levered, better-funded balance sheet, but the earnings base is eroding. The beat leaned on non-recurring income, the portfolio is shrinking, and NAV per share has fallen for four consecutive quarters. Bears have legitimate ammunition in thin distribution coverage and dilution. The buyback is the one lever that could turn the deep discount to NAV into a per-share tailwind.
Read our earnings preview for Prospect Capital Corporation: https://www.earningswhispers.com/article/PSEC/22776
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-29 | |
| Oct-27 | |
| Oct-22 | |
| Sep-28 | |
| Aug-21 | |
| Aug-20 | |
| Aug-20 | |
| Aug-19 | |
| Jul-06 | |
| Jun-23 |
