Dragonfly Energy's Trucking Ramp Faces Its First Real Test After A 77% Stock Collapse
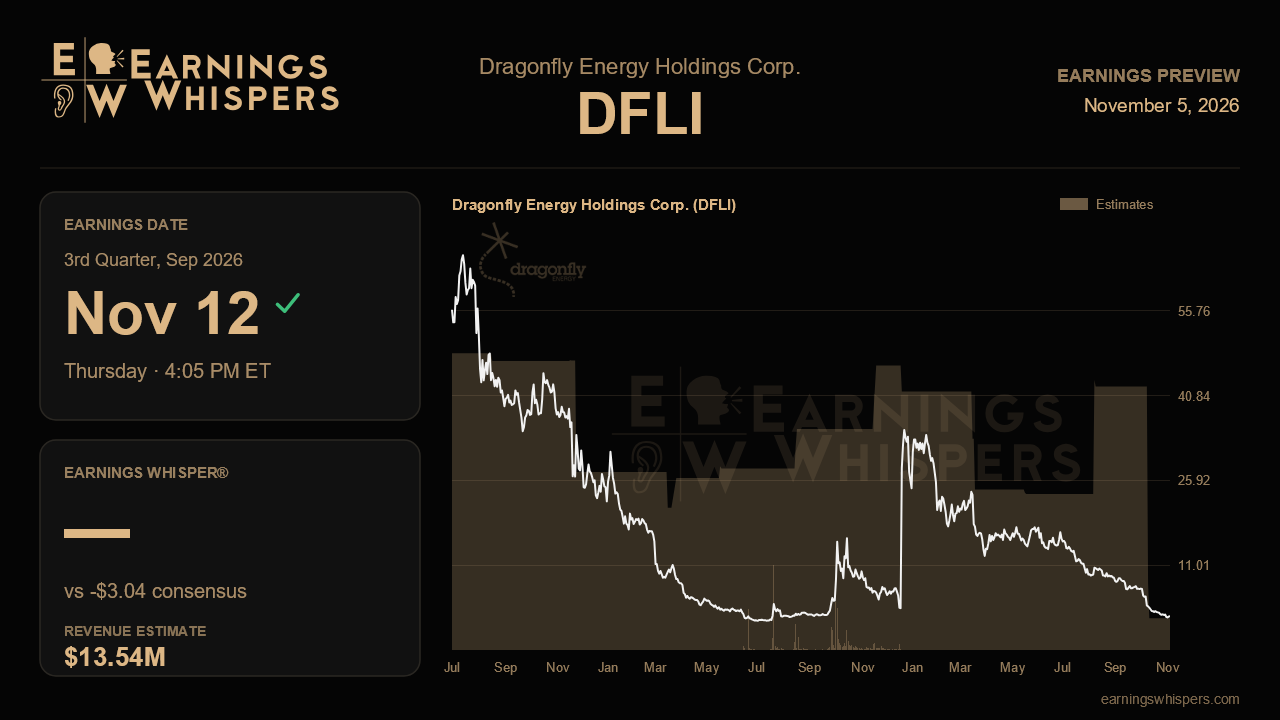
Three months ago, Dragonfly Energy told investors its engine was finally working. Heavy-duty trucking had moved from pilot programs to actual revenue, gross margin had jumped to 33%, and a bolt-on deal for Dakota Lithium promised a new channel at little added overhead. The market's verdict since then has been brutal: the shares have lost about 77% of their value while the S&P 500 barely moved. The third-quarter report, due after the close on November 12, is where the company has to show that the operating story still holds even though the stock has stopped believing it.
The revenue bar is unusually clear. Management guided to roughly $13.5 million for the quarter, and consensus now sits right on that figure, after Street estimates had stood near $17.4 million before the company spoke up. That puts expectations squarely on management's number rather than above it, so the top line is less about a beat than about confirming the outlook was conservative enough. At $13.5 million, sales would be up only slightly from the second quarter's $13.2 million and down about 15% from $16.0 million a year ago, which is contraction, not recovery. Consensus calls for a loss of $3.04 per share against a $0.43 loss last quarter, a figure that sits so far from recent history that revenue and adjusted EBITDA are likely the cleaner measures of how the business actually performed.
Trucking is the swing factor that matters most. Management said heavy-duty revenue of about $0.5 million in the second quarter should more than double to roughly $1.3 million, with Stevens Transport shipping against a 2,500-truck program and Werner implementation underway. Hitting or exceeding that mark would validate the claim that fleet conversions are no longer slipping, a pattern that marked several earlier calls. A shortfall, or vague language about rollout timing, would revive the concern that trucking remains a pipeline rather than a business. Commentary on the newly hired national fleet sales leader and the emerging industrial opportunities in traffic signals and telecom will help gauge whether a second leg is forming.
Margins are the other test. The second-quarter gross margin of 33% was a dramatic leap from 17.6% in the first quarter, and investors need evidence it reflects mix and cost discipline rather than a one-time high-water mark. Management has already guided adjusted EBITDA down to about negative $2.4 million from negative $1.6 million, blaming temporary costs for vacated space and restarting Dakota. If the loss lands near that guide with gross margin holding in a similar range, the step-down looks like the transitory blip management described. A wider loss, or a margin retreat toward the high teens, would suggest the cost actions worth about $9 million a year are being overwhelmed. Updates on Dakota's restart, which was supposed to turn EBITDA-accretive in the fourth quarter, and on the RV market, which management now expects to stay soft through 2026, round out the operating picture.
The balance sheet hangs over everything. Recent covenant relief, payment-in-kind interest for two quarters and a lower minimum cash requirement bought time but also signal tight liquidity, so any discussion of cash, working capital or financing will be scrutinized closely.
Sentiment has swung from mildly bearish before the last report to solidly bullish now, an odd backdrop for a stock trading near $2.03, close to its post-report low of $1.80 and far beneath its 200-day average of $13.80. That gap suggests optimism about the plan coexists with deep skepticism about the capital structure. The report ultimately comes down to one question: can trucking volume and sustained margins arrive fast enough to carry Dragonfly toward profitability before its financial cushion runs thin?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Aug-17 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Jul-31 | |
| Jul-30 | |
| Jul-21 | |
| Jun-23 | |
| Jun-18 | |
| Jun-15 | |
| Jun-02 | |
| May-15 | |
| May-14 |
