United Parks Misses As Attendance Slide Deepens And 2026 Growth Hopes Fade, While Pass Sales And Pricing Shift The Story To 2027
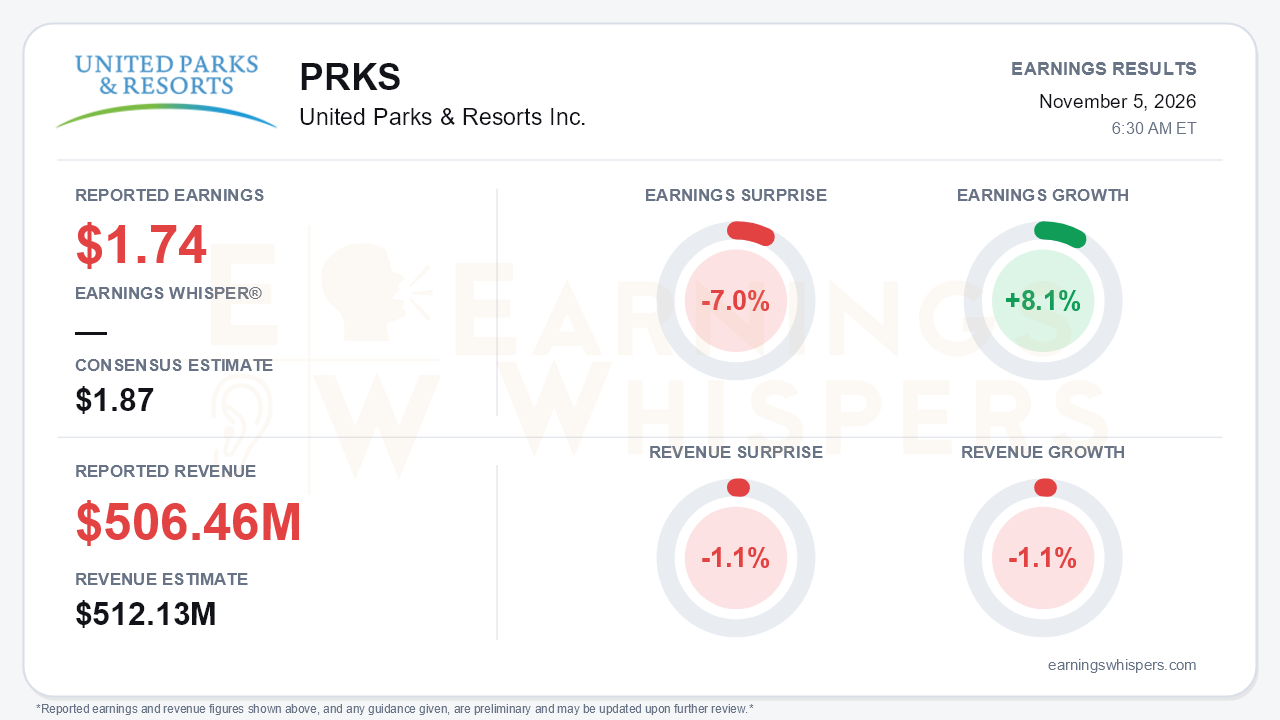
United Parks & Resorts (NYSE: PRKS) delivered another quarter in which the forward indicators looked better than the reported results. Third-quarter earnings of $1.74 per share missed the $1.87 consensus by 7.0%. Revenue of $506.46 million fell 1.1% short of expectations and was down 1.1% from a year ago. Earnings grew 8.1% year over year, but that figure needs context. Net income actually fell 10.5% to $80.0 million. The EPS gain came entirely from a sharply smaller share count, with roughly 46.0 million diluted shares versus 55.5 million a year earlier, the product of aggressive buybacks earlier in the year. That is the central tension: per-share growth is being manufactured by capital allocation while the operating business keeps shrinking, even as management points to early evidence that 2027 could look very different.
The operating trend deteriorated again. Attendance fell 4.7%, or about 320,000 visits, which was worse than the 2.9% decline in the second quarter. Adjusted EBITDA dropped about $11 million to $205.1 million, the third straight quarter of year-over-year declines, and the gap has widened each quarter. Selling, general and administrative expense jumped 13.1%. Management also conceded that its gross cost savings have not yet produced net margin expansion. The add-backs also merit attention: business optimization and strategic initiative costs excluded from Adjusted EBITDA rose to $8.5 million from $4.9 million. Free cash flow fell 38.3% to $23.5 million, as capital spending ran 22.9% higher. Cash ended September at just $26 million, and $40 million was drawn on the revolver.
Beneath that weak headline, the revenue mix improved in ways that matter. CEO Marc Swanson said unusual weather, calendar and international headwinds cost roughly 325,000 visits. He also said a planned reduction in promotional admissions cost more than 100,000. By his account, attendance would have been up excluding the unusual headwinds. Pricing is clearly working:
- Admission per capita swung to +3.4% after declines of 1.8% in the second quarter and 0.5% in the first.
- Total per capita revenue growth accelerated to 3.8% from 1.5%.
- In-park spending reached a record $37.39.
- The paid pass base turned slightly positive at +0.3% through October, up from -1% in June and -4% at year-end 2025.
- Third-quarter pass sales rose about 8%, and the 2027-specific pass base is up more than 15%.
- Deferred revenue grew 4.9%, an improvement from 2% in June.
Those are the most credible signs yet that the demand problem is about volume and execution rather than pricing power.
The guidance picture, however, moved backward. In the first quarter, management committed to 2026 revenue and EBITDA growth. In the second quarter, it expected growth from August through December. Both expectations have now effectively been abandoned, and fourth-quarter EBITDA growth is framed as contingent on weather. The sponsorship outlook was trimmed to $12-15 million from more than $15 million, and the real estate monetization timeline slipped. Share repurchases were paused in the third quarter, after roughly $125 million in the second quarter and $93 million in the first. With net leverage up to 3.55x from 3.4x, the buyback support that drove this quarter's EPS growth is no longer available. Marketing execution is still described as making only slow progress.
Management is trying to offset those cuts with new catalysts:
- a new $40-50 million gross cost-savings target for 2027;
- double-digit gains in 2027 forward bookings at Discovery Cove and in group business;
- international sales revenue up mid-single digits;
- a non-binding MOU for a potential Middle East park;
- new attractions slated for 2027.
The common thread is that the growth narrative has shifted a full year out. Bears have legitimate ammunition in a company that has repeatedly pushed the inflection point forward.
The market had already priced in much of the disappointment. Shares opened at $50.00 after the August report, which marked a 52-week high, and then fell 31.6% to $34.19 heading into this release. The stock touched an inter-earnings low of $29.64 on October 21 and has since rebounded about 15% from that level, but it remains roughly 10% below its 200-day moving average. Price and AVWAP trend readings are negative, while sequential growth and momentum are neutral. Investor sentiment stayed positive but weakened, slipping from 0.25 to 0.16. That suggests expectations had cooled meaningfully without turning hostile.
The bottom line is that United Parks missed on both lines and abandoned its 2026 growth expectations. It also lost the buyback lever that flattered per-share results. Even so, pass sales, deferred revenue and admission pricing have inflected in a way that supports management's case for 2027. Investors now have to weigh better forward demand indicators against a rising cost base, a thin cash cushion and higher leverage, with a management team whose recent forecasts have not held.
Read our earnings preview for United Parks & Resorts Inc.: https://www.earningswhispers.com/article/PRKS/22169
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 8 hours | |
| 8 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-26 | |
| Oct-13 | |
| Oct-08 | |
| Sep-29 | |
| Sep-22 | |
| Sep-20 | |
| Aug-04 | |
| Aug-04 |
