Ingevity Hits The Whisper, But Pavement Weakness, Slower Organic Growth, And A Delayed APT Sale Take The Shine Off A 24% EPS Gain
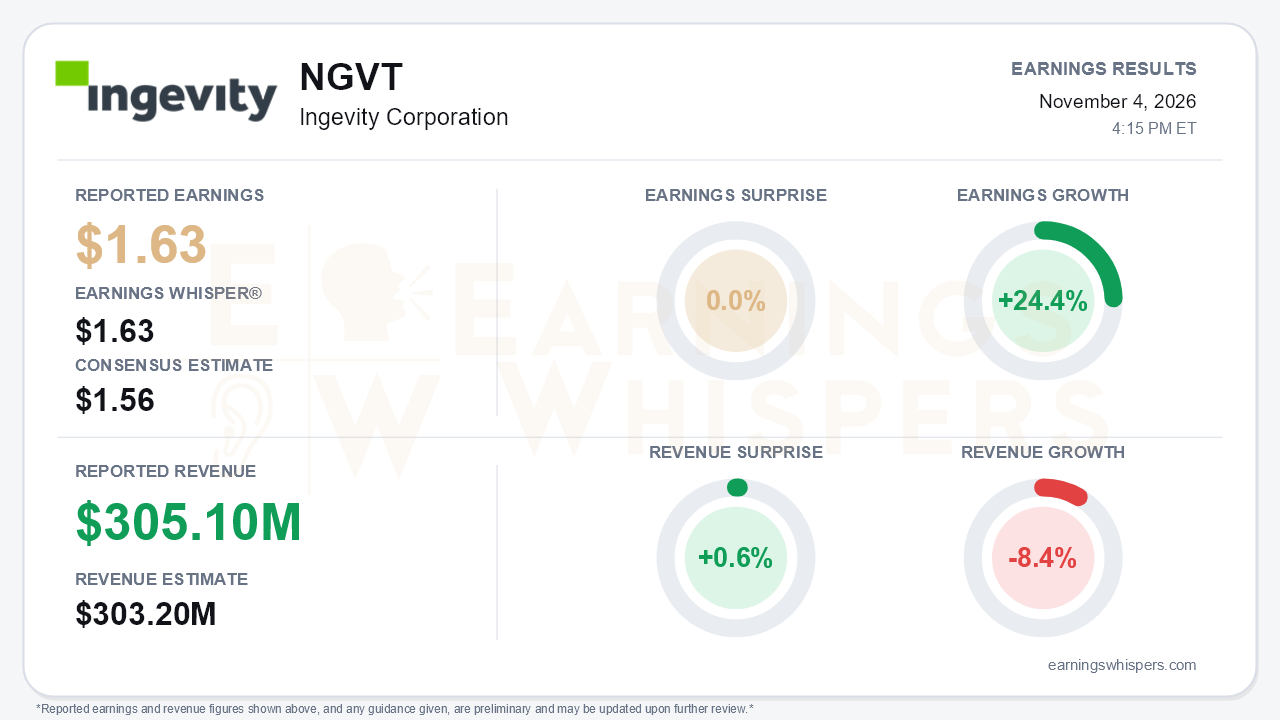
Ingevity (NYSE: NGVT) reported third-quarter adjusted earnings of $1.63 per share. That matched the Earnings Whisper number exactly and beat the $1.56 consensus. Revenue of $305.1 million came in 0.6% above expectations but fell 8.4% year over year, mostly because the Road Markings product line was sold in April. Adjusted EPS grew 24.4%, and adjusted EBITDA margin expanded 230 basis points to 35.4%. On the surface, the quarter shows a leaner, higher-margin portfolio. Underneath, momentum slowed noticeably from a strong second quarter. That is the central tension.
The quality of the EPS growth deserves scrutiny. Adjusted EBITDA from continuing operations actually fell $2.4 million to $108.0 million. Most of the per-share gain came from items below the operating line:
- Diluted shares fell to 34.9 million from 37.0 million after roughly $125 million of buybacks so far this year.
- Net interest expense dropped to $13.5 million from $18.4 million.
- Depreciation and amortization fell by about $7 million.
The margin expansion is real, but it partly reflects portfolio subtraction. Lower SG&A and the absence of prior-year indirect costs tied to divested businesses helped. Excluding Road Markings, sales rose just 2%, down from 5% growth in the second quarter. GAAP results were solid: continuing-operations EPS was $1.46, up from $1.10. Still, investors are being paid more by financial engineering and mix than by volume.
The segment picture explains the slowdown.
- **Performance Materials** remains the anchor. Sales were $154.1 million and EBITDA was $83.4 million, with a steady 54.1% margin. North American hybrid demand and filtration pricing offset softness in China and Europe. However, both sales and EBITDA were flat, after growing 4% and 6%, respectively, in the second quarter.
- **Pavement Technologies** was the clear disappointment. Segment EBITDA fell $7.3 million to $19.6 million, hit by lower volumes, stranded dis-synergy costs from the Road Markings sale, and higher input and logistics costs. On the call, management said asphalt costs are up about 50% in some U.S. regions. That is pushing customers toward maintenance rather than new paving and slowing warm-mix adoption. Management now concedes that the mid-single-digit 2027 growth target for the segment will be hindered.
- **Advanced Polymer Technologies** grew sales 18%. But its margin fell 280 basis points to 26.0%, because input-cost surcharges carried little incremental profit.
The forward signals are mixed, and the risks look more immediate than the catalysts.
On the positive side, filtration is becoming a credible growth leg. Management cited several more municipal PFAS water-treatment contracts since the first win in the second quarter. It also highlighted biogas and RNG purification as a rapidly growing new application. The filtration upgrade contributed roughly 15% year-over-year improvement, and management expects acceleration into 2027. It also reaffirmed that Performance Materials should land within its 2027 Investor Day ranges.
On the negative side, three developments weigh on the outlook:
- **APT sale timing slipped.** Management described the deal as at an "advanced stage" last quarter. Now it says an announced agreement may not come until early 2027.
- **Free cash flow guidance was trimmed.** The full-year range moved to $220–$230 million from $220–$245 million, reflecting higher capex and working capital.
- **Guidance was narrowed, not raised.** The adjusted EBITDA outlook was tightened to $385–$395 million around an unchanged midpoint, after a raise last quarter. Management flagged fourth-quarter pressure in all three segments.
The tone shifted accordingly, from "outstanding execution" in July to "resilience" amid a "mixed global demand environment."
Market positioning reflects that cooling. Earnings Whispers investor sentiment remained positive but weakened modestly, slipping to 0.19 from 0.27 ahead of the prior report. The shares have gone essentially nowhere since that report: at $73.73, they are 0.4% below the $74.05 open that followed the July release. The stock sits about 3.3% above its 200-day moving average of $71.34, a constructive but not commanding position. The Earnings Whispers trend readings are mostly positive on price momentum and AVWAP, but the sequential-growth reading is negative. That split mirrors the fundamental story: healthy earnings power with fading growth.
The bottom line is that Ingevity delivered the earnings number investors were looking for, but not the kind of quarter that extends the bull narrative. Strong margins, a shrinking share count, and lower interest costs drove 24% EPS growth even as adjusted EBITDA slipped and organic growth slowed. Meanwhile, Pavement Technologies is under real cost pressure, free cash flow guidance edged down, and the APT exit is taking longer than promised. Filtration and the durability of Performance Materials keep the longer-term story intact. Bears, however, now have legitimate evidence that near-term momentum has peaked, and fourth-quarter execution in Pavement Technologies, plus clarity on the APT sale, will matter more than the headline beat.
Read our earnings preview for Ingevity Corporation: https://www.earningswhispers.com/article/NGVT/21887
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-07 | |
| Sep-17 | |
| Sep-03 | |
| Aug-18 | |
| Aug-05 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-16 |
