CRA International Beats And Raises Again As Revenue Accelerates, But Margins And Taxes Limit Earnings Growth
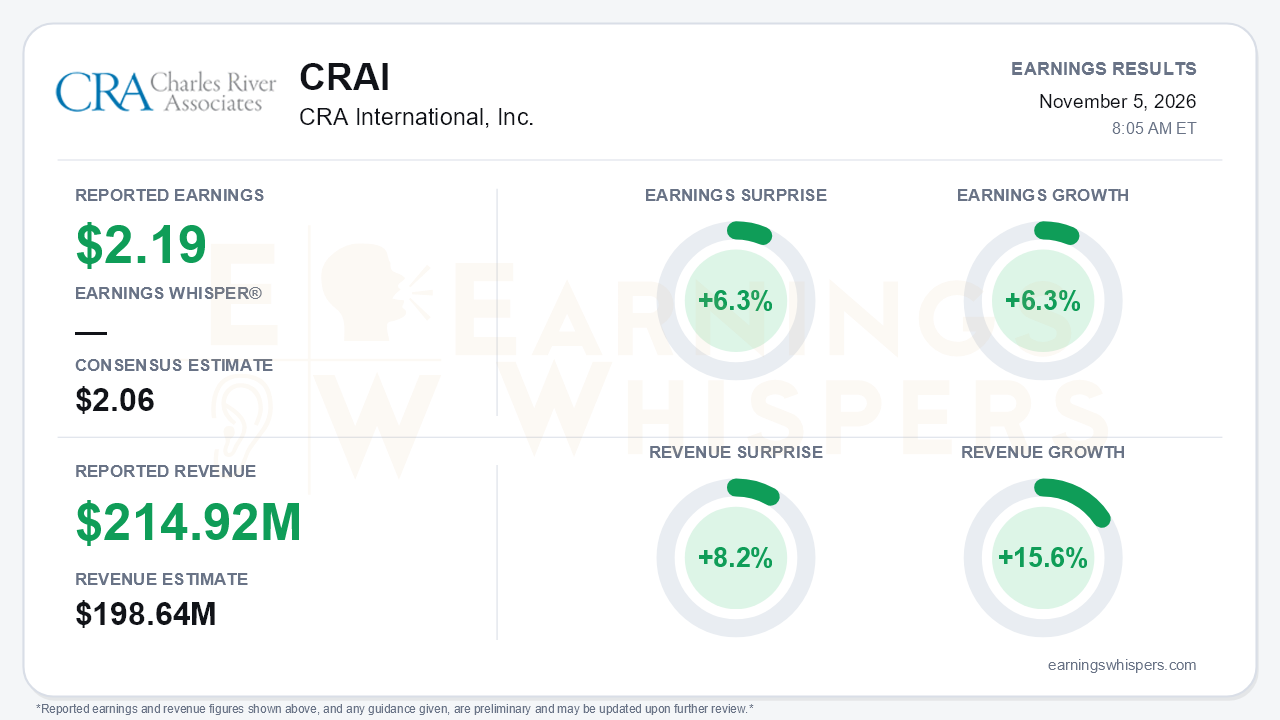
CRA International delivered its strongest third quarter on record, but the quarter's real message is that the top line is running well ahead of the bottom line. Non-GAAP earnings of $2.19 per share beat the $2.06 consensus by 6.3% and grew 6.3% year over year. Revenue of $214.92 million topped the $198.64 million consensus by 8.2% and rose 15.6%. That revenue growth extends a clear acceleration, from 10.5% in the first quarter to 12.8% in the second and now 15.6%. Management raised full-year revenue guidance for the second consecutive quarter, to $830 million to $840 million on a constant-currency basis. That compares with $805 million to $820 million last quarter and an original $785 million to $805 million. Revenue growing more than twice as fast as non-GAAP EPS is the central tension in an otherwise impressive report.
The quality of the earnings beat deserves scrutiny. GAAP diluted EPS jumped 27.2% to $2.20, but that comparison is flattered by $3.7 million of restructuring and separation charges in the year-ago quarter. On a non-GAAP basis, net income rose just 1.5% to $13.9 million, and net margin compressed to 6.4% from 7.3%. Non-GAAP EBITDA grew 11.2% to $27.1 million, yet EBITDA margin slipped to 12.6% from 13.1%. Below the operating line, net interest expense climbed to $2.6 million from $1.75 million, and the non-GAAP tax rate rose to 34.9% from 28.8% a year ago. A roughly 4% decline in the diluted share count, supported by $49.3 million of buybacks year to date, did meaningful work in turning flat non-GAAP net income into mid-single-digit per-share growth.
The operating picture underneath is stronger than the margin line suggests:
- **Broad-based growth:** Legal & Regulatory revenue grew 15.7%, up from 10.1% in the second quarter, and Antitrust & Competition Economics posted its seventh straight record quarter.
- **Hiring and utilization:** Consultant headcount rose 6.2% to 1,028, versus 3.3% growth in the second quarter and 2.5% in the first. Utilization still improved to 78% despite the seasonal intake of roughly 100 new consultants.
- **Pipeline:** Management said lead flow and new project originations grew more than 20% year over year, up from double-digit growth earlier in the year.
- **Cost leverage:** Non-GAAP SG&A fell to 14.9% of revenue from 16.3%.
The margin pressure is partly self-inflicted and deliberate. Forgivable loan amortization tied to talent investment is expected to rise by about $15 million this year, with roughly $14 million already booked.
The pressure points are real, however. Management narrowed EBITDA margin guidance to 12.2%–12.8% from 12.0%–13.0%. The top end came down and the midpoint was unchanged, so the revenue raise is not translating into higher profitability expectations. Other cracks also showed:
- Management Consulting growth cooled to 9.8% from about 25% in the second quarter.
- Seven practices grew, versus eight earlier in the year.
- International growth decelerated sharply against tough comparisons.
- The 34.9% tax rate, driven by proposed Section 162(m) regulations, exceeded the 33%–34% second-half guide.
- Days sales outstanding rose to 117 from 113 last quarter and 100 in the first quarter. Year-to-date operating cash flow was an outflow of $43.9 million.
- Global M&A value fell 41% sequentially in the third quarter. Because antitrust work tends to lag deal activity, that is a potential future headwind for CRA's strongest franchise.
On the positive side, management cut net debt to $129.6 million from $197.6 million last quarter and raised the dividend 17.5% to $0.67, a clear statement of confidence.
Investors were not leaning bullish heading into the print. Sentiment was already negative and weakened further, falling from -0.57 to -0.73. The stock, however, told a different story. Shares sat at $194.75 ahead of the report, up 7.4% from the open after the August release and 17.4% above the 200-day moving average. They had also rallied about 24% off the September 23 low of $156.97, though they remained 5% below the October 26 high of $204.94. Earnings Whispers trend readings were mostly positive, consistent with that price action. The setup is therefore unusual: skeptical sentiment paired with a stock that had already priced in much of the recovery in growth.
The bottom line is that CRA's demand engine is accelerating, with record revenue, faster hiring, stronger originations and a second guidance raise. But margins are flat at best, and non-GAAP earnings growth is being held back by investment spending, higher taxes and higher interest costs. Bulls can point to a credible growth story and a pipeline that is still building. Bears have legitimate ammunition in the unchanged margin outlook, stretched receivables and a softening M&A backdrop. With the stock trading well above its 200-day average, converting revenue momentum into margin expansion is the next test.
Read our earnings preview for CRA International, Inc.: https://www.earningswhispers.com/article/CRAI/22076
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-28 | |
| Oct-22 | |
| Oct-06 | |
| Oct-01 | |
| Sep-29 | |
| Sep-25 | |
| Sep-23 | |
| Sep-22 | |
| Sep-17 | |
| Aug-06 |
