Oscar Health Turns An Expected Loss Into A $0.49 Profit And Raises Guidance Again, But A $250 Million Risk-Adjustment Gain Did Much Of The Work
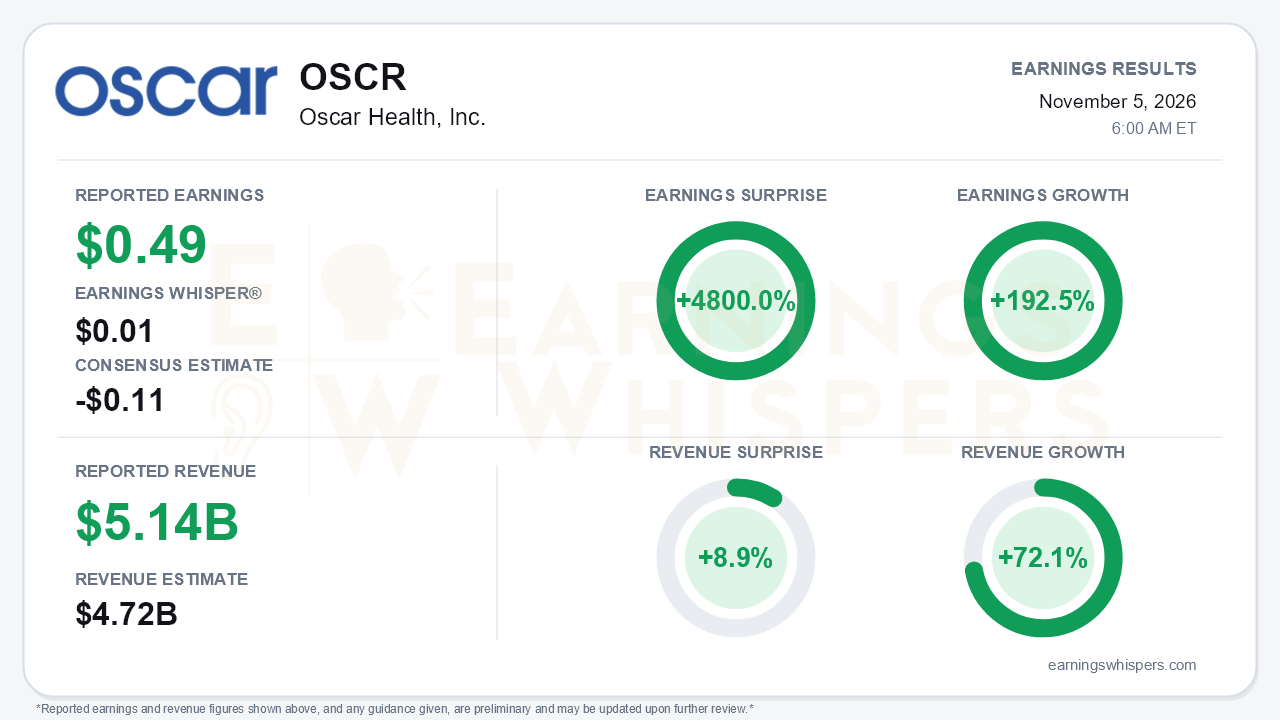
Oscar Health delivered the kind of third quarter that bears were not positioned for. The ACA-focused insurer earned $0.49 per diluted share. Wall Street had expected a loss of $0.11, and the Earnings Whisper number was only $0.01. That works out to a 4800.0% surprise and 192.5% earnings growth from the year-ago loss of $0.53 per share. Revenue of $5.139 billion topped the $4.72 billion consensus by 8.9% and grew 72.1% year over year. Management also raised its full-year earnings-from-operations outlook for the third time in 2026, to $850-$950 million from $600-$800 million. The headline is unambiguously strong. The quality of the beat, however, deserves scrutiny.
The central issue is risk adjustment. Third-quarter revenue included a $250 million benefit from updated risk adjustment estimates. Oscar attributed it to favorable development in its risk scores relative to the market and modestly better market morbidity than expected. That benefit exceeds the quarter's entire $178.0 million in earnings from operations. Without that true-up, the quarter looks far less impressive. Favorable prior-period development on medical costs also halved, to $42 million from $84 million a year ago. The medical loss ratio still improved to 84.0% from 88.5%, which management credited to disciplined pricing. But it has climbed sharply through the year from the 70.5% Oscar posted in the first quarter, the expected seasonal pattern for an ACA book as members work through deductibles. The guidance math reinforces the point. Year-to-date operating earnings already total $1.27 billion, so the updated range implies an operating loss of roughly $320-$420 million in the fourth quarter. The midpoint of the raise, about $200 million, is also smaller than the $250 million risk-adjustment benefit booked this quarter.
That does not erase real operating progress. Effectuated membership rose 27% to roughly 2.69 million from 2.12 million. Rate increases and enrollment growth combined to drive premium revenue up more than 70%. The SG&A ratio fell to 14.0% from 17.5%, helped by fixed-cost leverage and lower risk adjustment as a share of premium. It also edged below the 14.2% reported in the second quarter. Investment income rose to $91 million from $53 million on a much larger float. Full-year targets moved favorably across the board: revenue to $19.0-$19.3 billion, MLR to 80.5%-81.5%, and SG&A to 15.1%-15.6%. Stockholders' equity has more than doubled since December to $2.2 billion.
Investors should be careful with the cash figures. Operating cash flow of $3.5 billion for nine months was inflated by a $1.9 billion increase in payables to CMS, which are risk adjustment obligations that will be paid out. Oscar's cash pile is partly a timing item, not purely earned liquidity. The available conference-call record contained no substantive discussion, so management's updated views on several key issues could not be assessed. Those include membership churn, utilization, and 2027 pricing. That leaves the open questions from the second-quarter call unresolved:
- second-half churn expected at roughly 2%-4% per month, driven by CMS program-integrity disenrollments;
- elevated outpatient utilization;
- a seasonal MLR increase and higher SG&A ratio in the fourth quarter;
- the 2027 enrollment environment.
The release's own risk factors flag the expiration of enhanced premium tax credits and new ID-proofing rules. CEO Mark Bertolini's claim that Oscar can grow share and expand margin in 2027 is a management expectation, not yet a demonstrated result.
The market setup is more complicated than the surprise implies. Shares closed at $35.19 the day before the report, up 27.8% since the open following the August release. That leaves the stock nearly 48% above its 200-day moving average and just 2.7% below the 52-week high of $36.16 set on November 4. In other words, the stock entered earnings near the top of an inter-earnings range that began at a $25.37 low in early August. Much of the improvement was already being priced in. Investor sentiment moved the other way, slipping from mildly positive (0.08) to mildly negative (-0.08). The shift is modest, but it suggests the rally outpaced conviction. The trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that Oscar is on track for its most profitable year by a wide margin, and the third raise to guidance is a genuine achievement. This quarter's upside, though, leaned heavily on a favorable risk-adjustment estimate rather than core underwriting alone. The guidance also implies a sizable fourth-quarter loss, and the stock entered the print near its highs. The burden of proof now shifts to 2027 pricing, churn, and whether margin gains hold without one-time help.
Read our earnings preview for Oscar Health, Inc.: https://www.earningswhispers.com/article/OSCR/22160
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 11 hours |
Oscar Slips As LifeStance, HCA Climb On Earnings, Payment Hike
OSCR -5.71%
Investor's Business Daily
|
| 12 hours | |
| 14 hours | |
| Nov-04 | |
| Oct-30 | |
| Oct-28 | |
| Oct-21 | |
| Oct-20 | |
| Oct-15 | |
| Oct-12 | |
| Oct-01 | |
| Sep-21 | |
| Sep-20 | |
| Sep-18 |
