AMSC Beats On Revenue But Pull-Ins Push December Guidance Lower While Orders And Backlog Build
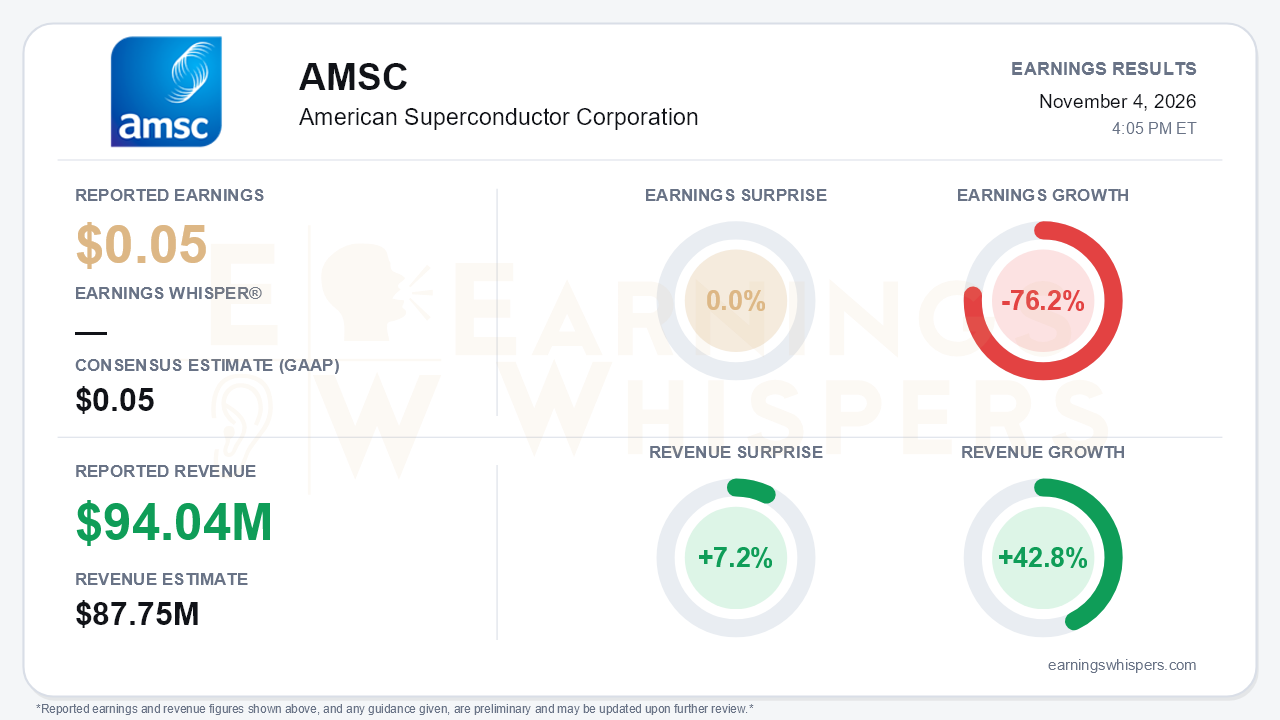
American Superconductor delivered a quarter in which demand outran deliveries but the near-term outlook still stepped down. Revenue of $94.04 million beat the $87.75 million consensus by 7.2% and grew 42.8% year over year. Earnings of $0.05 per share matched the GAAP consensus, a 76.2% year-over-year decline. The release itself shows GAAP diluted EPS of $0.06 and non-GAAP EPS of $0.20, or $0.19 diluted, flat with a year ago. The central tension is that orders, backlog and cash flow all improved meaningfully, yet management guided the December quarter below Street expectations because customers pulled deliveries forward.
The quality of the beat deserves scrutiny. Revenue was essentially flat sequentially at roughly $94 million for a second straight quarter. Year-over-year growth was strong, but it depends partly on the Comtrafo acquisition as well as organic expansion. Gross margin improved about 190 basis points from the first quarter to 28%, helped by better Comtrafo utilization, but it remains below the 31% posted a year ago. Comtrafo purchase-accounting amortization will keep weighing on cost of revenue through the fiscal year. Operating costs also rose:
- SG&A climbed to $18.3 million from $13.4 million.
- Stock-based compensation nearly doubled to $6.5 million.
- Operating income still improved to $5.4 million from $3.0 million, but that figure includes a $1.3 million gain from a change in the fair value of contingent consideration.
What collapsed GAAP earnings was taxes. Income tax expense jumped to $3.4 million from $0.1 million, so pre-tax income rose while net income fell to $3.0 million from $4.8 million.
Cash generation was the cleanest part of the report. Operating cash flow was $32.7 million in the quarter, up from $16 million in the first quarter. First-half operating cash flow reached $48.7 million versus $10.6 million a year earlier, lifting cash, equivalents and restricted cash to $181.9 million. Investors should note that a $16.4 million increase in deferred revenue, reflecting customer prepayments, did much of the work. That signals demand strength, but it is not purely a margin story. Capital spending also stepped up to $14.4 million in the half.
The call preserved a credible growth story and was management's most bullish of the past four calls.
- **Orders:** Second-quarter orders exceeded $95 million. First-half orders totaled about $230 million, more than double the prior-year period, and quarterly orders are averaging above $100 million this fiscal year versus about $70 million in fiscal 2025.
- **Backlog:** Twelve-month backlog reached about $320 million, up roughly 50% year over year and about $20 million above the first-quarter level.
- **Comtrafo in North America:** The first Comtrafo transformer delivered into North America, a 165 MVA unit commissioned for a Texas solar-plus-storage project, arrived about two years ahead of the original 2028 expectation. Management says similar-scale North American projects are in the pipeline.
- **Other demand drivers:** Management cited a roughly $200 million semiconductor pipeline that is not yet in backlog, new data center orders and deliveries, and a surge in military quoting. The military revenue impact is not expected until 2028-2029.
- **Margin targets:** Management reiterated its goal of returning gross margin to the 30% range and lifting non-GAAP net margin to the low teens.
Bears have legitimate ammunition in the guidance. Third-quarter targets are revenue above $80 million, non-GAAP net income above $7 million ($0.15 per share) and GAAP net income above breakeven. All three sit below the second-quarter guide of more than $85 million, more than $8 million and more than $1 million. Management blamed customer pull-ins that borrowed from the December quarter, a holiday slowdown, and a large semiconductor/materials project that will be built in the third quarter but cannot ship until the fourth. Management expects the fourth quarter to end the year "on a high note." That framing is plausible given the backlog, but it is still a forecast. Rising project sizes are making quarterly results lumpier. Policy and election uncertainty and Middle East instability were also flagged as variables for traditional energy investment.
The market had already been skeptical heading into the print. Shares at $26.26 are down 11.4% from the open following the August report and sit about 25.5% below the 200-day moving average of $35.26. Investor sentiment remained negative but improved modestly, moving from -0.171 to -0.132. The Earnings Whispers trend readings are split: sequential growth and momentum are positive, while price and AVWAP trends remain negative. That split mirrors the gap between improving operating data and weak stock behavior.
The bottom line is that AMSC's demand picture strengthened more than its headline EPS suggests. Record cash flow, $320 million of near-term backlog, an earlier-than-expected North American transformer entry and a sizable semiconductor pipeline all point to a larger business ahead. However, flat sequential revenue, margins still below year-ago levels, a tax-driven GAAP earnings decline and a soft December-quarter guide leave the near-term setup unresolved. For a stock trading well below its long-term average, proof will likely require a fourth quarter that converts the pull-in narrative into a clear sequential reacceleration.
Read our earnings preview for American Superconductor Corporation: https://www.earningswhispers.com/article/AMSC/22517
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-30 | |
| Oct-29 | |
| Oct-13 | |
| Oct-05 | |
| Sep-15 | |
| Aug-05 | |
| Aug-05 | |
| Jul-31 | |
| Jul-28 | |
| Jun-04 |
American Superconductor CEO Puts AI Data-Center Growth In Perspective
AMSC
Investor's Business Daily
|
| May-28 | |
| May-28 |
