Watts Water Beats And Raises Again As Data Centers And Pricing Offset Softer Construction, But 2027 Tailwinds Are Fading
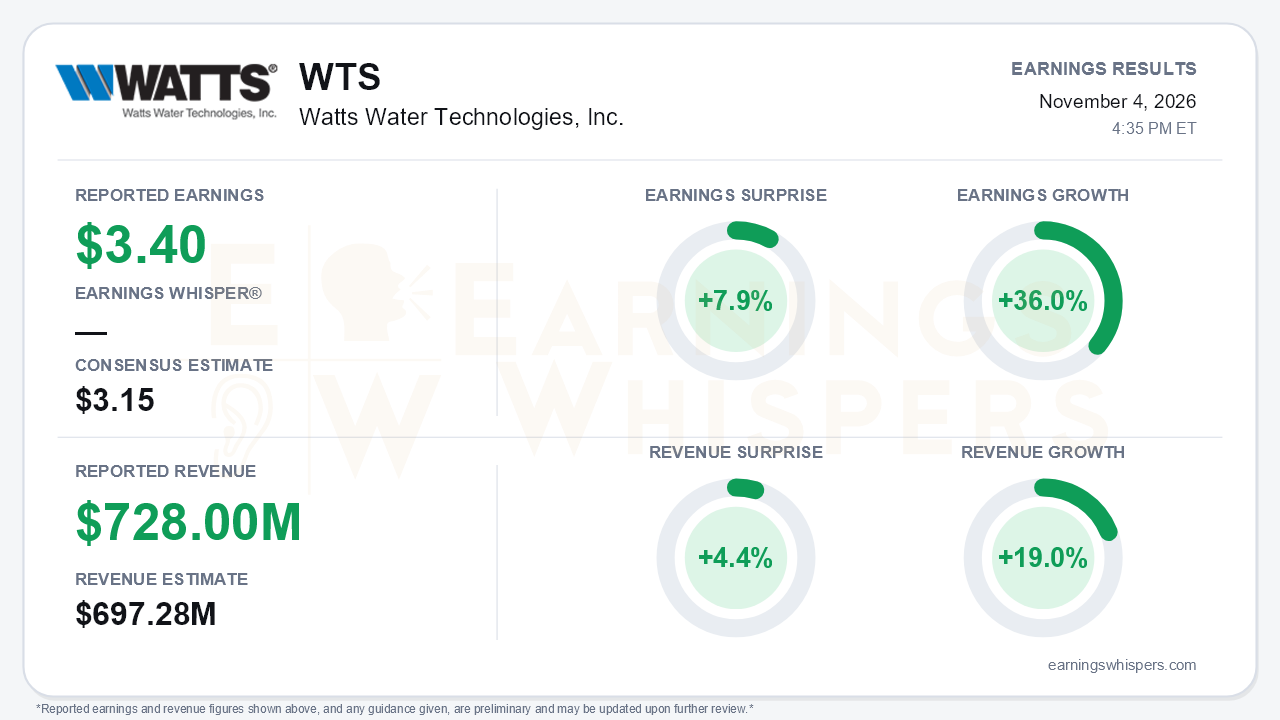
Watts Water Technologies delivered a clean third-quarter beat that also accelerated. Adjusted EPS of $3.40 topped the $3.15 consensus by 7.9% and rose 36.0% year over year, double the 18% growth posted in the second quarter. Revenue of $728.0 million beat the $697.28 million consensus by 4.4% and grew 19.0%. Organic growth of 12% far exceeded the 5-8% management had guided for the quarter only three months earlier. Management raised full-year guidance for the third straight time. The central tension is that the drivers powering 2026 are not ones management expects to repeat at the same strength in 2027. Data-center growth faces hard comparisons, pricing is set to normalize, and the core construction market is getting worse rather than better.
The quality of the beat holds up better than the GAAP headline suggests, but it deserves some unpacking. GAAP diluted EPS of $4.34, up 77%, was inflated by $39.3 million of tariff refunds worth $0.94 per share. Management properly excluded those refunds from adjusted results. On an adjusted basis, operating margin expanded 240 basis points to 20.9%. That reversed a 60-basis-point contraction in the second quarter and beat the company's 19.8-20.4% guide. All three segments improved:
- Americas margin rose 180 basis points to 25.5%, after falling 150 basis points in Q2.
- Europe margin rose 230 basis points to 14.5%.
- APMEA margin rose 170 basis points to 21.1%.
The less flattering detail is how much of the top line came from outside the core. Acquisitions contributed roughly 7 points of reported growth. Price realization, which ran near 8% in the first quarter and 6% in the second, was largely tariff-driven. Cash conversion also slipped. Free cash flow of $230 million for nine months covered just 63% of net income, versus 84% a year ago, despite the refund benefit. Receivables climbed and inventory was built ahead of data-center demand.
Data centers remain the engine. Management said the category is now tracking at the high end of mid-to-high single digits as a percentage of sales, up from roughly 3% in 2025. China data-center projects that customers pulled forward drove APMEA organic growth of 30%. Capacity is being added in China and at Superior Boiler for CoolVault tanks. Europe was a pleasant surprise, with 9% organic growth helped by price, easier comparisons and renewed heat-pump incentives. Full-year Europe organic guidance moved to 5-6%, from 1-4% previously and a decline of up to 4% back in February.
Guidance improved across the board:
- Full-year organic growth is now 11-12%, up from 8-11% in August and 2-6% at the start of the year.
- Adjusted margin expansion was tightened to the top of the range, at 70-80 basis points.
- Every segment's growth and margin outlook was raised, and no metric was cut.
The forward-looking caveats are substantive. CEO Robert Pagano said non-institutional commercial and residential new construction are "slightly worse" than planned three to six months ago, with project softness now visible on the ground. He said that weakness extends into 2027. Management also said data-center growth will not match the 2025-2026 pace against tough comparisons, and it assumes 15-20% market growth. Pricing for 2027 is expected to revert to a normal increase of about 2%. The implied fourth quarter already shows deceleration:
- organic growth of 9-12%;
- operating margin expansion of only 10-70 basis points;
- APMEA margin guided between down 50 and up 10 basis points on volume deleverage.
Free-cash-flow conversion guidance of at least 90% was held rather than raised. Inflation, trade policy and the Middle East conflict remain live risks.
The market appears to have been weighing that 2027 debate before this report. Shares traded at $353.30 on the report date, down 8.1% from the $384.29 opening after the August release, even as that quarter's guidance raise played out. The stock still sits about 6.5% above its 200-day moving average of $331.76, so the pullback has not broken the longer-term trend. Investor sentiment remained positive but edged lower, from 0.35 to 0.33, a modest cooling rather than a shift in tone. Earnings Whispers trend readings are mixed, with momentum positive while AVWAP is negative.
The bottom line is that Watts posted an accelerating, broad-based beat-and-raise with genuine operating leverage. The adjusted numbers stand on their own without the tariff windfall. However, the quarter leaned on three supports that management itself says will weaken next year: outsized data-center growth, tariff-driven pricing and acquisition contributions. Meanwhile, the core new-construction market is softening. Bulls can point to a credible data-center franchise and a net-cash balance sheet of about $347 million. Bears have legitimate ammunition in the implied fourth-quarter slowdown and the 2027 comparisons. The stock's slide since August suggests investors are already pricing the second half of that argument.
Read our earnings preview for Watts Water Technologies, Inc.: https://www.earningswhispers.com/article/WTS/21972
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-27 | |
| Oct-13 | |
| Oct-07 | |
| Oct-01 | |
| Sep-04 | |
| Aug-05 | |
| Aug-05 | |
| Aug-03 | |
| Jul-09 | |
| Jul-08 | |
| Jun-16 |
