Ingredion Misses As Argo Recovery Stalls, Cuts 2026 Outlook For The Third Straight Time
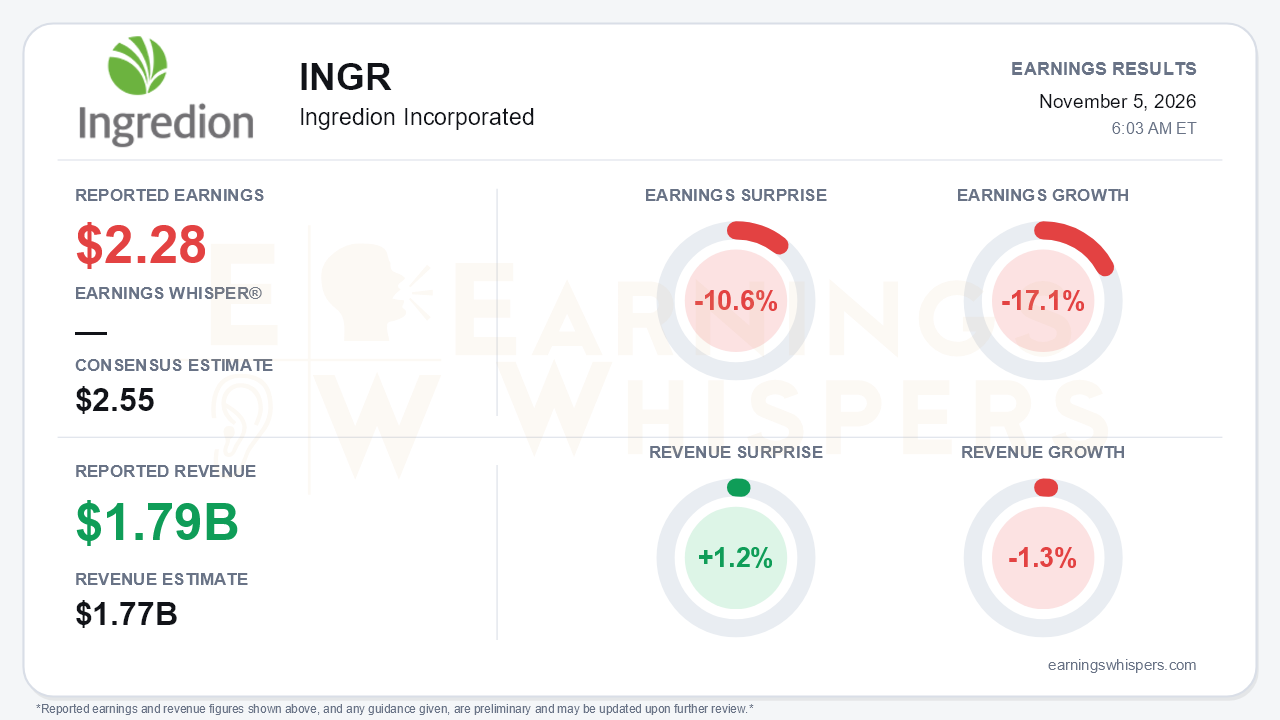
Ingredion's third quarter was a clear miss, and the guidance cut matters more than the miss itself. Adjusted EPS of $2.28 fell 10.6% short of the $2.55 consensus and declined 17.1% year over year. Revenue of $1.792 billion was 1.3% lower than a year ago but beat the $1.77 billion consensus by 1.2%. That modest top-line beat offers little comfort. Management lowered full-year adjusted EPS guidance to $9.25-$9.70 from $10.30-$10.90 in August. It is the third consecutive reduction from an initial range of $11.00-$11.80, and it reverses the 'turned the corner' message from the second-quarter call. CEO Jim Zallie said plainly that results 'fell short of our expectations' and that the Argo recovery 'is taking longer than we expected.'
The deterioration is steep, and it is accelerating. Adjusted operating income fell 19% to $206 million, compared with a 5% decline in the second quarter. Management had guided full-year operating income to be down only mid-single digits. Adjusted EPS fell $0.47 year over year, versus just $0.05 in Q2. The damage came almost entirely from margin. Gross profit fell 12% to $399 million on essentially flat sales, and margin alone cost $0.72 per share. Volume added $0.05, while buybacks and other income cushioned the rest. GAAP EPS of $2.23 got help from a $17 million restructuring benefit, mainly a land sale gain in Australia. That gain was excluded from adjusted results, so it does not flatter the adjusted figure. It does, however, make reported operating income look better than the underlying business. On the top line, the 1% sales decline mostly reflects the Pakistan divestiture. Excluding Pakistan, sales rose 2%, but that growth relied on favorable currency.
The call explained why the decline sped up. In Food & Industrial Ingredients–U.S./CAN, operating income fell 36% to $52 million. About two-thirds of the shortfall came from Argo, where yields remain below industry levels and maintenance spending ran over budget. Volumes also fell 3%. Consumer softness in U.S. sweeteners and starches began in August and has continued into the fourth quarter. Management pointed to unit declines, trade-down and SNAP benefit cuts. Texture & Healthful Solutions remained the strategic bright spot, with a 10th straight quarter of volume growth. Clean label sales are up 8% year to date, and APAC clean label is up more than 30%. Even so, segment volume growth slowed to 2% from 7% in Q2. Tapioca costs, up roughly 65%, pushed segment operating income down 10% to $95 million. LATAM volumes improved to +4% on brewing and beverage demand. The stronger Mexican peso and the Colombia earthquake still cut segment profit 6%.
The guidance cuts are broad. Net sales are now expected to be flat, with no growth layered on top. Texture & Healthful Solutions operating income guidance fell to flat-to-up low single digits from up mid-to-high single digits. LATAM is now expected to be down mid-to-high single digits. U.S./CAN is expected to fall 35-40%. Operating cash flow guidance dropped to $650-$750 million, down from $820-$940 million at the start of the year. Year-to-date operating cash flow of $389 million trails last year's $539 million.
Management did offer some forward catalysts:
- Argo production has been stable for two quarters, inventories are rebuilt, and October yields improved by a couple of percent.
- 2027 peso exposure is hedged, and management expects tapioca and currency headwinds to ease next year.
- A new Brazil brewing contract, savings from the Cabo plant closure, and additional consolidation candidates provide cost levers.
- The Tate & Lyle acquisition remains targeted for a second-half 2027 close.
- New CFO Diego Reynoso joined October 1.
The problem is credibility. Bears have legitimate ammunition after three downgrades in a single year, and record diesel prices add freight and energy inflation that management cannot control.
The market had already priced in much of this skepticism. Shares closed at $97.36 ahead of the report. That is 5.7% below the open following the August release and 7.7% below the 200-day moving average of $105.45. The stock had slid from an inter-earnings high of $108.06 in late August to a 52-week low of $93.30 on October 28, and it entered the report only 4.4% above that low. Investor sentiment remained negative but improved from -0.56 to -0.42 heading into the release. That suggests some investors had begun positioning for stabilization, and this report undercuts that view. The Earnings Whispers trend signals lean negative, with price and AVWAP trends negative while momentum and sequential growth are neutral.
The bottom line is that Ingredion's operational recovery at Argo has not yet become a financial recovery. Weakening consumer demand and input inflation are now compounding the problem. Clean label growth and the Tate & Lyle combination keep a credible long-term story intact, and 2027 tailwinds from tapioca and the peso are plausible. Still, a company that has cut its outlook three times must prove that this guidance is the floor. Until it does, the shares are likely to trade on execution evidence rather than promises.
Read our earnings preview for Ingredion Incorporated: https://www.earningswhispers.com/article/INGR/22119
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| 17 hours | |
| 17 hours | |
| Oct-28 | |
| Oct-21 | |
| Oct-15 | |
| Sep-17 | |
| Sep-17 | |
| Aug-20 | |
| Aug-18 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-31 | |
| Jul-30 |
