Cummins Posts Record Margins But Misses On Revenue And Cuts Guidance For The First Time This Year
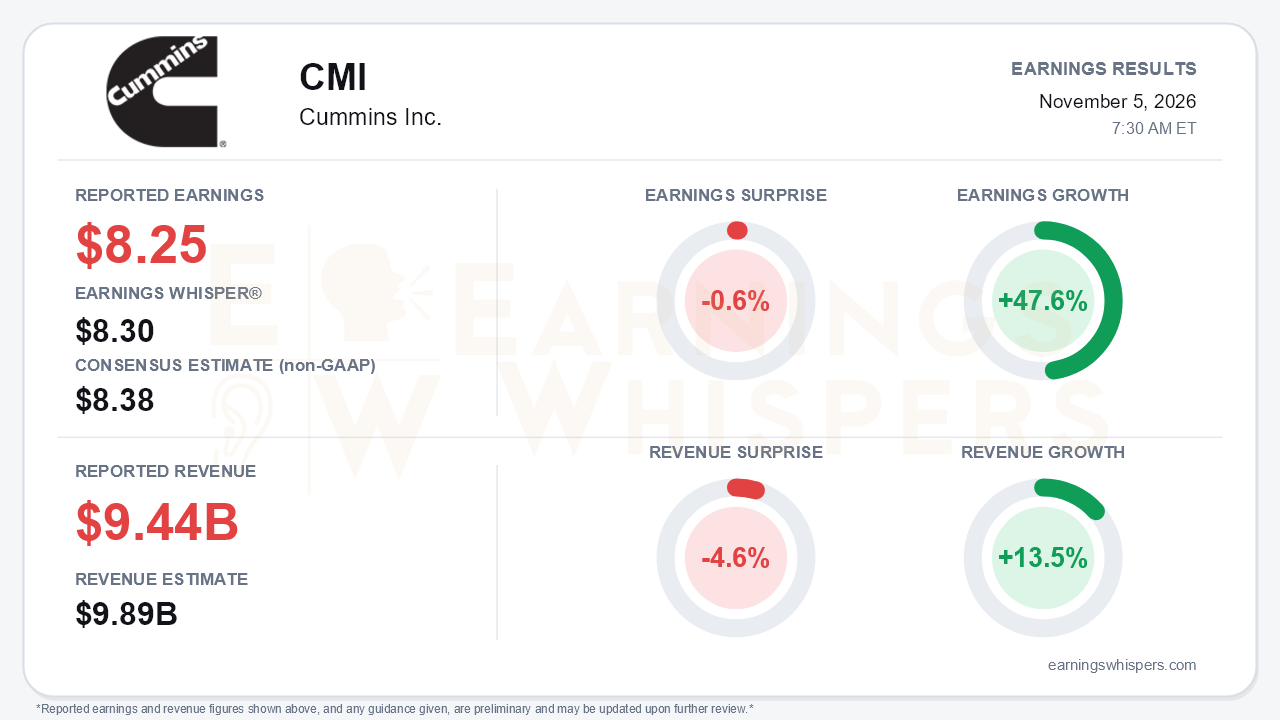
Cummins delivered a record-profitability quarter that still fell short of expectations. Third-quarter EPS of $8.25 missed the $8.38 consensus by 0.6% and came in just under the $8.30 Earnings Whisper. Revenue of $9.438 billion missed the $9.89 billion consensus by 4.6%, a wider shortfall. On the surface, growth looks excellent: earnings rose 47.6% year over year and revenue rose 13.5%, an acceleration from roughly 3% growth in the first quarter and 9% in the second. The central tension is that margins and growth improved while the top line fell short of expectations and full-year guidance was trimmed. After raising guidance in each of the first two quarters, management now expects revenue growth of about 10%, the bottom of the prior 10% to 13% range.
The quality of the EPS figure deserves scrutiny. The reported $8.25 is a GAAP figure, while consensus was on a non-GAAP basis. It also included $0.54 per share of favorable discrete tax items, which pushed the quarter's effective tax rate down to 17.7%. Without that tax benefit, the earnings miss would have been considerably wider. The year-over-year comparison is also flattered: the prior-year quarter carried $1.73 per share of Accelera charges, including a $210 million goodwill impairment. Even so, the operating improvement is real. EBITDA was a record $1.8 billion, or 18.9% of sales, versus 17.2% a year ago excluding special items and 17.5% in the second quarter. Gross margin reached a record 27.7%. Engine and Components margins expanded to 13.5% and 14.3%, helped by North American heavy-duty truck volumes. Distribution was the exception: segment EBITDA margin fell to 13.9% from 15.5% on only 4% sales growth.
Power Systems remains the engine of the story. Segment revenue hit a record $2.3 billion, and EBITDA margin reached 25.4%, up from 24.5% in the second quarter and 22.9% a year ago. Power generation sales within the segment rose to $1.56 billion. On the call, management said third-quarter power generation orders beat expectations and that international data center orders are now on par with the U.S. Management held its power generation growth outlook at 15% to 25%. The company also cited two new data center catalysts:
- its largest-ever battery energy storage award, for a U.S. data center project;
- a new cooling systems plant that more than doubles capacity in that business.
The weakness sits in trucks and in supply. Management attributed the revenue miss roughly half to pickup demand and half to a supplier constraint, which pushed about $200 million of Distribution revenue into the fourth quarter. Forecasts were cut in several places:
- North American pickup engine shipments to 118,000-122,000 units, from 125,000-140,000;
- medium-duty truck production to 125,000-130,000 units, from 130,000-140,000, as buyers wait on the final EPA 2027 rule;
- revenue and margin ranges for both the Engine and Components segments.
China truck units fell 15% as battery-electric adoption rises, and price-cost turned slightly negative. The guidance now depends on a sharp fourth-quarter ramp: management expects record revenue, which implies roughly a 23% sequential step-up in Distribution. The full-year outlook also implies Power Systems margin falling to about 22.5% in the fourth quarter. Bears have additional ammunition in the stop-use recommendation on HyLYZER electrolyzers, whose financial impact is unquantified and excluded from guidance.
Cash generation offers a partial counterweight. Operating cash flow was $1.4 billion, and the company returned $661 million to shareholders, including $359 million in buybacks. Inventories, however, rose $418 million in the quarter and about $1 billion year to date. That build is worth watching if the fourth-quarter ramp disappoints.
The market had already moved ahead of this report. Shares closed at $471.84 heading into earnings, down 18.5% from the opening price after the prior report. That leaves them 21.6% below the 200-day moving average and 28.6% below the August 5 high of $661.01. The stock entered the report essentially at its inter-earnings low, set the day before. Investor sentiment remained positive but weakened, falling from 0.35 to 0.25. Earnings Whispers price and AVWAP trend readings are negative, even as momentum remains positive. The skepticism was established before the guidance trim, so the cut partly validates a concern investors were already pricing in.
The bottom line is that Cummins' profitability engine, led by data center power generation, is running at record levels, but the quarter exposed how much the truck and pickup cycle and supply constraints can offset it. The miss was small on earnings and propped up by tax items. The larger issues are the revenue shortfall, the first guidance cut of the year, and a back-end-loaded fourth quarter. Until Cummins shows it can convert record power generation orders into revenue without supply friction, the stock's weak technical position reflects a credible debate rather than a mispricing that is obvious on its face.
Read our earnings preview for Cummins Inc.: https://www.earningswhispers.com/article/CMI/22068
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 7 hours | |
| 12 hours | |
| 13 hours | |
| Nov-04 | |
| Oct-29 | |
| Oct-28 | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 |
