Cadre Beats And Lifts The Low End Of Guidance, But A Pulled-Forward EOD Order And Shrinking Backlog Temper The Raise
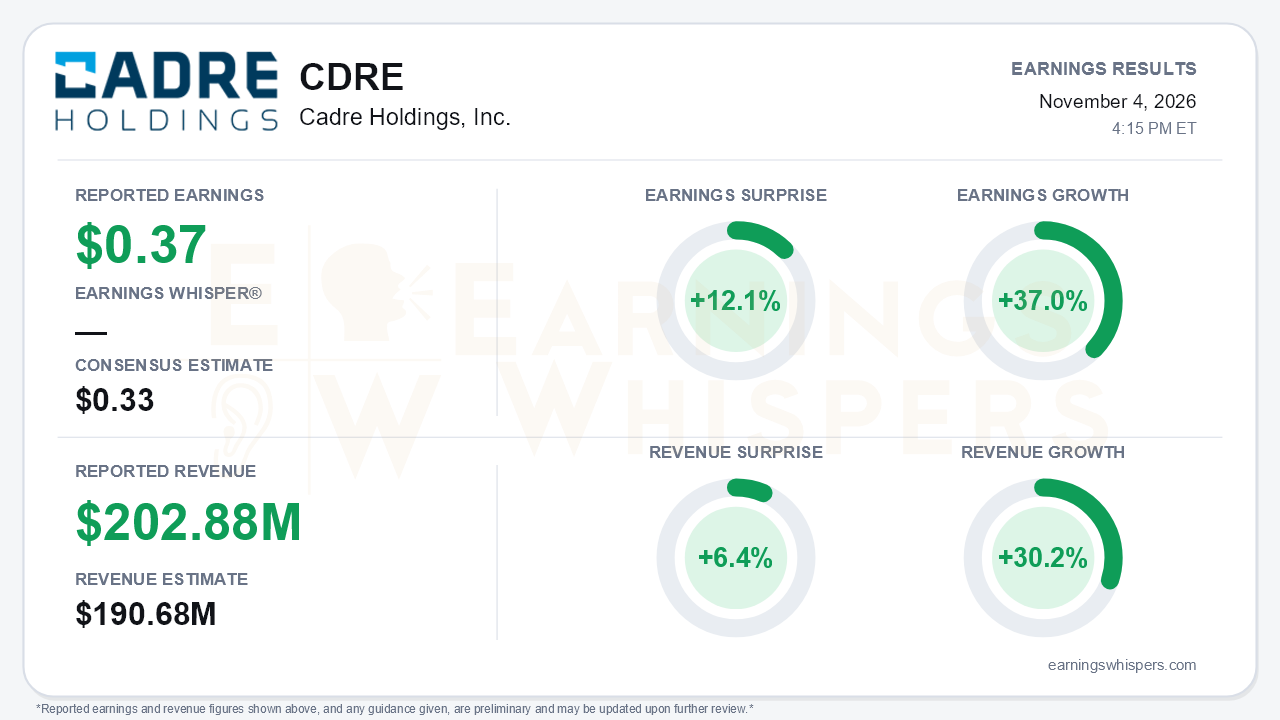
Cadre Holdings (NYSE: CDRE) delivered a clean third-quarter beat on the surface. EPS of $0.37 topped the $0.33 consensus by 12.1%, and revenue of $202.88 million beat the $190.68 million estimate by 6.4%. Earnings grew 37.0% year over year on 30.2% revenue growth. The company raised full-year guidance for the second straight quarter and announced its first share repurchase authorization, at $100 million. The quality of the beat deserves scrutiny, however. Roughly $10 million of the upside came from a next-generation bomb suit (NGABS) R&D shipment pulled into Q3 from later in the year. The guidance increase lifted only the low end of the range. That is the central tension: Q3 looked materially better than the full-year outlook actually changed.
The income statement shows real progress with some caveats. GAAP net income rose 46% to $16.0 million, while per-share growth was lower because diluted shares climbed to 43.5 million from 41.0 million. Gross margin improved to 43.4% from 42.7% on favorable pricing, which the company said was partially offset by unfavorable operating leverage. Product segment gross margin actually slipped to 43.7% from 43.9%, even as segment sales jumped about 36%. Distribution sales fell to $23.6 million from $26.5 million, though that segment's margin improved to 23.4%. Adjusted EBITDA rose to $41.1 million, a 20.2% margin, up 110 basis points and well above the roughly 18% management had signaled on the Q2 call. Tax expense doubled to $7.9 million, lifting the effective rate to roughly 33%. Third-quarter add-backs were modest. On a nine-month basis, though, GAAP net income of $29.4 million trails last year's $32.4 million, while adjusted EBITDA excludes $5.1 million of inventory step-up and $6.1 million of contingent consideration. In an acquisition-driven model, that GAAP-to-adjusted gap is worth watching.
The conference call preserved a credible growth story. Organic growth excluding distribution reached 10%, up from 5% in Q2 and a negative organic result in Q1. The Tier acquisition is tracking about $120 million annualized, against the $100 million assumed at close. Alien Gear is back near its roughly $20 million run rate, and armor and duty gear backlogs each rose just under 10%. Management sounded more confident, voicing explicit optimism about 2027 and introducing an AI efficiency narrative alongside the Cadre Operating Model.
The cracks are visible in the forward indicators:
- Total backlog fell about $29 million sequentially, after record levels in Q1 ($355 million) and Q2, as EOD and Tier orders shipped.
- Full-year organic growth was narrowed to 3-4% from 3-5%.
- Implied fourth-quarter revenue of roughly $197 million sits below Q3, reflecting caution on Tier's holiday and European seasonality.
- The high end of guidance is unchanged at $769 million in sales and $144 million in adjusted EBITDA, with new ranges of $756-769 million and $140-144 million. That is why Earnings Whispers characterizes the update as a narrowing rather than a clean raise.
The new catalysts are tangible but incremental. They include a roughly $25 million RCMP ballistic shield award for Tier, and a third BMO purchase order that brings that program above $20 million of a $50 million IDIQ. Cadre also announced a tuck-in of an EOD precision metal fabrication supplier, which carries about $4-5 million of external revenue and $1-1.5 million of EBITDA. On the risk side, Zircaloy's mid-teens margins and Alpha Safety's unfavorable mix continue to cap consolidated margin expansion. Consumer holster demand, about 8% of revenue, remains politically sensitive. The balance sheet tells two stories. Net debt rose $121.2 million since year-end to $305.6 million after $164.8 million of acquisitions, and cash fell to $63.9 million. Management nonetheless reports net leverage falling to 2.2x from 2.5x in Q2, helped by EBITDA growth and nine-month operating cash flow of $67.6 million versus $42.5 million a year ago. Given that cash level and a continued appetite for M&A, the pace of buybacks is an open question.
The market has not rewarded the improving numbers. Shares closed at $30.84, down 10.8% from the $34.59 open following the August report, even though that report also included a guidance raise. The stock sits 3.9% below its 200-day moving average of $32.09. Investor sentiment was essentially unchanged and still negative, edging from -0.2953 to -0.2806. Momentum and AVWAP readings have turned positive while the price trend is neutral, suggesting selling pressure has eased without a clear shift in direction.
The bottom line is that Cadre's operating execution, margin progress, and acquisition integration are better than the stock's recent performance implies. The buyback signals management confidence at these levels. Still, bears have legitimate ammunition. The Q3 upside was partly timing, backlog is shrinking from its peak, the organic outlook was trimmed, and the high end of guidance did not move. Whether sentiment can turn likely depends on Q4 landing near the implied $197 million and on backlog stabilizing heading into 2027.
Read our earnings preview for Cadre Holdings, Inc.: https://www.earningswhispers.com/article/CDRE/21801
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Oct-27 | |
| Oct-22 | |
| Oct-20 | |
| Oct-02 | |
| Sep-16 | |
| Aug-26 | |
| Aug-20 | |
| Aug-10 | |
| Aug-05 | |
| Aug-04 | |
| Jul-23 | |
| Jul-21 | |
| Jun-30 |
