Dorian LPG Posts Third Straight Record As Hormuz Disruption Lifts TCE To $97K; Asset Sales And A Net-Cash Pivot Hedge Against A Sudden Rate Reversal
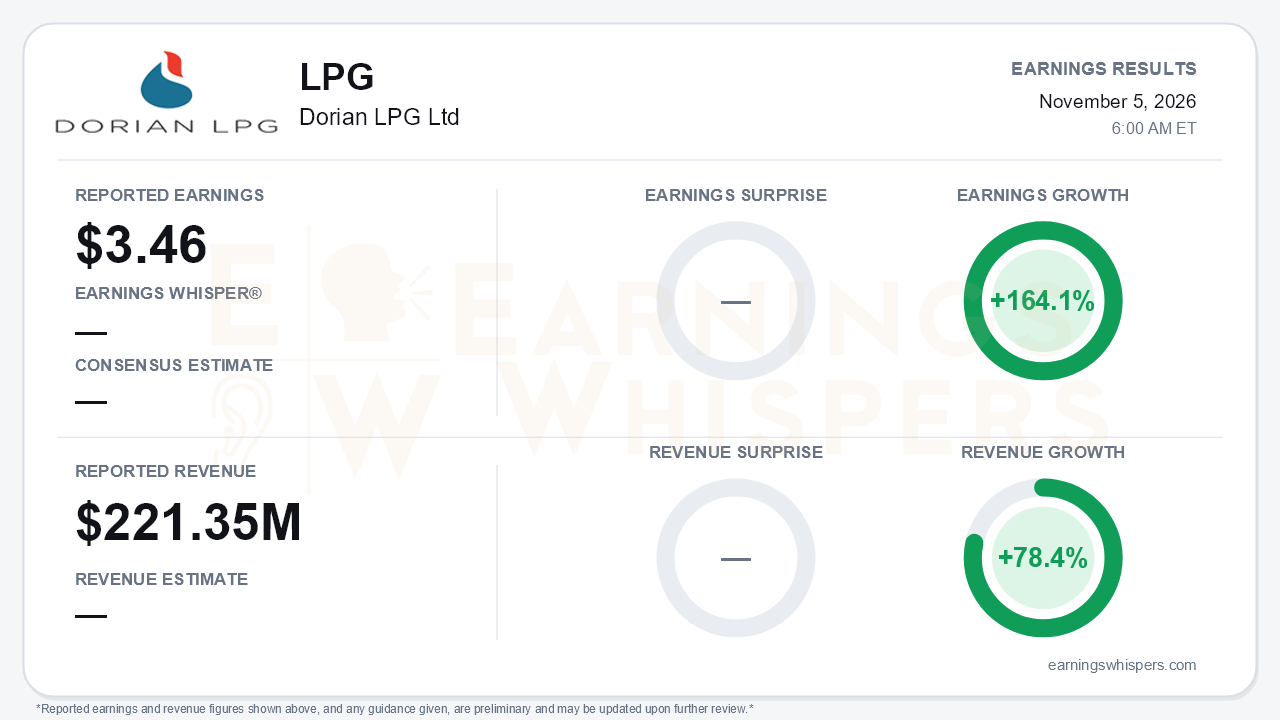
Dorian LPG delivered a third consecutive record quarter for the period ended September 2026. Adjusted earnings came in at $3.46 per share, up 164.1% from a year ago, on revenue of $221.35 million, up 78.4%. No consensus estimate was available, so there is no surprise to measure. Growth itself is the story, and it is still accelerating. The fleet's time charter equivalent rate reached $96,990 per available day. That compares with $75,926 in the June quarter, $63,615 in the March quarter and $50,333 in the December quarter. The central tension is that these earnings come almost entirely from a geopolitical shock: the effective closure of the Strait of Hormuz. Management is acting as though it knows that, monetizing ships at elevated values and building cash rather than adding spot exposure.
The headline numbers need careful reading. GAAP net income was $213.9 million, or $4.98 per diluted share. That figure includes $63.6 million, or $1.48 per share, of gains from selling the Corsair and Constellation in July. Adjusted EPS of $3.46 strips those gains out and compares with $1.31 a year ago. Adjusted EBITDA of $242.0 million also includes the gains; excluding them, the call put it at $178.4 million.
The operating gain was overwhelmingly rate-driven. Available days were essentially flat at 2,272 versus 2,290, and the benchmark Baltic LPG index averaged about $229 per ton versus $81 a year earlier. Costs are creeping higher beneath the surface:
- Daily operating expenses excluding drydock items rose 8.4% to $10,273 on crew wages and repairs.
- G&A climbed 16.8%.
- Charter-hire expense rose 33%.
- Bunker prices jumped to $826 per ton from $505.
Against a cash breakeven of roughly $27,000 per day, however, these pressures are immaterial at current rates.
The call reinforced how extreme conditions became during the quarter:
- Helios Pool spot and contract TCE hit $115,163, up from $82,445 in the prior quarter.
- The BLPG-3 route reportedly moved from roughly $82,000 to $198,000 per day during the quarter.
- Scrubber savings doubled to $4,174 per day.
Management's tone was its most confident yet. Executives described the sector as "short shipping" and argued that peace would ultimately be net positive. The release adds to the case for continued tightness. U.S. cargoes are replacing lost Middle East volumes on longer routes, Panama Canal congestion persists, and Chinese imports recovered. Notably, U.S. export terminals still ran below capacity for lack of ships. That cuts both ways: Gulf loadings fell to roughly 102 per month from about 113, a volume ceiling imposed by tonnage scarcity.
Capital allocation is where the setup changed most:
- **Dividend:** The irregular dividend rose to $1.25 per share, after $1.00 in each of the prior two quarters and $0.70 before that.
- **Ship sales:** Two more vessels, Captain John NP and Clermont, were sold in October for $167.4 million combined. Management says those sales will book more than $88 million of gains next quarter.
- **Refinancing:** A new seven-year facility, about $368 million at SOFR plus 140 basis points (roughly 60 basis points tighter), lifted undrawn revolver capacity to about $154 million from $41 million.
- **Balance sheet:** Quarter-end cash was $578.8 million. Management cited roughly $785 million of cash and about $320 million of net cash after the quarter. Debt-to-capitalization fell to 25.6%.
- **Newbuilds:** Dorian ordered three dual-fuel Panamax VLGCs from Hanwha for about $338 million, delivering in 2030. That brings the newbuild program to four ships.
The strategy reads as harvesting today's market while deferring reinvestment to a later cycle. The cost is a smaller operating base. Five ships have been sold this year, pool participation dropped to 26 vessels from 29, and spot exposure slipped to about 73%. The cash breakeven edged up to about $27,000 per day because fewer vessel days now absorb fixed costs.
The risks are well defined. Management acknowledged that rates could fall "very fast" if Hormuz reopens. Middle East exports remain at about half their pre-conflict levels, so a normalization would release substantial supply. The global VLGC/VLAC orderbook has swelled to about 36.4% of the existing fleet, with 160 vessels due through 2030, including 19 ordered in the quarter alone. The company's own seasonality disclosure flags the December and March quarters as typically weaker. The IMO net-zero vote is an additional regulatory unknown. A lower-than-usual spot share and a large cash cushion soften, but do not remove, the earnings sensitivity to a geopolitical de-escalation.
Market context is limited. Current price and sentiment readings were not supplied, so the post-report reaction cannot be assessed. For reference, shares opened at $45.12 after the August report, and the 200-day moving average now sits at $42.31.
The bottom line is that Dorian's fundamentals have rarely looked stronger, with record rates, a rising payout, cheaper financing and a net-cash balance sheet. The quality of those earnings, however, depends on disruption rather than structural demand growth. Investors are being paid generously, and management is visibly banking the windfall through ship sales and dividends. The open question is not whether this quarter was exceptional but how much of it survives a reopening of Hormuz and a wave of newbuild deliveries.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| 14 hours | |
| 15 hours | |
| 15 hours | |
| Oct-30 | |
| Oct-29 |
Energy Leader Dorian LPG Positioned To Hit Buy Point Ahead Of Earnings Results
LPG
Investor's Business Daily
|
| Sep-07 | |
| Sep-07 | |
| Sep-04 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-03 | |
| Jul-30 | |
| Jul-16 |
