Western Midstream Misses On EPS As Margin Compression And Heavier Costs Offset Record Volumes And A Better 2027 Outlook
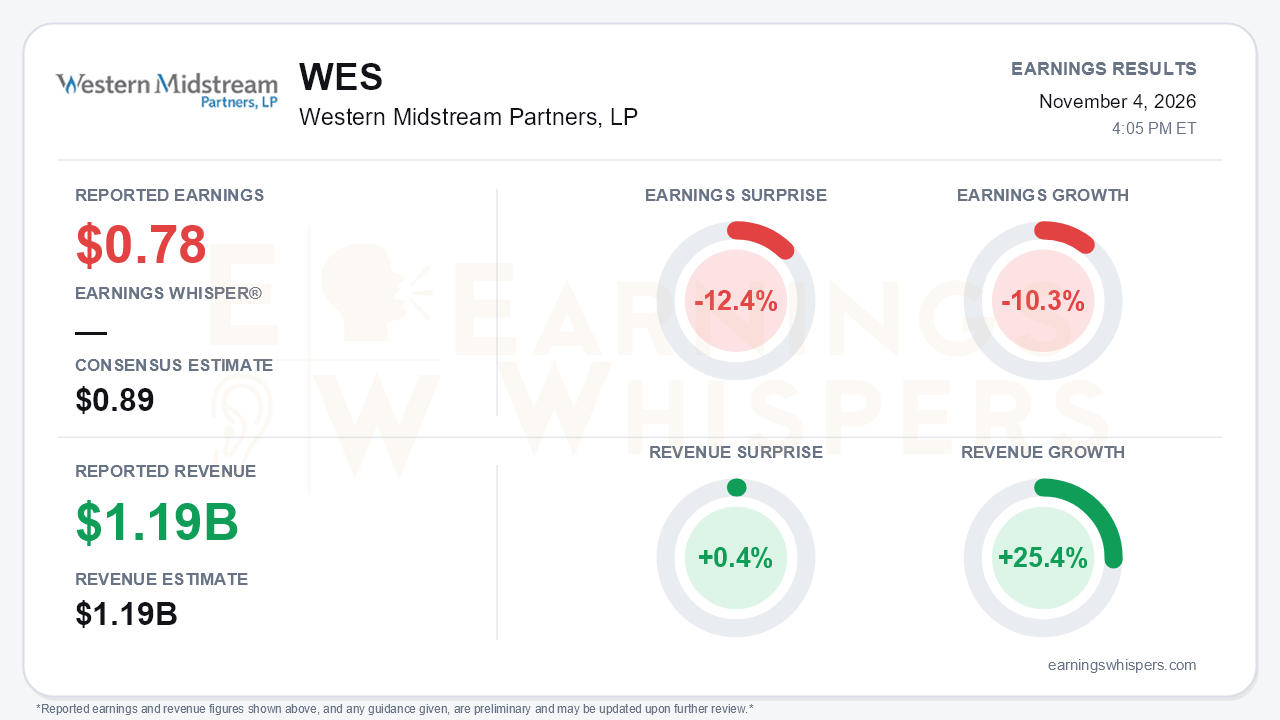
Western Midstream Partners (NYSE: WES) delivered a quarter in which record volumes did not translate into earnings. The partnership earned $0.78 per diluted unit, 12.4% below the $0.89 consensus and down 10.3% from a year ago. Revenue reached $1.194 billion, up 25.4% year over year and 0.4% above expectations. The central tension is that the business is getting bigger while each unit of throughput is earning less. Volume growth and the Brazos Delaware acquisition are lifting the top line, but higher costs, more units outstanding, and falling per-unit margins absorbed that growth before it reached unitholders.
The quality of the miss deserves scrutiny because it was not a single-item problem.
- **Operating costs:** Operation and maintenance expense rose to $291.5 million from $212.4 million a year earlier, and depreciation climbed to $223.8 million from $170.3 million.
- **Financing costs:** Interest expense increased to $116.6 million from $92.4 million as long-term debt grew to $8.88 billion.
- **Unit count:** Diluted weighted-average units rose to roughly 415 million from 383 million, diluting per-unit results.
- **Cash flow metrics:** Adjusted EBITDA of $708.3 million was up 12% year over year but fell from Q2's record $736.5 million. Distributable cash flow slipped to $512.3 million from $537.2 million, and free cash flow eased to $244.2 million from $263.6 million.
After funding the unchanged $0.93 distribution, free cash flow was negative $148.5 million. The balance sheet reflects that gap: cash fell to $44.5 million from $819.5 million at year-end, alongside $266 million of net commercial paper borrowing.
Operationally, the volume story is genuinely strong.
- Natural-gas throughput hit a record 5.9 Bcf/d, up 8% sequentially.
- Delaware Basin gas jumped 20% to 2.6 Bcf/d, driven mostly by a full quarter of Brazos.
- Produced water set another record above 3.0 million barrels per day.
The weakness showed up in pricing and mix. Adjusted gross margin per unit fell sequentially across all three segments:
- natural gas, to $1.25 from $1.35 per Mcf;
- crude and NGLs, to $2.93 from $3.21 per barrel;
- produced water, to $0.89 from $0.96 per barrel.
Management attributed the sequential EBITDA decline to lower crude and NGL pricing, DJ Basin throughput declines, and seasonally higher maintenance expense. The DJ softness is not fully resolved. Management said DJ declines resumed in July with no clear near-term catalyst, even though full-year DJ gas expectations were lifted to low-single-digit growth.
The call preserved a credible growth story, and arguably improved it. Management now expects 2026 Adjusted EBITDA above the $2.85 billion midpoint, more than $250 million above February's original midpoint, or more than $150 million excluding Brazos. Volume outlooks also improved:
- 2026 crude and NGL throughput moved from a decline to low-single-digit growth.
- Produced-water growth was nudged to 85-90%.
- Brazos activity is running above the underwriting case, with tie-in to the West Texas Complex expected by mid-December.
- Pathfinder start-up was pulled forward into late Q4.
Management explicitly framed 2027 as a growth year across all three product lines, a clear shift from the earlier "transition year" language. Longer-dated optionality includes:
- the 7.5% Solitude Pipeline stake;
- long-lead orders for a roughly 300 MMcf/d Delaware plant, with sanction targeted for early 2027;
- a $98 million Eddy County water bolt-on;
- new Powder River agreements.
Bears have legitimate ammunition, however.
- **Margin guidance:** The 2026 crude/NGL margin guide was trimmed to $3.05-3.10 per barrel. Guidance for 2027 implies gas margins of $1.25-1.30 per Mcf and oil margins of $3.00-3.05 per barrel, both below 2026 levels. Only water margins move higher.
- **Cash flow guidance:** Distributable cash flow and free cash flow guidance were reaffirmed, not raised, even as EBITDA expectations moved up.
- **Capital spending:** Capex will land slightly above the $1.0 billion high end, and 2027 spending is expected to remain at a similar level.
- **Commodity exposure:** The outlook leans on roughly $85 oil in the second half, with commodity sensitivity raised to about $50 million per $10 move in WTI.
- **Throughput loss:** The Southwest Wyoming sale removes about 215 MMcf/d from 2027.
The market had already been leaning skeptical. Shares fell 9.5% from the $47.03 open after the August report to $42.54. That leaves the stock about 3.7% below its 200-day moving average of $44.17. Investor sentiment, slightly negative entering the quarter, became more negative, moving from -0.03 to -0.10. The shift is meaningful but not dramatic. The Earnings Whispers trend readings are mixed, with momentum positive but AVWAP negative, consistent with a stock that has not been rewarded for its volume gains.
The bottom line is that WES is executing well on growth and is tracking ahead of its EBITDA plan, but the per-unit economics are moving the wrong way. The EPS miss reflects real pressure from margin compression, rising interest and depreciation, and a larger unit base. The setup now hinges on whether 2027 volume growth can outrun lower guided margins and elevated capex. It also depends on whether cash flow can comfortably cover the distribution again after a quarter in which it did not.
Read our earnings preview for Western Midstream Partners, LP: https://www.earningswhispers.com/article/WES/21970
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-19 | |
| Oct-16 | |
| Oct-12 | |
| Oct-07 | |
| Sep-02 | |
| Aug-31 | |
| Aug-18 | |
| Aug-17 | |
| Aug-17 | |
| Aug-10 | |
| Aug-10 |
