Service Properties Trust Beats As Hotel Recovery Accelerates, But Guidance Cut And 2027 Maturities Overshadow The Upside
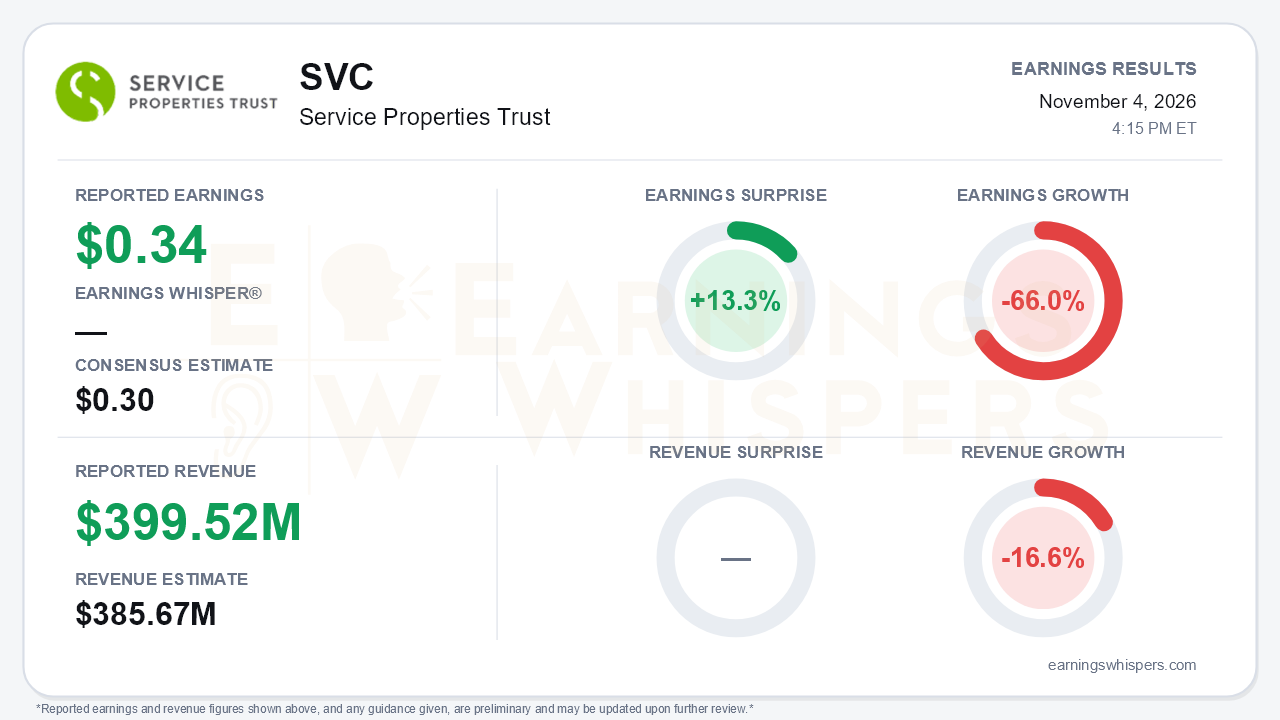
Service Properties Trust (NASDAQ: SVC) delivered a third-quarter beat, but the quarter's central tension is that the hotel recovery is gaining speed while full-year guidance moves the other way. The REIT reported earnings of $0.34 per share on revenue of $399.52 million. That topped the $0.30 consensus by 13.3%, and revenue beat the $385.67 million estimate by 3.6%. On a year-over-year basis, however, earnings fell 66.0% and revenue fell 16.6%. The revenue decline is consistent with a smaller hotel portfolio after 15 hotels were sold in 2026. Management's preferred measure tells a different story: normalized FFO rose 29.3% to $43.8 million and also beat consensus. Investors should note that the two bases diverge sharply. Much of the FFO improvement came from $17.4 million of lower interest expense after roughly $1.6 billion of debt was redeemed this year, which is a balance-sheet gain rather than an operating one.
The operating story on the retained hotels was the strongest in some time. Retained-hotel RevPAR grew 8.3%, up from 6.6% in the second quarter and 7.5% in the first, and well above the 1.7% of the fourth quarter of fiscal 2025. Excluding the Nautilus Miami Beach renovation, RevPAR grew 9.8%. Management said the portfolio outperformed the industry for an eighth straight quarter. More importantly, revenue growth is finally reaching the bottom line:
- retained adjusted hotel EBITDA rose 16.2% to $41.1 million, compared with gains of 4.2% and 2.1% in the prior two quarters;
- margin expanded 130 basis points to 15.4%.
There were blemishes. Food and beverage revenue fell 3.6%, repeat Las Vegas group business was lost, and Hurricane Lola hit the Kauai property.
Guidance is where bears have legitimate ammunition. Despite a raised RevPAR outlook, management cut nearly every major full-year target:
- Normalized FFO guidance fell to $113-128 million ($1.07-1.22 per share) from $124-144 million, a range that had been reaffirmed as recently as the second quarter.
- The top of the hotel EBITDA range dropped to $134 million from $144 million. Drivers were a later-than-expected Nautilus Phase 3 opening, which defers about $3.8 million of EBITDA, and widening losses at exit hotels during the sale process.
- Net lease NOI guidance fell $7 million at the midpoint to $373-379 million on higher credit reserves, vacant-asset carrying costs and slower acquisitions as rates rose.
- Adjusted EBITDAre is now $489-498 million, against an original $500-520 million.
The net lease book itself looks steadier than the guidance cut suggests. TA rent coverage climbed to 1.44x from 1.20x three quarters ago, occupancy improved to 97.6% from 96.6%, and two QSR franchisee bankruptcies were resolved with leases assigned to corporate franchisors. Even so, net lease cash NOI was flat year over year.
The call added real catalysts. Management quantified its retained-hotel margin plan for the first time, targeting about $109 million of incremental EBITDA over 12-24 months from a $139 million 2026 base and aiming for roughly a 20% margin. The plan has five components:
- $35 million from renovation lift;
- $7 million from synergies;
- $16 million from revenue mix;
- $38 million from lower customer-acquisition costs;
- about $13 million from market RevPAR.
The $38 million piece depends heavily on Sonesta and its new direct-booking platform launching in November, which makes it the most execution-sensitive component. Other near-term items include:
- the Nautilus reopening as the James Nautilus in the fourth quarter;
- signed LOIs on the final two exit hotels (795 keys);
- an expected revolver recast by year-end;
- 2027 demand events such as the Super Bowl in Los Angeles and the MLB All-Star Game in Chicago.
Rolling four-quarter cash available for distribution has also turned positive, compared with an $83 million deficit a year ago. The most striking disclosure was the board's rejection of an unsolicited, non-binding $2 billion proposal from TKO LLC for the hotel portfolio, which the board said significantly undervalued the assets. That signals confidence, but it also puts a public marker on hotel value that sits uneasily against the stock price.
The market has not been giving SVC the benefit of the doubt. Shares were at $6.28 on the report date, down 21.1% from the $7.96 open after the August report and about 24.2% below the 200-day moving average of $8.28. The Earnings Whispers trend signals are mostly negative, reflecting that persistent weakness. Investor sentiment nonetheless improved modestly, rising from 0.35 to 0.44, which suggests expectations were tilting more positive even as the price slid. The refinancing calendar likely explains part of the discount. The revolver matures in June 2027 and $580 million of zero-coupon notes come due in September 2027, while higher rates threaten to widen cap rates and slow transactions.
The bottom line is that SVC's hotel turnaround looks more credible operationally than at any point this year. Accelerating RevPAR, real margin expansion, a quantified EBITDA bridge and a rejected $2 billion bid all support management's thesis. However, the beat leaned on interest savings, full-year guidance was trimmed across the board, and 2027 maturities still need to be addressed. Until the company converts the margin plan into delivered EBITDA and clears its refinancing hurdles, the gap between the operating momentum and the share price is likely to persist.
Read our earnings preview for Service Properties Trust: https://www.earningswhispers.com/article/SVC/21945
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Sep-17 | |
| Aug-05 | |
| Aug-05 | |
| Jul-09 | |
| Jul-08 | |
| Jul-02 |
