South Bow Beats On A Weaker Quarter As Leverage Falls Faster And Prairie Connector Permitting Stays Unclear
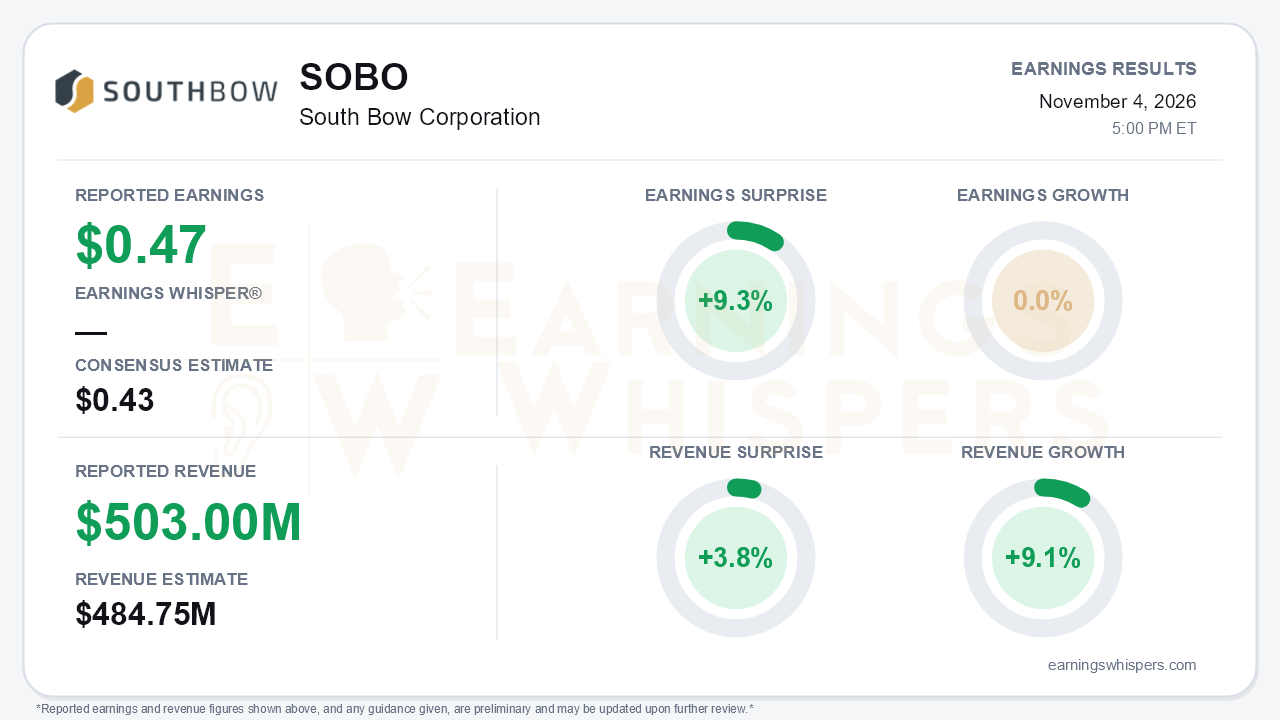
South Bow (TSX: SOBO) reported third-quarter earnings of $0.47 per share, 9.3% above the $0.43 consensus. Revenue of $503.0 million beat the $484.75 million estimate by 3.8% and grew 9.1% year over year. Earnings, however, were flat at 0.0% growth. That gap is the central tension in the quarter. Revenue came in strong, but the operating engine cooled noticeably from a record second quarter. Normalized EBITDA was $248 million, which management called in line with expectations. That figure was down 11% from Q2's $280 million and slightly below the $254 million earned a year ago. The beat came against a consensus that had already priced in a softer quarter, not from accelerating fundamentals.
The quality of the quarter deserves scrutiny. On a GAAP basis, net income rose to $99 million ($0.47 per share) from $93 million ($0.45) a year earlier. Normalized EPS of $0.47 was unchanged year over year and down from $0.50 in Q2. The softness sat squarely in the core Keystone Pipeline System segment, where normalized EBITDA slipped to $234 million from $259 million in Q2 and $260 million a year ago. Gulf Coast segment throughput fell to 663,000 bbl/d from 800,000 bbl/d in Q2, and Marketlink volumes dropped to 513,000 bbl/d from 642,000. Smaller marketing losses and a stronger Intra-Alberta segment ($17 million versus $11 million) cushioned the year-over-year comparison. Distributable cash flow rose 7% sequentially to $187 million, but the company attributed that to a one-time favourable current income tax adjustment rather than operating strength.
On the call, management explained the Q3 volume pullback with three factors:
- tighter differentials;
- low Cushing inventories;
- capacity outages tied to in-line inspection work.
These factors effectively unwound the trade-flow disruptions that had inflated Q2 demand for uncommitted capacity. Management offered a more constructive forward read. It said transportation differentials widened in Q4 and expects Western Canadian supply growth to outpace egress additions in 2027, with high asset utilization as its base case. The release also struck a cautious note: Gulf Coast conditions may stay volatile through 2027, which could temper uncommitted demand. Possible heavier refinery turnarounds and peer egress additions add further downside risk to the uncommitted volumes that drive variability around guidance.
The forward-looking package was mixed but leaned constructive:
- 2026 DCF guidance rose about 4% to roughly $690 million, after $655 million earlier in the year and $665 million in August.
- 2026 normalized EBITDA guidance of $1.04 billion was reaffirmed.
- Initial 2027 normalized EBITDA guidance is about $1.07 billion, helped by a full year of the Blackrod Connection Project.
- 2027 DCF is guided down to about $630 million on higher cash taxes.
- 2027 maintenance capital rises to about $40 million from $25 million.
The balance sheet is the clearest improvement. South Bow repurchased $320 million of senior notes for $314 million, and leverage fell to 4.3x from 4.4x in Q2 and 4.7x earlier in the year. The CFO now sees the 4.0x target likely reached by end-2027 rather than the original 2028-29 window, though a $600 million note matures in August 2027. Operationally, regulators approved the MP-171 remedial plan and pressure restrictions have begun lifting on certain segments. At Q1 that was only an expectation. A contractor fatality at Cushing remains under investigation, and the company named Heather Krislock COO and Richard Prior to a new chief commercial officer role.
The growth narrative is where bears have legitimate ammunition. Prairie Connector and Liberty Bridge still target a mid-2027 final investment decision. However, management repeatedly called permit-durability discussions 'complex and sensitive,' declined to share details, and referenced 'multiple pathways' that could shift timing. A post-midterm Democrat-controlled Congress adds uncertainty to those options. Pre-FID spending is held to $65 million with no steel purchased, and supply-chain pressure on electrical equipment from data-center demand could affect costs. The tone was less celebratory than in Q2, when the open-season win set the narrative, and more defensive on regulatory certainty.
The market has treated the stock cautiously. Shares are at $34.05, down 6.2% since the open after the August report and about 1.4% below the 200-day moving average of $34.53. Investor sentiment remained mildly positive but edged lower, from 0.078 to 0.068, a small shift that suggests expectations were essentially unchanged rather than reset. The Earnings Whispers trend readings are modestly supportive, with momentum and AVWAP positive while price trend is neutral.
The bottom line is that South Bow delivered a headline beat on a quarter that was sequentially weaker underneath. Keystone volumes and EBITDA retreated from an unusually strong Q2, and the DCF lift leaned on a tax benefit. What improved is the durability of the setup: faster deleveraging, raised 2026 cash flow guidance, modest 2027 EBITDA growth, and progress on MP-171. What did not improve is visibility on Prairie Connector, which remains the swing factor for whether South Bow becomes a growth story or stays a high-yield, slowly deleveraging toll road.
Read our earnings preview for South Bow Corporation: https://www.earningswhispers.com/article/SOBO/21942
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-01 | |
| Oct-27 | |
| Oct-07 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-08 | |
| May-29 | |
| May-07 | |
| May-07 | |
| Apr-30 | |
| Apr-09 |
