Graham Beats On Margins, But Slowing Revenue And Unchanged EBITDA Guidance Keep A Battered Stock's Setup Complicated
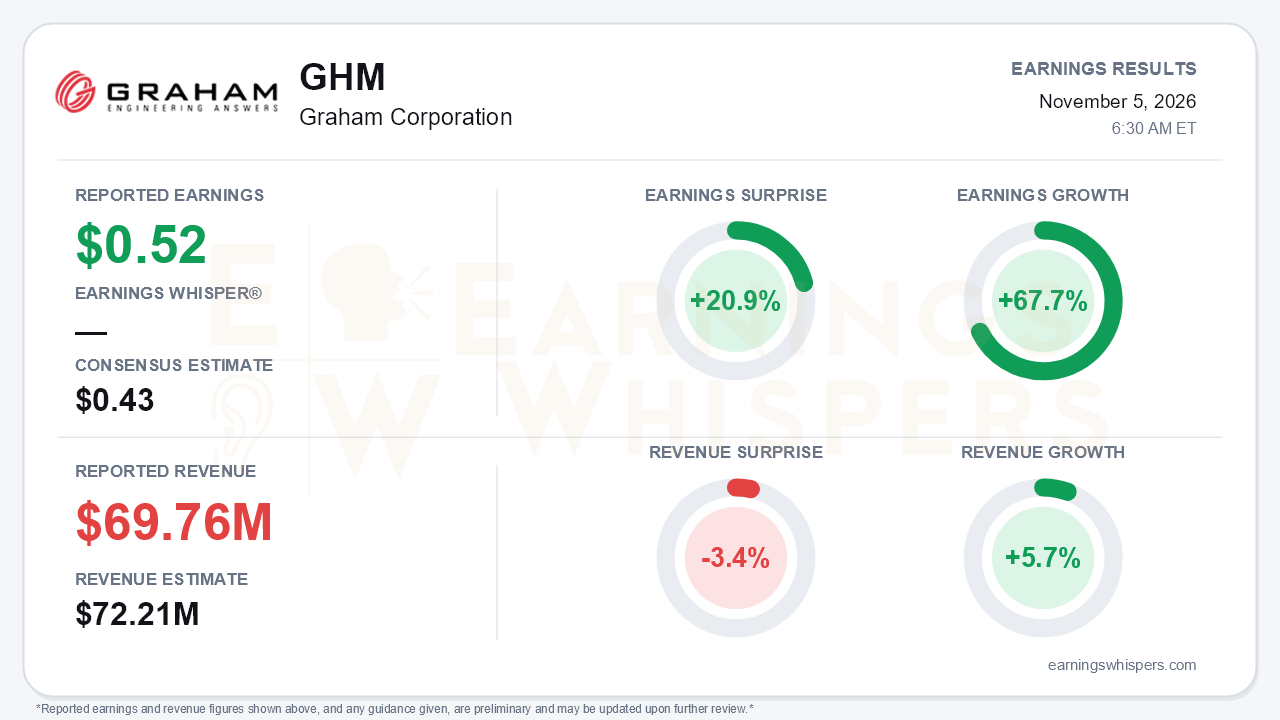
Graham Corporation delivered the kind of profitability quarter its long-term margin story depends on, but the top line went the other way. Adjusted earnings of $0.52 per share beat the $0.43 consensus by 20.9% and grew 67.7% year over year. Revenue of $69.76 million missed the $72.21 million consensus by 3.4%, and growth slowed to 5.7% from roughly 29% in the first quarter. Sales also dipped sequentially from $71.3 million. That is the central tension. Graham is clearly earning more on each dollar of work, but it is converting its record backlog into revenue more slowly than investors expected, and management kept full-year sales and adjusted EBITDA guidance unchanged rather than raising it.
The quality of the beat deserves scrutiny. Gross margin jumped 650 basis points to 28.2%, up from 25.0% in Q1. Adjusted EBITDA reached a record $10.3 million at a 14.8% margin, already inside the company's 14-16% fiscal 2029 target band. GAAP EPS rose to $0.39 from $0.28. Management credited better execution, healthier pricing on newer defense awards, and a richer mix from Space and FlackTek. Part of the gain, however, came from roughly $10 million less in low-margin material receipts than in the year-ago quarter. The CFO said gross margin should normalize from here. The revenue picture is also softer than the 6% headline suggests. FlackTek contributed $9.5 million in sales, so legacy revenue fell below last year's $66.0 million. Energy & Process dropped 17% on weak large capital project activity and lower non-U.S. sales, and aftermarket sales slipped 3% after rising 20% in Q1.
Guidance reflects that mix. Graham raised its fiscal 2027 gross margin outlook by about 50 basis points to 25-26%. It also lifted SG&A to 17.5-18.5% of sales on higher acquisition and integration costs, which leaves the $35-40 million adjusted EBITDA range unchanged. With $19.1 million of adjusted EBITDA already booked in the first half, that range implies no meaningful second-half acceleration. Q3 is also seasonally the weakest revenue quarter. Management additionally trimmed its expectation for backlog converting to sales within 12 months to 30-35% from 35-40%. For a stock that needs revenue to compound, that is arguably the most important change in the report: the $561.3 million backlog is a seventh straight record, but it is getting longer-dated.
Demand indicators were steady rather than accelerating. Orders of $73.7 million produced a 1.1x book-to-bill, down from $95.9 million and 1.3x in Q1, and backlog growth cooled to 12% year over year from 15%. Space orders fell to $10.6 million from $14.4 million, though first-half Space orders of $25.0 million still ran at 2.0x sales and Space backlog more than doubled. FlackTek's first-half book-to-bill of 1.3x, against 2.0x in Q1, implies a softer second quarter of bookings. There were real bright spots:
- Aftermarket orders rose 91% to $18.3 million.
- Defense backlog is 85% funded, according to the call.
- Radar cooling programs are moving toward rate production, and microreactor turbomachinery opportunities are reaching production.
- The company completed its first customer test at the Florida cryogenic facility and broke ground on the 30,000-square-foot Arvada expansion.
The balance sheet changed meaningfully. Cash rose to $71.4 million with no debt, and management described the M&A pipeline as full. Investors should note how that cash was built, though. The first half included $50.5 million of equity proceeds, and Q2's $46.7 million in operating cash flow was driven largely by the timing of collections and customer deposits rather than a sustainable earnings run rate.
The market had already turned skeptical before the report. Shares closed at $69.52 the day before earnings, down 34.4% from the $106.04 open after the August report and nearly 24% below the 200-day moving average of $91.19. The stock peaked at $116.63 in mid-August, then slid to a quarter low of $62.64 on October 22 and has recovered only about 11% from that level. Investor sentiment, already negative, deteriorated further to -0.53 from -0.34, a meaningful shift. Price and AVWAP readings remain negative even as momentum has turned positive. A sizable margin beat may ease some pessimism, but the revenue miss and reaffirmed guidance give bears legitimate ammunition.
The bottom line is that Graham proved its margin expansion is real and arriving ahead of schedule, but it did not show that revenue growth is re-accelerating. With gross margin expected to normalize, EBITDA guidance held flat, and backlog conversion stretched out, the next leg of the story depends on turning a record, increasingly long-dated backlog into faster sales growth.
Read our earnings preview for Graham Corporation: https://www.earningswhispers.com/article/GHM/22104
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-08 | |
| Aug-10 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-23 | |
| Jun-18 | |
| Jun-17 | |
| Jun-15 |
