CION Misses On NII As Rapid Deleveraging Shrinks Earnings Power And Forces A 17% Distribution Cut
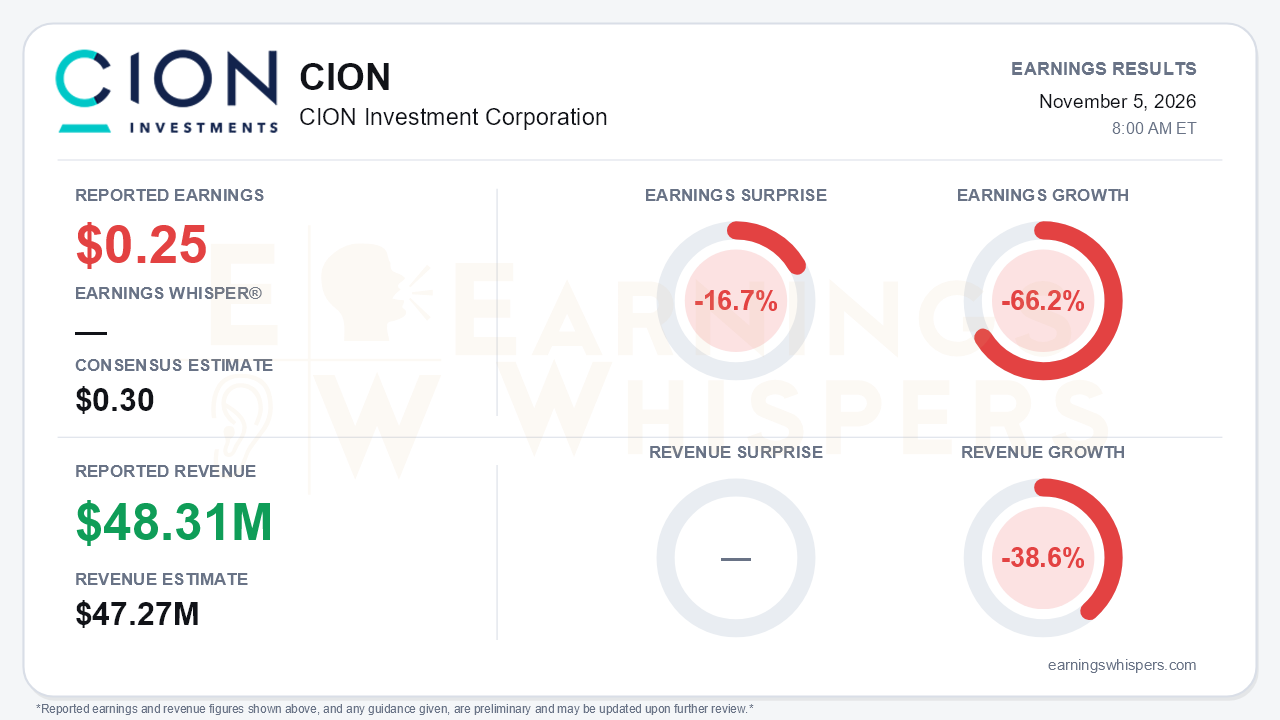
CION Investment Corporation finished the deleveraging it promised last quarter faster and more aggressively than planned. The cost is now visible in the income statement and the dividend. Net investment income came in at $0.25 per share, missing the $0.30 consensus by 16.7% and falling 66.2% from a year ago. Total investment income of $48.31 million beat the $47.27 million consensus by 2.2% but fell 38.6% year over year. On a GAAP basis, the net decrease in net assets from operations was $(0.07) per share, a sharp reversal from the $0.62 gain in the second quarter. That is the central tension. The balance sheet is materially safer, but the company that remains earns less, and management has reset the 2027 base distribution to $0.25 per quarter from $0.30.
The quality of the revenue beat deserves scrutiny. Interest income from non-controlled, non-affiliated investments fell to $17.4 million from $30.3 million a year earlier. Fee income from affiliated investments turned negative at $(2.9) million after a legacy transaction fee was reversed because its collectability is not reasonably assured. What held the top line above estimates was a $14.3 million dividend from affiliated investments, compared with $0.4 million a year ago. That is not a recurring interest stream.
The year-over-year earnings comparison is also distorted. Last year's $0.74 included $8.9 million of fee income from controlled investments. Sequentially, NII slipped from $0.29 back to the first quarter's $0.25. On the call, management attributed roughly $0.15 of one-time hits to the quarter, including about $0.03 from writing off debt issuance costs on the JPMorgan facility. Elevated legal and joint-venture formation costs pushed general and administrative expense to $2.8 million from $1.6 million.
The deleveraging itself was decisive:
- Balance-sheet debt fell from $1.17 billion to $897 million after CION repaid the $200 million JPMorgan facility and the $114.8 million of Israeli notes.
- Net debt-to-equity dropped to 1.30x from 1.52x, beating the roughly 1.35x target.
- About 90% of the debt is now unsecured.
The credit picture underneath is less reassuring. Net asset value fell 2.7% to $13.20, driven by realized losses on restructurings, including Thrill One, and markdowns at names such as Berlitz and Avison Young. Non-accruals rose to 1.63% of fair value and 4.85% of cost, up from 1.44% and 4.41%. The share of risk-rated 3 names climbed to 17.5% from 14.1%. First lien exposure fell to about 72% of the portfolio, while equity now represents 27.9%, including a Longview stake above 6% and a meaningful David's Bridal concentration.
The interest coverage figures also conflict. The release shows weighted coverage edging down to 1.82x from 1.87x, while call commentary cited roughly 1.6x versus about 2x. Either way, the direction is lower. New first lien spreads compressed to S+6.1% from S+8.1%, and cash fell to about $51 million from more than $160 million.
The tone shift from the prior quarter matters as much as the numbers. In the second quarter, the CEO called a dividend cut low probability. Three months later, the first-quarter 2027 distribution has been declared at $0.25, exactly matching this quarter's NII. That suggests the payout is being sized to current earnings rather than a recovery thesis. No shares were repurchased during the quarter despite the $130 million authorization announced earlier.
The forward catalysts are largely about monetization rather than organic growth:
- **Senior Loan Fund Partners:** The new joint venture bought 20 first lien loans at 99.8% of par, which supports existing marks. CION retained roughly $50 million of equity yielding about 12%.
- **Pearl:** The David's Bridal digital platform signed a letter of intent to merge with a SPAC at a $350 million pro forma enterprise value with a $75 million PIPE. The agreement is non-binding and targets a first-half 2027 close.
- **Longview Power:** The sale is still expected in the fourth quarter of 2026 or the first quarter of 2027, with management signaling significant gains intended to fund renewed buybacks.
The market entered the report cautious but less pessimistic. Earnings Whispers investor sentiment improved from -0.28 to -0.17, still negative but noticeably less so. Shares closed at $7.05 on the eve of the report, up 5.2% from the open after the prior release. That leaves them 2.3% below the $7.21 200-day moving average, 8.4% under the mid-August high of $7.70, and 12.8% above the October 21 low of $6.25. At roughly half of NAV, the stock already discounts considerable credit and earnings risk. Sequential-growth and AVWAP trend readings remain negative, consistent with a business still shrinking its earnings base.
The bottom line is that CION traded earnings power for balance-sheet safety, and this quarter showed the full cost of that trade: lower NII, a lower NAV, rising non-accruals, and a 17% distribution cut that contradicts management's earlier assurances. Bulls can point to cleaner leverage, loan sales near par, and potential gains from Longview and Pearl. Bears have legitimate ammunition in the weakening credit metrics, a growing equity concentration, and a revenue beat that leaned on one-time dividends. Until those monetizations close and core interest income stabilizes, the reset distribution looks like the realistic baseline.
Read our earnings preview for CION Investment Corporation: https://www.earningswhispers.com/article/CION/22066
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 9 hours | |
| Oct-28 | |
| Oct-22 | |
| Oct-22 | |
| Oct-01 | |
| Sep-29 | |
| Aug-06 | |
| Aug-06 | |
| Jul-14 | |
| Jul-01 | |
| May-07 | |
| Apr-06 | |
| Mar-15 | |
| Mar-12 |
