NexPoint Real Estate Finance Beats Estimates As Book Value Erosion And Weaker Q4 EAD Guidance Cloud The Quarter
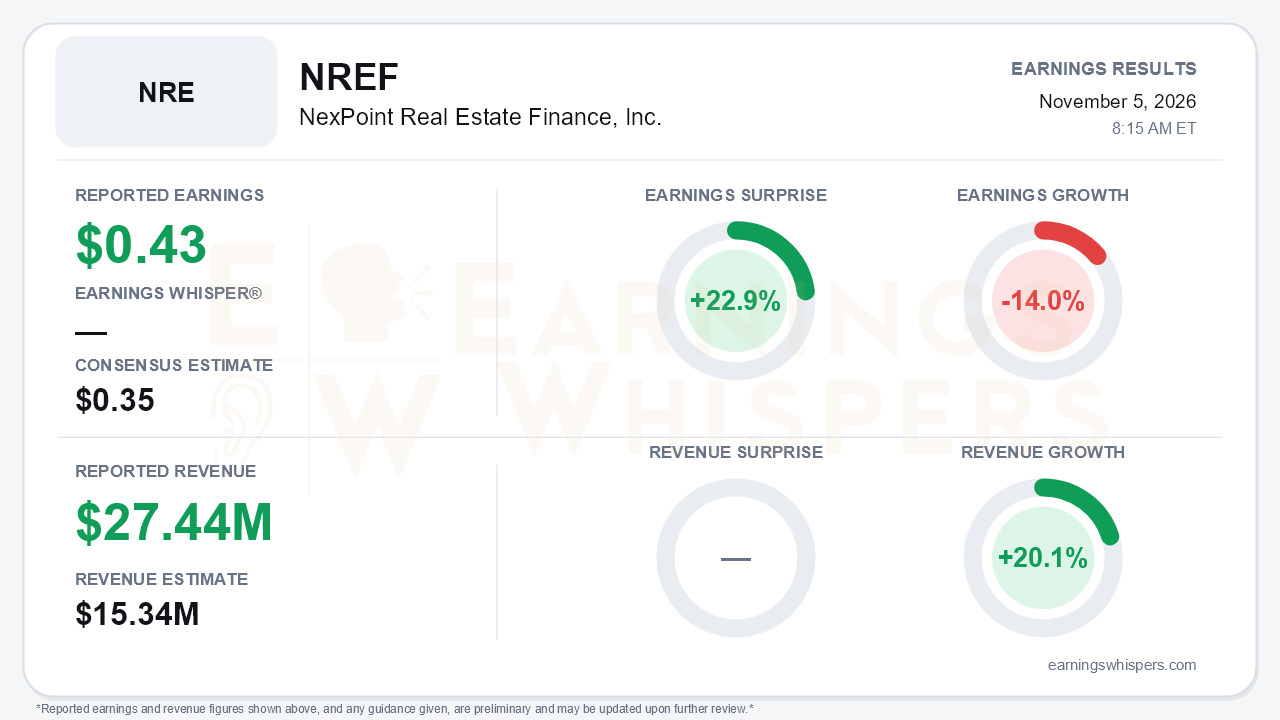
NexPoint Real Estate Finance (NYSE: NREF) cleared a low bar in the third quarter. Earnings were $0.43 per share against a $0.35 consensus, a 22.9% surprise, and revenue of $27.44 million beat the $15.34 million estimate by 78.9%. Revenue grew 20.1% year over year, but earnings fell 14.0%, so the top-line strength did not carry through to the per-share result. Beneath the beat, the balance sheet weakened. Book value per share fell 5.2% to $17.63. Leverage rose. Fourth-quarter EAD guidance moved lower, and several expected repayments slipped. That is the central tension: income metrics held up while the asset base underneath them softened.
The quality of the beat deserves scrutiny because the company's own measures diverge sharply. On a GAAP basis, NREF lost $12.2 million, or $0.65 per diluted share, compared with net income of $35.0 million a year ago and $0.29 per share in the second quarter. The swing came almost entirely from $21.9 million of unrealized losses on fair-value investments and derivatives. A year earlier, the company recorded $48.3 million of unrealized gains. The company's preferred non-GAAP measure, earnings available for distribution, was $0.52 per share, versus $0.51 a year ago. Cash available for distribution rose to $0.60 from $0.53. Both came in ahead of the $0.43 EAD and $0.55 CAD midpoints management set last quarter, and both covered the $0.50 dividend. Investors should note that the normalized $0.43 figure sits well below the company-reported EAD. Credit provisioning was minimal at $460,000, compared with $15.7 million in the year-ago quarter.
The call was more cautious than the release suggests. Management described multifamily blended lease rates as "flat to slightly positive" with concessions still common. Last quarter it had highlighted a +30 basis point inflection in July. Management also flagged Freddie multifamily delinquencies rising to 80 basis points from 48 in 2024, an agency K deal on watch, and a 10-year Treasury back above 5%. Collateral stabilization slipped to 78.3% from 82.5% at the end of 2025. Weighted-average LTV climbed to 64.7% from 59.9% in the first quarter. Debt-to-equity reached 0.97x, up from 0.7x in Q1. Meanwhile, the portfolio shrank to 83 investments and $1.0 billion. New Q3 originations totaled just $6.2 million, versus $62.8 million in the second quarter. Life sciences concentration kept rising, reaching 40.7% of the portfolio, up from 30% at year-end.
Management did offer offensive angles:
- The Mizuho facility was upsized to $450 million from $375 million.
- The weighted-average cost of debt fell to 5.8% from 6.3%.
- Series C preferred raises climbed to $27.9 million.
- $280 million of the $415 million April pipeline has closed year to date, with another $160 million committed.
- Management is developing a Freddie supplemental-capital program aimed at roughly $30 billion of stressed 2020–2023 floating-rate multifamily loans.
- Edge-compute and powered-shell interest at IQHQ and Vacaville could create a monetization path.
The risk is execution timing. Holly Springs and Vacaville were extended rather than repaid. The Alewife recapitalization, with term sheets near $400 million against a roughly $200 million first mortgage, slipped from "Q4" to "next quarter or two."
Guidance reinforces the cautious read. Fourth-quarter EAD guidance calls for $0.37 to $0.47 per share, a $0.42 midpoint that implies only 0.84x dividend coverage. CAD guidance holds at a $0.55 midpoint, or 1.10x coverage. Dividend support therefore increasingly rests on the cash measure rather than distributable earnings. Bears have legitimate ammunition here.
Investor sentiment improved meaningfully into the report but stayed negative, moving to -0.18 from -0.41. Price action has been punishing. The stock opened at $17.04 after the August report, briefly hit a 52-week high of $18.43 the next day, and has since given back all of that and more. It closed at $14.64 on November 4, down 14.1% since the prior report and 20.6% below that high. That puts shares 4.9% below the 200-day moving average and just 1.7% above the November 3 inter-earnings low. The stock trades well below even the reduced book value. The Earnings Whispers trend signals are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that NREF delivered the dividend coverage it promised, but the quarter shifted the debate toward asset quality. Falling book value, rising leverage, slipping repayments and softer Q4 EAD guidance outweigh a headline beat. A recovery case now depends on Alewife and other repayments actually arriving and on multifamily credit stabilizing as rates stay elevated.
Read our earnings preview for NexPoint Real Estate Finance, Inc.: https://www.earningswhispers.com/article/NREF/22150
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-27 | |
| Oct-06 | |
| Sep-30 | |
| Sep-16 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Jul-28 | |
| Jul-09 |
