LSI Industries Misses On EPS As Royston Masks Organic Stall; Program Wins Point To A Back-Loaded Year
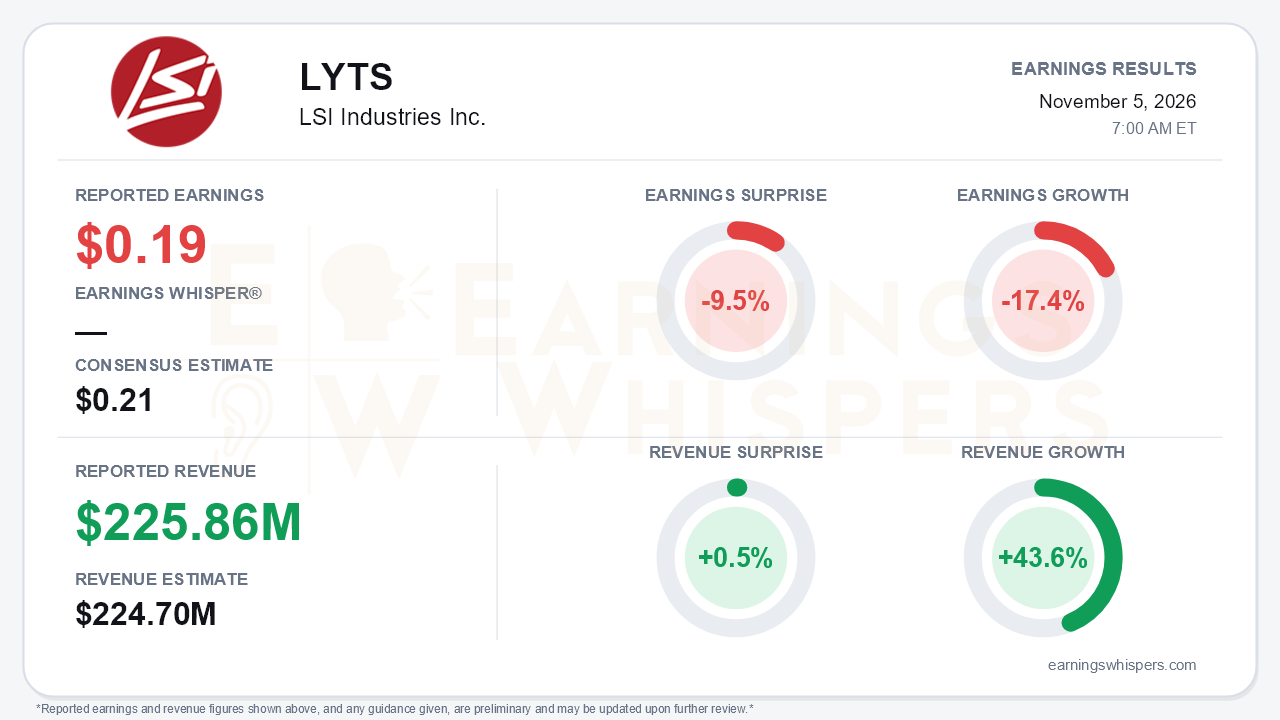
LSI Industries (NASDAQ: LYTS) reported fiscal first-quarter earnings of $0.19 per share, 9.5% below the $0.21 consensus, on revenue of $225.86 million, a 0.5% beat. Revenue grew 43.6% year over year, but earnings fell 17.4%. That gap is the central tension. The Royston acquisition, closed in March 2026, roughly doubled the Display Solutions segment and lifted total sales. Strip it out, though, and organic sales declined 2%. Higher interest expense and a larger share count then absorbed the incremental profit. This was a quarter of acquired growth layered on top of a core business that stopped growing.
The quality of the quarter deserves scrutiny on both sides of the GAAP line. On a GAAP basis, operating income rose 29% to $14.2 million. Net interest expense, however, jumped to $3.9 million from $0.7 million. Diluted shares rose to 37.9 million from 31.4 million, reflecting acquisition financing. Together these left GAAP net income slightly lower at $7.1 million. Adjusted EPS of $0.31 was flat with the prior year, so even on management's preferred basis the deal has not yet been accretive per share. Adjusted EBITDA rose 41% to $22.2 million. The adjusted EBITDA margin, however, slipped to 9.8%, down from 10.0% a year ago and 10.9% in the fiscal fourth quarter, and well short of the reaffirmed 12.5% target. The clear bright spot was cash. Free cash flow was $13.8 million against negative $0.3 million a year ago. Net debt fell $14.3 million, and leverage eased to 2.6x from 2.7x at the end of June. Management reiterated its goal of reaching 2x within 12 to 18 months.
The call made the organic deceleration hard to ignore. Comparable Display Solutions growth slowed to about 1%, from 18% in the fiscal fourth quarter and 14% in the third. QSR and banking display sales were down double digits. Lighting has now deteriorated for four straight quarters:
- Fiscal second quarter: sales up 15%.
- Fiscal third quarter: up 2%.
- Fiscal fourth quarter: down 3%.
- This quarter: down 6%.
Lighting orders rose just 1% despite quotes up 5%, and the usual seasonal fall uptick never arrived. Price actions did nudge Lighting gross margin up 10 basis points, which is a sign of discipline rather than demand. Management also flagged rising customer schedule pushouts of weeks to months, driven by budget constraints, labor shortages and job-site delays. Inflation is stretching customer capex so fewer sites get completed per budget. The tone shifted noticeably from last quarter's confident, record-year framing to an emphasis on being realistic about the near term.
The forward pipeline is where the bull case lives, and it is substantive. LSI was named one of three providers for a 3,000-store QSR interior renovation program, starting late in fiscal Q3 and running about three years. The 2,500-site refueling refresh is ramping as planned and now includes Royston signage, an early tangible cross-selling win. A second major c-store chain is in pilot deployments, and LSI won additional grocery share at the largest retailer's line review. Display orders and backlog each rose 4%, with grocery orders up 12%. Royston itself improved, with sales up 8% sequentially and adjusted EBITDA margin up 100 basis points. Management is targeting another 200 basis points at Sign Resources in Q2. Self-help adds support through the Collingwood consolidation (over $1 million in annual savings) and roughly $1 million in procurement savings. Most of these wins, however, ramp late in fiscal 2027 and into 2028. Meanwhile the holiday slowdown and project pushouts weigh on the next quarter or two. A new multi-year plan extending to 2032, due in mid-December, is the next potential sentiment event.
Investors were already leaning cautious before the report. Earnings Whispers sentiment fell sharply, from roughly neutral at -0.03 to -0.50, a decisive negative shift. Shares stood at $21.39 in the pre-report snapshot. That is 5.9% below the open following the August report and 2.9% under the 200-day moving average. The stock sits 7% below its inter-earnings high of $23.00, set on the day of the last report, and 11.9% above the September low of $19.11. Price and AVWAP trend readings remain negative, consistent with a stock that has steadily faded since the last report.
The bottom line is that LSI delivered a revenue beat and strong cash generation but missed on earnings as Royston-driven growth concealed an organic business that has flattened. Lighting is in clear decline, and margins are moving away from target. Bears have legitimate ammunition in the deceleration, the softer tone and the absence of per-share accretion. Bulls can point to a growing roster of multi-year program wins, Royston margin repair and steady deleveraging. The investment case now rests on whether those programs convert on schedule in the back half of fiscal 2027, despite customers who keep pushing projects out.
Read our earnings preview for LSI Industries Inc.: https://www.earningswhispers.com/article/LYTS/22138
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-19 | |
| Aug-24 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-06 | |
| May-27 | |
| Apr-24 | |
| Apr-23 |
