Gold Royalty Matches EPS Estimates As Record GEO Volumes Shift Focus To Capital Returns, But Shares Stay Stuck Below The 200-Day
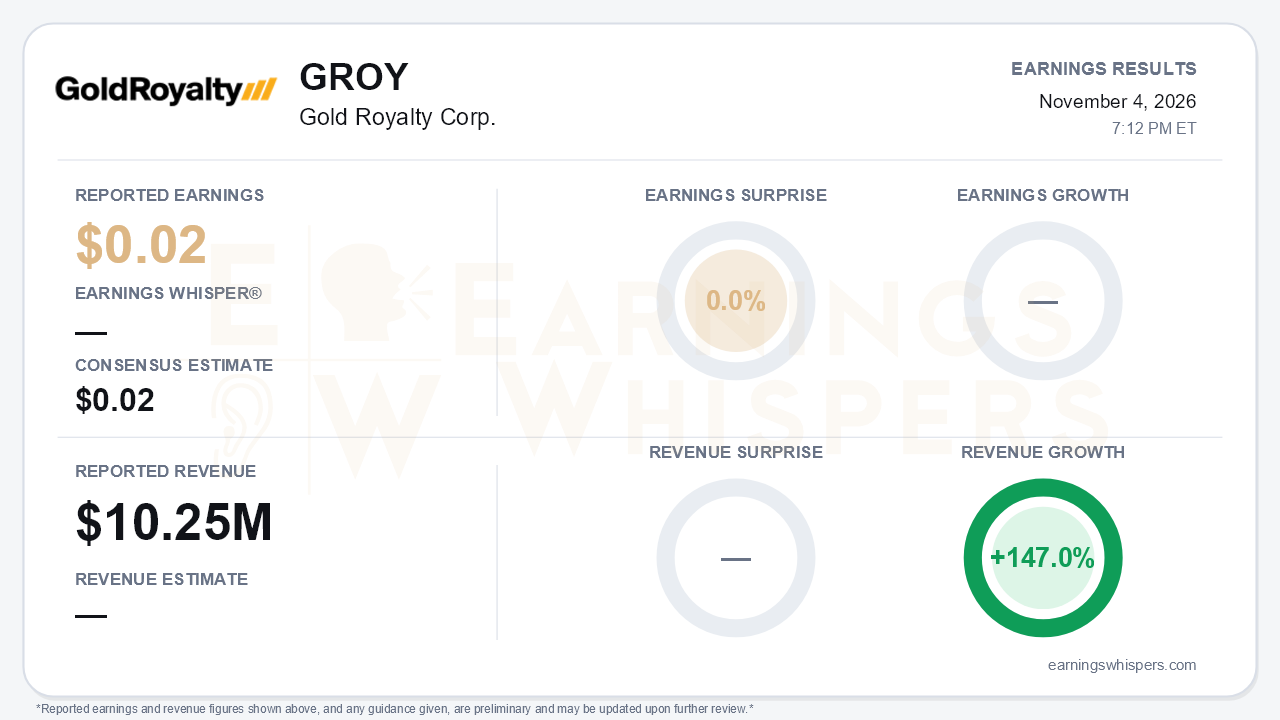
Gold Royalty Corp. (NYSE American: GROY) earned $0.02 per share in the third quarter, exactly matching the consensus estimate. The in-line print understates how much the business changed. Revenue rose 147.0% year over year to a record $10.25 million. Net income swung to $3.8 million from a $1.1 million loss a year earlier. Gold equivalent ounces (GEOs) jumped to 2,689 from 1,757 in the second quarter, a sharp re-acceleration after a soft middle quarter. The central story is no longer whether the portfolio can generate cash. It is now what management does with that cash, and whether the market will start paying for it.
The quality of the quarter is mostly good, with one caveat. Total Revenue, Land Agreement Proceeds and Interest reached $11.5 million, up from $9.4 million in Q1 and $7.9 million in Q2. Adjusted EBITDA climbed to $9.0 million from $5.6 million in Q2 and $2.5 million a year ago. Operating cash flow tripled year over year to $7.5 million.
The mix improved materially:
- Royalty revenue rose to $7.3 million from $1.6 million.
- Streaming revenue roughly doubled to $2.4 million as Vareš ramped.
- Advance minimum and pre-production royalties fell to $0.2 million from $1.1 million, a sign that development-stage payments are giving way to producing assets.
The volume gain came even though the average gold price fell to $4,266 from $4,516 in Q2, so this was not simply a commodity-price tailwind. Below the operating line, finance costs collapsed to $0.2 million from $2.3 million with the convertible debentures gone, which cleaned up the earnings line considerably.
The caveat is land agreement proceeds of $1.1 million, versus $0.2 million a year ago. Management itself flagged these as lumpy and above the normal run rate, so part of the record is non-recurring. Per-share leverage is also diluted: the weighted diluted share count rose to roughly 238 million from 171 million.
On the call, management's tone improved noticeably even though the numbers in guidance did not change. The 2026 range of 7,500–9,300 GEOs was reaffirmed rather than raised or narrowed. Year-to-date output of 6,366 GEOs represents 76% of the midpoint, and management said the year could land in the higher end. That is a step up from simply being on track at Q2. Still, reaching the very top would require a fourth quarter above Q3's record, so investors should treat the language as directional rather than a formal raise.
The copper stream at Vareš reached commercial production on August 10, ahead of target, and management expects the Q4 run rate to carry into 2027. Capital returns advanced from something to 'evaluate later this year' in Q1 to active board consideration now. That shift is supported by:
- cash nearly doubling to about $21 million from $11.3 million;
- no debt;
- an undrawn credit facility. The release describes it as $125 million plus a $25 million accordion; the call characterized it as $150 million.
Forward catalysts are dense:
- Odyssey Shaft #1 production in Q2 2027.
- REN full production in 2027.
- The Jerritt Canyon restart in the second half of 2027.
- South Railroad first gold in 2028.
- Q4 study updates at Borborema, Côté and Odyssey.
The call said REN's first production is due by year-end, while the release frames the milestone around full production in 2027.
Bears have legitimate ammunition. The Bosnian Constitutional Court's six-month review of state property acts introduces legal uncertainty over the Vareš concession, the asset driving streaming growth, although DPM says operations continue normally. Management also acknowledged:
- operator cost inflation in sulfur, diesel and labor that could squeeze partner margins in 2027;
- an acquisition market competitive enough to compress returns, which leaves the company buying only small Nevada royalties, such as the $0.8 million Sterling and Granite Creek deals.
Granite Creek has its own wrinkle. i-80 has pushed the open-pit phase behind Mineral Point, and Granite Creek and South Railroad timing were not reiterated on the call.
The market setup is more complicated than the operating momentum implies. Shares sit at $2.89, unchanged from the open following the August report despite a record quarter. They trade 14.6% below the $3.38 200-day moving average. Investor sentiment remained modestly negative and was essentially unchanged, edging to -0.18 from -0.17. Earnings Whispers trend readings are mixed: momentum is positive while price and AVWAP trends remain negative. In short, the fundamental improvement has not yet translated into buying interest.
The bottom line is that Gold Royalty delivered a genuinely stronger quarter than its in-line EPS suggests. Record volumes, a cleaner balance sheet, an improving revenue mix and a capital-return discussion now before the board all point the same way. The quarter was partly flattered by lumpy land payments, guidance was not formally raised, and the Vareš legal review adds a real asset-specific risk. With shares flat since August and well below the 200-day average, the burden is on Q4 delivery and a concrete shareholder-return announcement to change how investors value the story.
Read our earnings preview for Gold Royalty Corp.: https://www.earningswhispers.com/article/GROY/21845
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Oct-27 | |
| Oct-08 | |
| Sep-28 | |
| Aug-18 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Jul-13 | |
| Jun-15 | |
| May-06 | |
| Apr-29 | |
| Apr-27 | |
| Apr-03 |
