AMH Beats And Raises Again, But Lower Costs, Not Rents, Are Driving The Upside As New-Lease Pricing Stalls
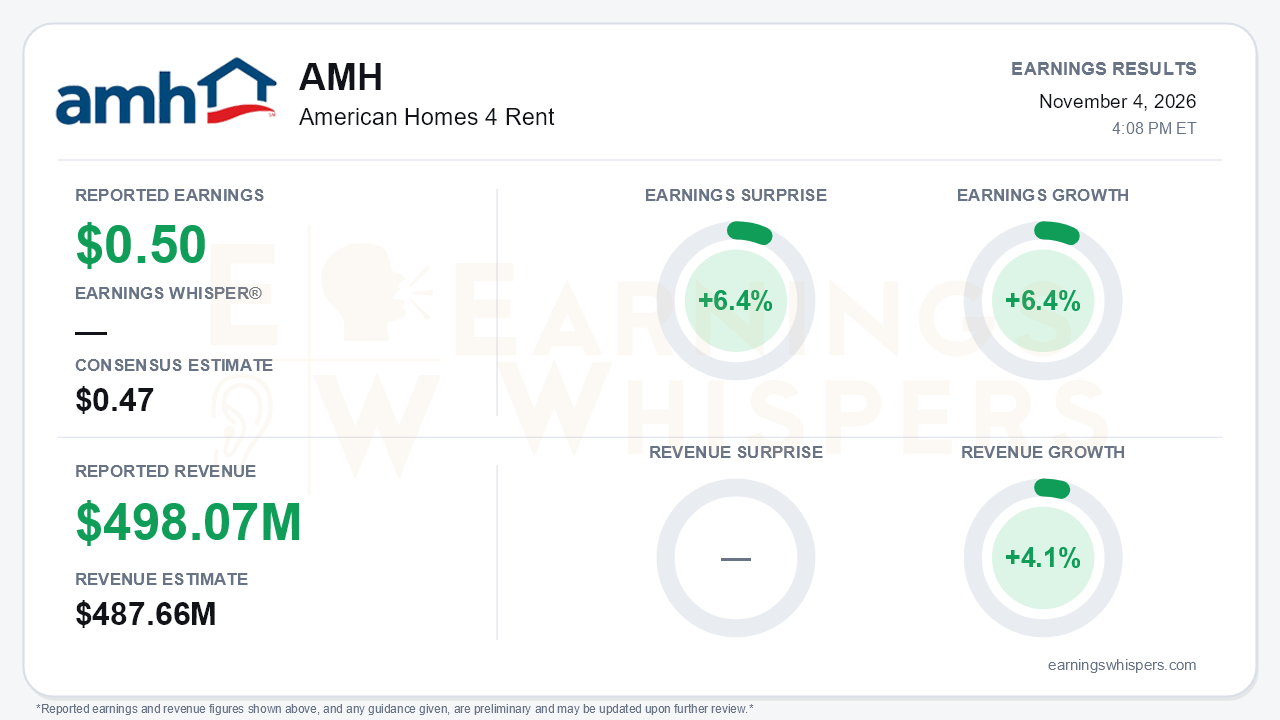
American Homes 4 Rent delivered a clean third-quarter beat and a third consecutive guidance raise, but the quality of the upside deserves scrutiny. Core FFO of $0.50 per share topped the $0.47 consensus by 6.4%, and revenue of $498.07 million beat expectations by 2.1% while growing 4.1% year over year. On Earnings Whispers' basis, earnings grew 6.4%. The company cites 7.4% Core FFO per-share growth, which reflects unrounded figures; on that basis, growth accelerated from 5.2% in the second quarter and 4.6% in the first. Management lifted the full-year Core FFO midpoint by $0.02 to $1.97, implying 5.3% growth. That is up from roughly 2.7% when the year began. The central tension is that this improving earnings trajectory is being built mostly on expense relief and execution, while the rent engine that ultimately drives the stock is losing speed.
Beneath the headline, the same-home portfolio was solid rather than strong. Same-home core revenues rose 2.3%. Average monthly realized rent increased 2.4%, partly offset by a 30-basis-point dip in occupancy to 96.0%. Same-home expenses rose 1.8% on higher repairs, maintenance and turnover costs. Same-home Core NOI grew 2.5%, slower than the 3.1% year-to-date pace. Total-portfolio Core NOI did better, rising 5.3%, because non-same-home NOI climbed to $32.4 million from $24.4 million as newly delivered development homes leased up. Per-share results also benefited from a shrinking share count. AMH repurchased another $75 million of stock at $31.39 in the quarter, bringing buybacks since late 2025 to about $463 million, or roughly 4% of shares. GAAP results told a different story. Net income per diluted share fell to $0.23 from $0.27, primarily because gains on property sales dropped to $21.5 million from $47.6 million. That decline is not an operating problem, but it is a reminder of how much non-core items swing the GAAP line.
The guidance revisions make the composition of the raise explicit. The same-home expense growth midpoint has fallen from 2.75% at the start of the year to 1.6%. Property tax growth is now in the mid-1% range rather than the roughly 3% originally planned, with Texas and Florida assessments coming in favorably, and insurance costs declined about 10%. Same-home NOI guidance has risen from 2.0% to 2.8%. Revenue guidance, by contrast, has moved only from 2.25% to 2.4%. Pricing is where bears have legitimate ammunition. New-lease spreads slid from 1.6% in July to 1.0% for the quarter and just 0.1% in October. The blended spread eased to 2.6% from 2.7%. Renewals at 3.3% are carrying the load. Management also indicated that 2027 earn-in sits in the low-1% area, below the mid-1% earn-in that supported 2026.
The call did preserve a credible forward story. Occupancy has stabilized near 96%, which removes the occupancy drag that weighed on 2026 comparisons. Development economics are improving. Initial yields are running above 5.3% on flat vertical costs, and new land is being underwritten above 6%. National builders are now selling finished lots in good locations, which shortens the development cycle. Pre-leasing of remaining 2026 deliveries exceeds 50%, up from 40% last quarter, without concessions. Management also pointed to John Burns' forecast of modestly re-accelerating market rent growth in 2027, but that is a third-party forecast rather than company guidance.
The risks are concentrated in supply and growth runway. Mortgage rates approaching 7% could push would-be sellers to rent out homes instead, adding shadow supply that management acknowledged is not yet visible. San Antonio remains weak, and Phoenix and parts of Texas are still absorbing inventory. Portfolio consolidation opportunities following housing legislation have produced no deals so far, and Treasury rulemaking is pending. Fourth-quarter wholly owned deliveries of about 100 homes will be the lowest since the program began, and disposition volume slowed to 291 homes.
Investors were not leaning in ahead of the print. Earnings Whispers sentiment slipped from modestly positive (0.08) to modestly negative (-0.11), a meaningful but not dramatic shift. At $32.63, shares are down 1.7% since the open following the July report, yet they still sit about 3.2% above the 200-day moving average. The stock has gone essentially nowhere through a quarter in which guidance rose, which suggests the market is discounting expense-driven upside. Price and AVWAP trend readings are negative, consistent with that sideways-to-softer tape.
The bottom line is that AMH executed well, beat estimates and raised guidance for the third straight quarter, but the raises are increasingly a cost story layered on top of decelerating new-lease pricing and a thinner 2027 earn-in. Buybacks, development yields and stable occupancy give the company levers to keep growing per-share results. Even so, the debate now turns on whether rent growth reaccelerates in 2027 or whether shadow supply keeps new-lease spreads near zero.
Read our earnings preview for American Homes 4 Rent: https://www.earningswhispers.com/article/AMH/21779
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-08 | |
| Oct-08 | |
| Sep-27 | |
| Sep-21 | |
| Sep-15 | |
| Sep-09 | |
| Aug-20 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-16 |
