RLJ Lodging Trust Beats As Business Travel Drives Margin Gains, But The Fourth Guidance Raise Largely Matches The Street
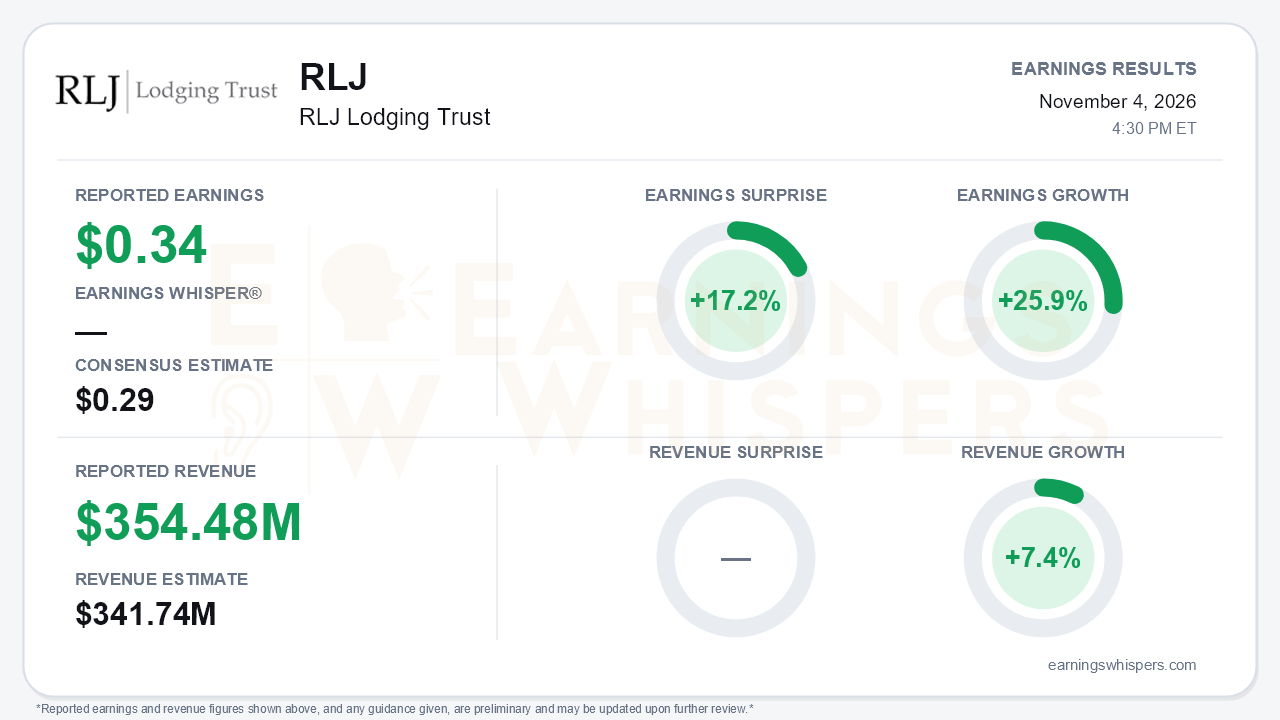
RLJ Lodging Trust delivered its strongest quarter of the cycle. Adjusted FFO of $0.34 per share beat the $0.29 consensus by 17.2% and grew 25.9% year over year. Revenue of $354.48 million topped the $341.74 million estimate by 3.7% and rose 7.4%. More important than the beat itself is the shape of the trend. Comparable RevPAR growth accelerated for a third straight quarter, from 4.8% in Q1 to 6.8% in Q2 to 9.7% in Q3, and the gap over the industry widened to 260 basis points from roughly 100-110 basis points earlier in the year. This was not a cost-cutting beat. Demand and pricing both moved: occupancy rose 230 basis points and ADR rose 6.4%.
The quality of the quarter shows up in flow-through. Comparable Hotel EBITDA rose 17.5% to $93.9 million, more than double the 7.1%-7.2% growth of the first two quarters. Hotel EBITDA margin expanded 190 basis points to 26.5%, compared with just 10 basis points in Q2. Cost per occupied room rose only about 3%, and management cited roughly 50% flow-through. Adjusted EBITDA climbed 17.3% to $85.2 million.
On a GAAP basis, the picture is less flattering. Net income swung to $4.6 million from a $3.8 million loss. After $6.3 million of preferred dividends, however, common shareholders still recorded a loss of $0.01 per share, narrowed from a $0.07 loss. That gap is typical for a lodging REIT carrying heavy depreciation, but it is a reminder that the headline strength sits in non-GAAP measures.
The call explained what changed beneath the numbers: business travel arrived in force. Business transient revenue grew 15%, up from 9% in Q1 and 10% in Q2, with business transient ADR up 13%. Compression nights rose 15%, and 20% on Monday through Wednesday. Leisure and group each grew about 10%, versus 7% and 6% in Q2. Markets outside the World Cup host cities grew about 12%, double their Q2 pace, which undercuts the argument that the quarter was an event-driven fluke. Management's tone shifted materially. Earlier in the year it spoke of being 'cautiously optimistic' with 'limited visibility.' Now it describes the 'early phases of a multi-year cycle' with 'true pricing power.' Execution on capital projects is adding to the story. Conversions lifted RevPAR 12% and EBITDA 18%, and last year's high-impact renovations grew RevPAR 26% and more than doubled EBITDA.
The guidance deserves a more measured reading than the headline 'raise' implies. Full-year RevPAR guidance moved to 5.75%-6.25%, from 3.5%-4.5% in Q2 and 0.5%-3% at the start of the year. Adjusted EBITDA guidance rose $9 million at the midpoint to $352-$358 million despite the Midway sale. The AFFO range tightened to $1.47-$1.51 from $1.37-$1.50, but it remains in line with Street estimates, so the raise largely ratifies expectations analysts had already built in. The near-term cadence also cooled. October RevPAR grew about 6%, versus roughly 11% in July, partly because the Dreamforce conference shifted into September. Non-room revenue growth decelerated for a third straight quarter, to 6.5%. Cash G&A guidance also ticked higher.
The forward catalysts are real but carry some caveats. On the positive side:
- 2027 group pace is tracking up mid-single digits.
- Q4 group pace improved 500 basis points during the quarter.
- The 2027 event calendar is crowded, including the Super Bowl in Los Angeles, the NFL Draft in DC, MLB's All-Star Game in Chicago, and pre-Olympic activity in Southern California.
- Key West and Boston conversions are slated to relaunch in 2027.
The risks bears can point to:
- Northern California RevPAR rose 13%, and EBITDA there is up 63% over two years, which ties a meaningful slice of growth to AI-driven demand. Analysts probed that exposure directly.
- The 2027 insurance and property-tax picture is undisclosed, and a favorable prior-year insurance renewal creates a tougher comparison.
- Energy costs remain elevated, though moderating.
- Management has not yet said how it will deploy roughly $500 million of cash.
The $110 million Midway sale, at 13.8x forecast 2026 Hotel EBITDA (16.1x including required capex), prunes a lower-quality cluster. It also adds cash and a $20 million seller note to that undeployed pile.
The market had partly anticipated the improvement. Shares at $12.72 are up 6.2% since the open after the August report and sit about 28% above the 200-day moving average of $9.93, so RLJ entered the print with a substantial run-up already behind it. Investor sentiment improved from slightly negative to modestly positive. That is a modest shift, not a surge in conviction. The Earnings Whispers trend readings lean positive on momentum and AVWAP, while the sequential-growth reading remains negative, consistent with a softer near-term cadence after an exceptional third quarter.
The bottom line is that RLJ produced an accelerating, high-quality quarter. Business travel and pricing power drove margin expansion that the first half lacked, and the call made a credible case for a multi-year urban upcycle. The setup is still more complicated than the 17.2% surprise suggests. Guidance only matches what the Street expects, October slowed, AI-linked Northern California demand is a concentration risk, and the stock already trades well above its long-term trend. Upside from here likely depends on 2027 visibility and capital deployment rather than on the strength of this quarter alone.
Read our earnings preview for RLJ Lodging Trust: https://www.earningswhispers.com/article/RLJ/21925
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-25 | |
| Oct-19 | |
| Sep-15 | |
| Sep-14 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jun-15 | |
| Jun-11 | |
| May-04 |
