MDU Resources Misses Q3 EPS Estimates As Bakken East FID Shifts Focus To Financing
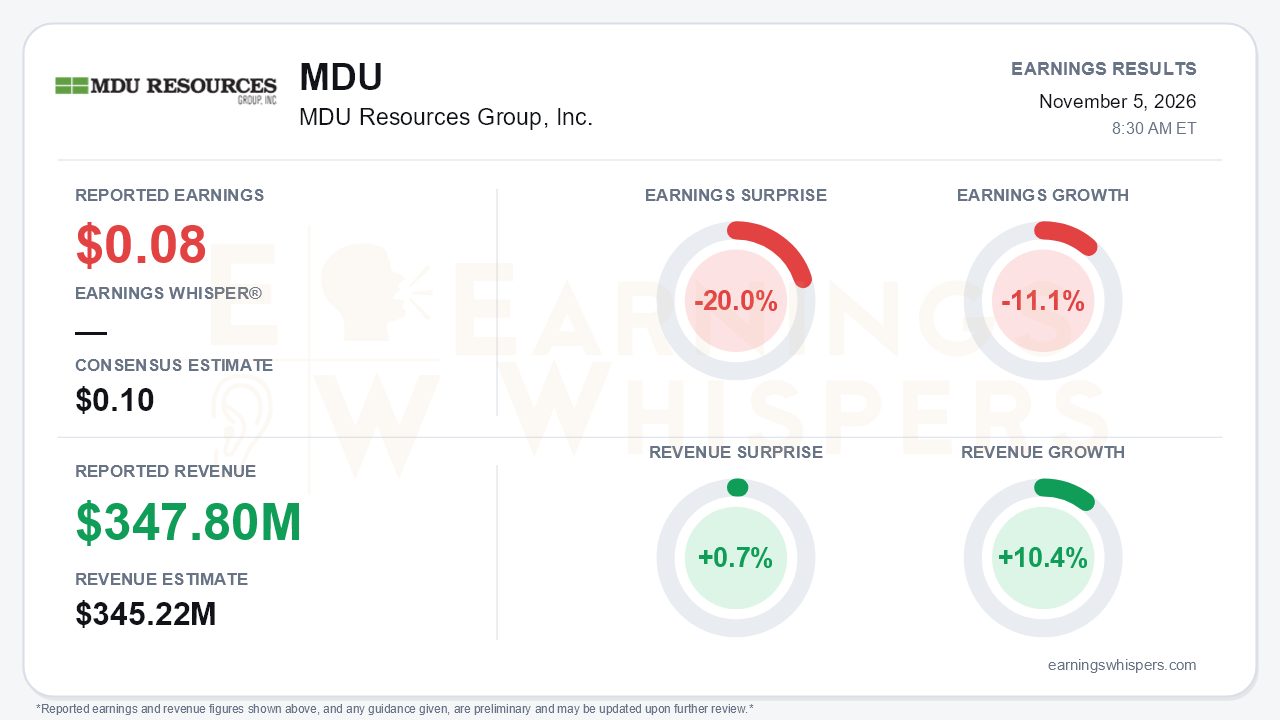
MDU Resources delivered a soft third-quarter print that was overshadowed, strategically at least, by the biggest decision in its post-separation history. Adjusted earnings of $0.08 per share missed the $0.10 consensus by 20.0% and fell 11.1% from a year ago. GAAP EPS was $0.07. Revenue rose 10.4% to $347.8 million, edging past the $345.22 million consensus by 0.7%. Management reaffirmed 2026 EPS guidance of $0.93 to $1.00 for the third consecutive call. The central tension is clear. The core utility engine is running better than the EPS line suggests, but the board has now committed to a $2.8 billion to $3.1 billion pipeline whose funding plan remains undisclosed.
The quality of the miss deserves scrutiny, because it did not originate in operations. Consolidated operating income climbed to $47.6 million from $39.8 million, and year-to-date operating income is up 15% to $211.2 million. The damage came below the operating line:
- Interest expense jumped to $32.6 million from $26.4 million.
- Other income collapsed to $1.4 million from $7.3 million, largely on weaker returns from nonqualified benefit plan investments.
- Diluted shares rose to 212.7 million from 205.3 million.
- The Other segment's loss widened to $4.9 million from $1.7 million on higher captive-insurance claims and tax-rate adjustments.
Non-GAAP adjustments covered only $2.6 million: a $2.1 million after-tax write-off of the Knott Landfill RNG project and $0.5 million of Bakken East advisory costs. Even adjusted, earnings went backward. A financing-heavy cost structure is eroding operating gains, and that pressure will intensify as the capital plan grows.
By segment, electric was the standout. Earnings rose 23.6% to $26.5 million on $7.1 million of new rate revenue, a $3.2 million contribution from Badger Wind, and a 9.3% increase in retail volumes. Data center sales climbed 18.4%, and online data center load rose to roughly 280MW from about 240MW in the second quarter, against more than 1GW of signed agreements. Some of the volume lift, however, was attributed to warmer weather. Natural gas distribution's seasonal loss widened to $20.7 million from $18.2 million, as higher O&M, payroll and interest costs swamped new rates and 7.1% volume growth. Pipeline is the more troubling trend. Earnings fell to $13.1 million from $16.8 million, the third straight year-over-year decline, and the gap has widened each quarter: down $1.9 million in Q1, $1.0 million in Q2 and now $3.7 million. The drivers were higher O&M, expensed Bakken East advisory costs, and storage injections of 4.7 MMdk versus 13.6 MMdk a year ago.
The forward story rests on Bakken East and regulation. The project's capital range was tightened with a slightly lower midpoint. The design is finalized, the FERC 7(c) filing is slated for the fourth quarter, and in-service targets of late 2029 and late 2030 are unchanged. Commercial momentum was steady, moving from about 40% of the 1.4 Bcf/d capacity signed in Q1 to roughly 1.2 Bcf/d in Q2 before FID. The regulatory calendar should also help near-term earnings:
- North Dakota electric interim rates of $26.3 million took effect September 1.
- An Oregon gas increase of $12.2 million took effect October 31.
- A Minnesota gas case was filed.
- A $31 million FERC pipeline rate request becomes effective December 1, subject to refund.
Bears still have legitimate ammunition. The project is roughly equal in size to the entire base capital plan. Management said financing, which could include outside equity or partners, will not be detailed until February, and it offered no 2027 framing within its 6% to 8% growth target. Nine-month operating cash flow also slipped to $347.6 million from $392.8 million, while total debt rose to $2.6 billion. The reaffirmed full-year range implies a fourth quarter of roughly $0.38 to $0.45 on a GAAP basis.
Investors were already leaning cautious. Earnings Whispers sentiment slid from essentially neutral (-0.02) to modestly negative (-0.18), a meaningful deterioration that likely reflects dilution and financing anxiety. Shares stood at $19.82 before the report, down 1.7% from the open following the August release and 3.7% below the 200-day moving average of $20.58. The stock marked a 52-week low of $18.24 on October 1, around the time of the FID, then recovered 8.7% into earnings. Even so, it remained 5.7% below the quarter's high, which was set the day after the prior report.
The bottom line is that MDU's quarter was weaker on the earnings line than in its operations. Electric growth, data center load and rate relief are genuine positives, and Bakken East is now a funded-in-principle growth platform rather than a concept. Until management explains how it will pay for the project and what that means for per-share growth, rising interest costs, share dilution and a slipping pipeline segment will keep the burden of proof on the company.
Read our earnings preview for MDU Resources Group, Inc.: https://www.earningswhispers.com/article/MDU/22142
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-15 | |
| Sep-30 | |
| Sep-16 | |
| Sep-10 | |
| Aug-13 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-16 | |
| Jun-22 | |
| May-13 |
