American States Water Misses As Pension Swing Flattens EPS; Rate Growth Holds But Q2 Tailwinds Fade
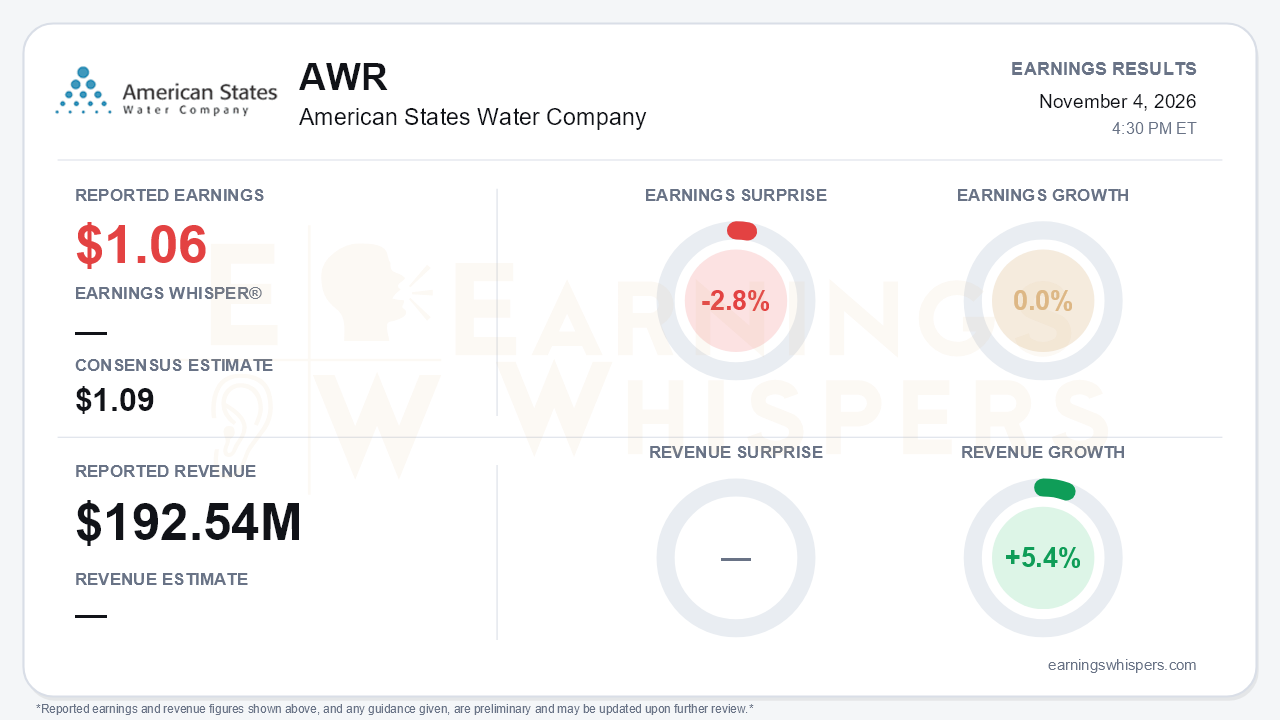
American States Water (NYSE: AWR) reported third-quarter earnings of $1.06 per share, unchanged from a year ago and 2.8% below the $1.09 consensus estimate. Revenue rose 5.4% to $192.54 million. The flat headline follows reported EPS growth of 8.6% in the first quarter and 25% in the second, so the trajectory has clearly slowed. Management's preferred explanation is a $0.05 per-share swing in retirement-plan investment results, from a $2.5 million gain last year to a small loss this year. Excluding that swing, adjusted EPS rose to $1.06 from $1.01. That is the central tension. The regulated earnings engine is still compounding on CPUC-approved rate increases, but several helpful items from the first half have faded or reversed: strong consumption, favorable supply mix, pension gains, and contracted-services growth.
The quality of the adjusted figure deserves some scrutiny. AWR began excluding these retirement-plan investment gains and losses from adjusted EPS only this quarter. Its stated reasons are that the trust has grown and the swings are becoming more consistently material. The rationale is reasonable, but the timing matters. Those same gains helped reported results earlier in 2026, when the company did not present an adjusted figure. Beneath the adjustment, the water segment earned $0.85 per share, or $0.81 to $0.85 on an adjusted basis. That segment was lifted by second-year rate increases and advice-letter capital recovery, but it also absorbed several drags:
- $1.3 million in higher net interest expense
- higher flowed-through income taxes
- roughly $0.02 of dilution from the now-completed ATM program
Consolidated income tax expense rose to $14.8 million from $12.9 million. Other income fell to $0.8 million from $3.0 million.
The call made the deceleration plain. Year-over-year revenue growth slowed to about $9.9 million, down from $18.2 million in the second quarter and $21.2 million in the first. Water consumption, which was up about 4% in the second quarter, is now up only about 1% year to date. Because the company operates under a modified decoupling mechanism and an incremental supply-cost balancing account, those swings now flow directly into earnings. Management repeatedly cautioned that favorable consumption and supply mix may reverse. The tone was noticeably more measured than the 'excellent quarter' framing used last quarter. Operating cash flow was described only as 'largely consistent' with last year, after year-over-year gains earlier in 2026. The top of the 2026 regulated capex range was also trimmed to $220 million from $225 million.
Contracted services (ASUS) was the most notable segment development. Its EPS fell to $0.17 from $0.19 on higher operating and construction costs, the first year-over-year decline after gains in the first two quarters. Management nonetheless reaffirmed its 2026 ASUS range of $0.63 to $0.67. It also introduced initial 2027 guidance of $0.67 to $0.71, backed by $31 million in new capital-upgrade awards so far this year, already above the $29.4 million awarded in all of 2025. The 2027 outlook suggests management views the third-quarter cost pressure as timing rather than trend.
The forward catalyst calendar is substantive:
- **Bear Valley Electric rate case:** A decision is expected in the first quarter of 2027, with an 11.3% requested ROE. New rates would be retroactive to January 1. Bear Valley's rate base has grown at a 19.1% compound annual rate since 2021.
- **Water rate case:** Filed in July, it seeks roughly $1 billion of 2028-2030 capex and reinstatement of full decoupling and full supply-cost balancing. Approval would materially reduce the volatility that clouded this quarter, but a decision is not expected until late 2027.
- **Norwalk acquisition:** A proposed decision on the small acquisition is due this quarter.
Balance-sheet support also improved. The $200 million ATM is finished, parent interest costs are falling, and management plans no new equity through at least 2029. S&P affirmed AWR's A rating and Golden State Water's A+ rating. The 8.2% dividend increase extends the company's streak of annual raises to 72 years.
Investor sentiment remains negative but improved modestly, rising from -0.43 to -0.37 since the prior report. Expectations were subdued rather than euphoric heading into the print. Shares have gained 2.6% since the open after the August report, to $88.61. They sit about 10.4% above the 200-day moving average of $80.24, so the stock entered this miss from a position of relative technical strength. Momentum and AVWAP trend readings are positive, consistent with steady accumulation over the quarter.
The bottom line is that AWR's quarter was steady at its core but decelerating at the margins. Rate-base growth, a cleaner equity outlook, and fresh 2027 ASUS guidance preserve a credible long-term compounding story. However, the flat GAAP result, a newly introduced adjustment that flatters the comparison, fading consumption gains, and the first ASUS decline give bears legitimate ammunition. With shares well above their 200-day average, the near-term setup depends more on the upcoming electric rate decision and on whether the cost and consumption pressures prove temporary.
Read our earnings preview for American States Water Company: https://www.earningswhispers.com/article/AWR/21791
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-27 | |
| Oct-14 | |
| Aug-17 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-29 | |
| Jul-21 | |
| Jul-20 | |
| Jul-09 | |
| Jun-22 |
