Ecovyst Beats And Raises Again, But Slowing EBITDA Growth And A Turnaround-Aided Guide Leave A Battered Stock With Something To Prove
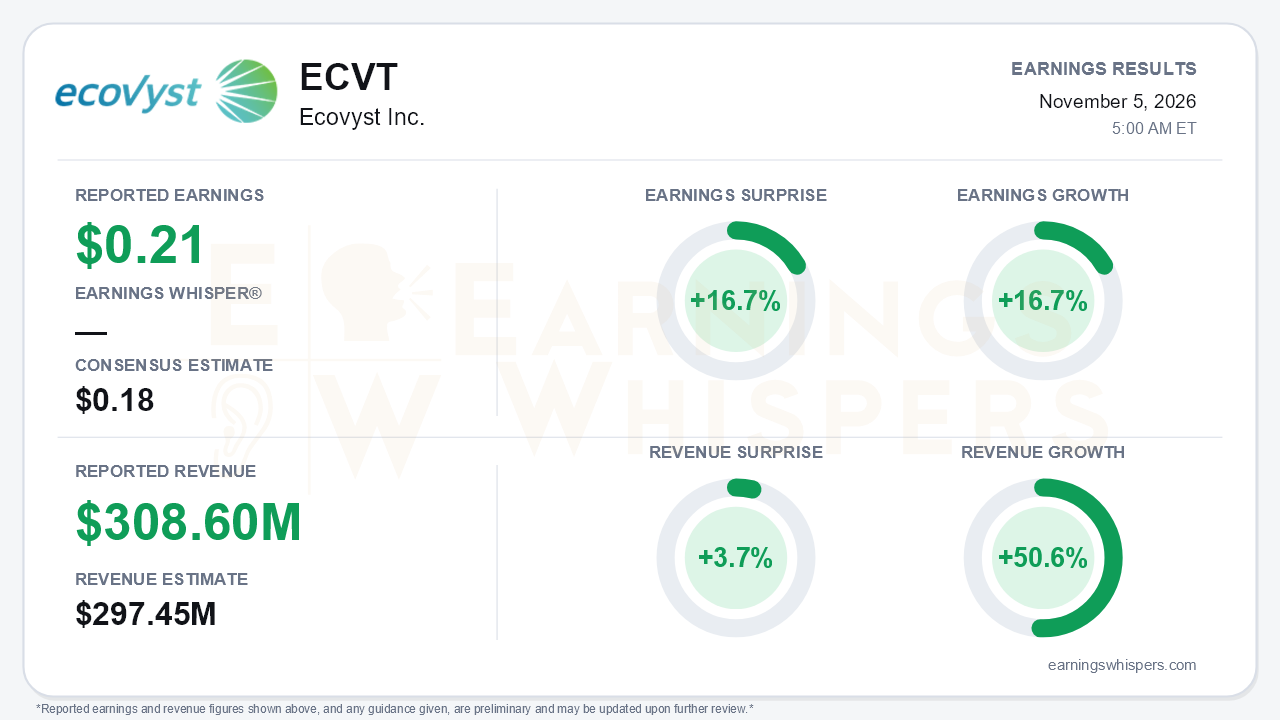
Ecovyst (NYSE: ECVT) cleared the bar comfortably in the third quarter. Earnings Whispers normalized EPS came in at $0.21, 16.7% above the $0.18 consensus and up 16.7% from a year ago. Revenue of $308.6 million beat the $297.45 million estimate by 3.7% and rose 50.6%. For reference, the company's own Adjusted Diluted EPS was $0.23, and GAAP diluted EPS from continuing operations was $0.17, so readers will see different per-share figures depending on the source. Management also raised full-year adjusted EBITDA guidance for the third consecutive call, to $208-$212 million. That is the headline. The central tension is that the beat-and-raise cadence is masking a sharp deceleration in underlying profit growth, and it arrives as the stock is trading near the bottom of its post-summer range.
The quality of the top-line beat deserves scrutiny. Roughly $67 million of the $103.7 million sales increase came from passing through higher sulfur costs. That cost recovery inflates revenue without adding commensurate profit. Calabrian, acquired June 30, contributed the first full quarter of volume. As a result, gross profit grew only 12.7%, and adjusted EBITDA rose just 6.4% to $61.2 million. Adjusted EBITDA margin compressed to 19.8% from 28.1%. Management said about 550 basis points of that compression is pass-through dilution, but higher manufacturing, transportation and labor costs also offset part of the $15 million volume and $5 million net price benefit. The GAAP swing to $18.4 million in net income from $0.2 million mostly reflects a distorted 99% tax rate in the year-ago period, not a step change in operations.
The trajectory matters more than the beat itself. Year-over-year adjusted EBITDA growth has slowed from 87% in the first quarter to 27% in the second and about 6% now as comparisons toughen. The guidance raise is also less clean than it looks. Of the 4.5% midpoint increase, about $3 million comes from pushing a fourth-quarter plant turnaround into early 2027. Management put the raise at roughly 3% excluding that shift. The implied fourth-quarter EBITDA of $54-$58 million is still above what the second-quarter call implied, but some of that strength is borrowed from next year. The 2027 calendar now carries six sulfuric acid plant turnarounds and slightly heavier customer maintenance.
The call preserved a credible demand story. Strong refining margins are keeping utilization high, gasoline exports are up 5%, and alkylate demand is supporting regenerated acid volumes. Management sounded upbeat on copper mining demand for virgin acid and on Canadian gold demand for Calabrian's sulfur dioxide. It expects positive pricing on 2027 virgin acid contract renewals and said Calabrian integration is on track, and in some areas ahead of plan. Bears have legitimate ammunition, however:
- Refiners deferring maintenance raises the risk of unplanned customer outages.
- The Tampa sulfur index fell $90 to $615 per ton, which could trigger year-end destocking.
- Fourth-quarter virgin acid volume is guided lower year over year.
The balance sheet is also tighter. Cash fell to $71.2 million from $197.2 million at year-end after the Calabrian deal, and net leverage rose to 2.1x from 1.2x. Liquidity slipped to $167 million. Year-to-date adjusted free cash flow of $32.4 million trails last year's $42.4 million. Hitting the raised $50-$60 million full-year target therefore depends on a strong fourth quarter, even as capex guidance moved up to $90-$95 million. New CFO Laurie Bergman's emphasis on cash generation will be tested quickly. The plan to repurchase up to $20 million in the second half, after only $2.7 million in the third quarter, puts most of the buyback in the fourth quarter as well.
The market setup is more complicated than the surprise implies. Shares closed at $9.97 the day before the report, down 18.5% from the $12.23 open after the August release. That leaves the stock about 15.5% below its $11.80 200-day moving average and only 4.3% above the October 1 inter-earnings low of $9.56. Investor sentiment swung sharply from roughly neutral to deeply negative over the quarter; the current reading even registers below the scale's nominal floor. Earnings Whispers trend signals are mostly negative on price and AVWAP, with momentum the lone positive reading. Expectations were clearly low going in, which gives a beat-and-raise room to be received better than the deceleration alone would suggest.
The bottom line is that Ecovyst delivered the beat and the raise investors have come to expect, and its end markets look healthy. However, the raise is partly a timing shift, EBITDA growth has slowed to mid-single digits, and pass-through revenue is flattering the top line. With sentiment washed out and shares near their quarterly low, the near-term debate will hinge on fourth-quarter cash conversion and whether 2027 pricing gains can outrun a heavier turnaround schedule and sulfur-driven volatility.
Read our earnings preview for Ecovyst Inc.: https://www.earningswhispers.com/article/ECVT/22087
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Aug-24 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-15 | |
| Jun-30 | |
| Jun-29 | |
| May-14 | |
| May-11 | |
| May-05 | |
| May-01 |
