Bentley Systems Delivers A Second Straight ARR Acceleration And A Guidance Raise, But A 44% Pre-Report Rally Raises The Bar
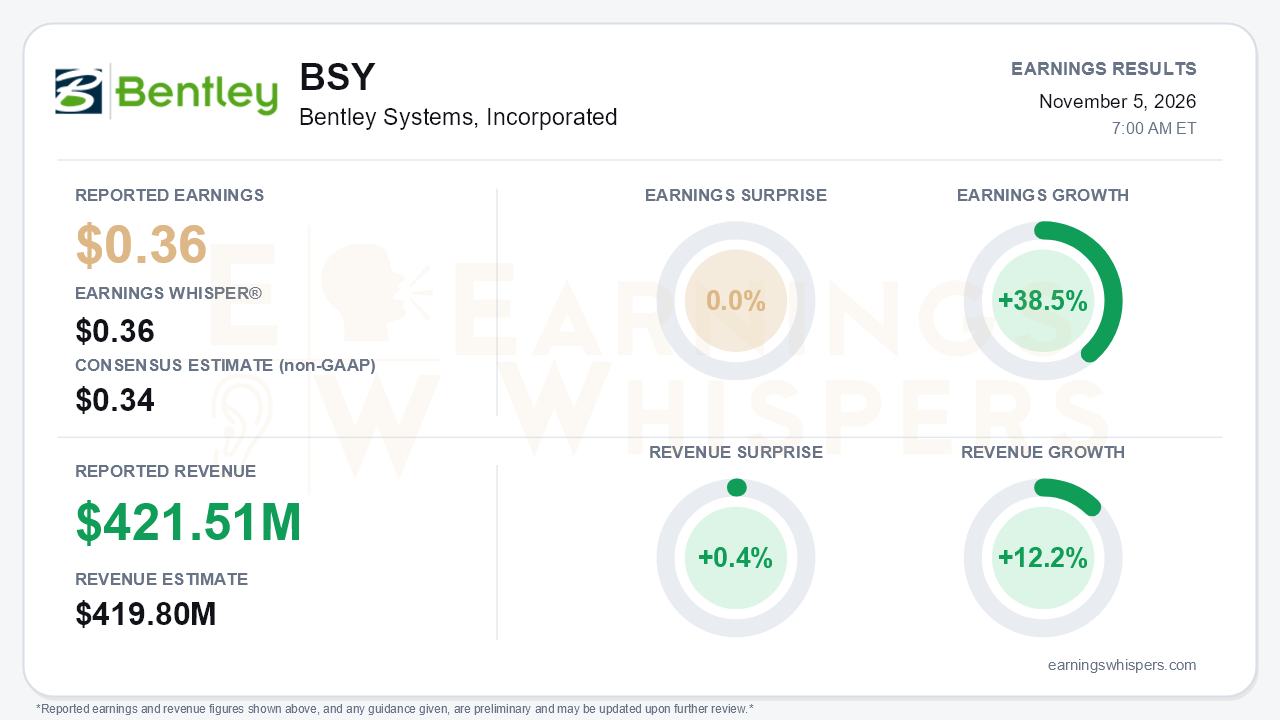
Bentley Systems (NASDAQ: BSY) reported third-quarter adjusted EPS of $0.36. That was two cents above the $0.34 consensus and exactly matched the Earnings Whisper number, so the result was effectively in line with what investors were really expecting. Revenue of $421.51 million edged past the $419.8 million consensus by 0.4% and grew 12.2% year over year. Earnings grew 38.5%. The headline beat was modest. The more important development came beneath it: annualized recurring revenue growth accelerated for a second consecutive quarter, and management raised its like-for-like ARR outlook above the top of its original range. That is the fundamental story. The complication is that the stock had already priced in a great deal of it.
The quality of the earnings growth deserves some scrutiny. Revenue rose about 12%, while adjusted EPS rose nearly 40%. Part of that gap came from real operating leverage. AOI less Operating SBC margin expanded to 32.1% from 28.1%, and GAAP operating margin jumped to 29.1% from 22.5%. Cost of subscriptions and licenses actually declined even as subscription revenue grew 12.4%. However, a meaningful share of the EPS lift came from the denominator. Diluted shares fell to roughly 317.7 million from 333.3 million, reflecting convertible note repayments and $168 million of year-to-date buybacks. A small swing in deferred compensation expense also helped GAAP margins. Two other details cut the other way. Net interest expense more than tripled after the convertible refinancing. Free cash flow of $101.4 million declined from $110.7 million, leaving year-to-date free cash flow down 8%, although the full-year $500-570 million guide was reaffirmed.
The call made a stronger case than the income statement. Constant-currency ARR growth has stepped from 11.5% in the first quarter to 12% in the second and 13% now. Sequential organic ARR growth was 3.1%, versus 2.2% a year ago. Net revenue retention reached a record 110%. Management credited asset analytics for roughly half of the sequential improvement, citing enterprise expansions with telecom tower OEMs and state DOT road-monitoring programs. APAC, led by India, became the fastest-growing region, and the Americas accelerated. Management's tone also shifted noticeably. Earlier in the year it described results as "in line with expectations"; this quarter it called them "ahead of expectations." The FY26 ARR outlook, excluding Cohesive, rose to 12.5-13.5% from 10.5-12.5%. About 100 basis points of that increase comes from the Eliis acquisition, and the rest reflects organic outperformance. Subscription revenue growth is now tracking toward the high end of the 11-13% range. G&A growth also moderated to 14% from 27% in the first half, which supports the margin trajectory.
The portfolio reshaping adds both catalysts and noise. Bentley contributed its Cohesive consulting business to Naviam in exchange for equity and warrants, and Naviam is expected to distribute Bentley's cloud and iTwin offerings across its IBM Maximo base. The cost is a lower total revenue guide of $1,673-1,703 million, down from $1,685-1,715 million, because Cohesive contributed roughly $12 million of fourth-quarter revenue. Reported ARR will also run about 100 basis points below like-for-like growth. Services, once guided to grow 15-20%, are now roughly flat and expected to decline through 2027. On the opportunity side, management committed to begin monetizing AI-in-design in 2027, though it does not expect the contribution to be material that year. Potential U.S. permitting and water legislation and new German rail tenders offer additional upside. Bears still have legitimate ammunition:
- The IIJA expired in September.
- Data-center projects could face scrutiny.
- European consumption is moderating as consultancies shift work to India.
- China remains weak.
- FX headwinds are building, at roughly $8 million year to date plus about $5 million in the fourth quarter.
- Reaching the high end of guidance requires lumpy asset analytics deals against a tough prior-year comparison.
- AI-driven pricing shifts could eventually pressure the per-user E365 model.
The market setup is more complicated than the fundamentals imply. Shares closed at $43.64 heading into the report, up 28.3% from the open after the August release. That put them within 1% of the inter-earnings high of $43.94, set the day before earnings, and nearly 27% above the 200-day moving average. The stock has also rallied almost 44% from its September 28 low of $30.36, so a substantial re-rating occurred before these numbers were known. Investor sentiment moved the other way, slipping from -0.15 to -0.23. It remained negative and weakened modestly, suggesting skepticism did not fade as the price climbed. The Earnings Whispers trend signals are uniformly positive, consistent with the strong price and sequential-growth backdrop.
The bottom line is that Bentley delivered the kind of quarter that matters most for a subscription software company: accelerating ARR, record retention, expanding margins, and a raised recurring-revenue outlook. Those gains offset a lower revenue guide driven by the divestiture and softer cash flow. The headline beat merely met the whisper, however, and the stock entered the report near its highs after a steep run. The next leg likely depends on whether fourth-quarter renewals and asset analytics deals sustain 13% ARR growth rather than on this quarter's numbers.
Read our earnings preview for Bentley Systems, Incorporated: https://www.earningswhispers.com/article/BSY/22058
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-02 | |
| Oct-28 | |
| Oct-23 | |
| Oct-22 | |
| Oct-15 | |
| Oct-07 | |
| Oct-05 | |
| Sep-30 | |
| Sep-28 | |
| Sep-24 | |
| Sep-21 | |
| Sep-18 |
