CoreCivic Beats And Raises Again, But Its Post-Sale Earnings Run Rate Is Lower Than The Headline Suggests
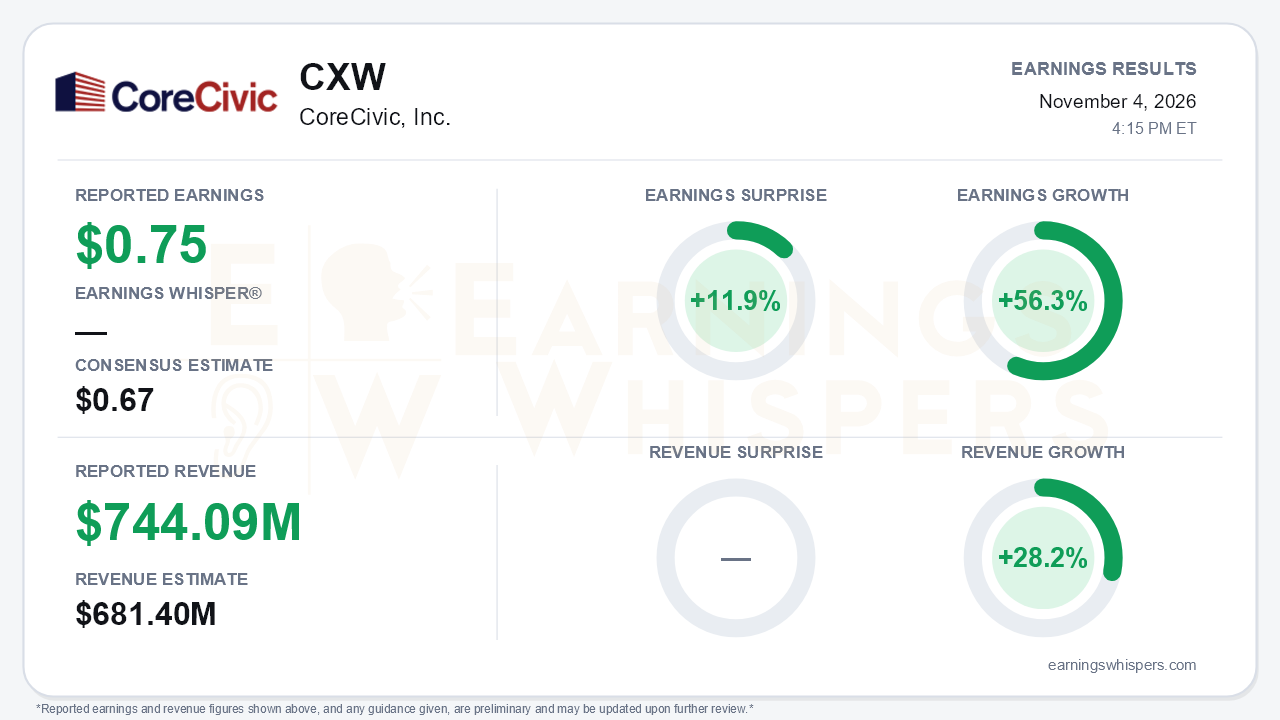
CoreCivic delivered a clear operating beat in the third quarter, but the more important story is how the company reshaped itself around that beat. Normalized FFO of $0.75 per share topped the $0.67 consensus by 11.9% and rose 56.3% year over year. Revenue of $744.09 million beat expectations by 9.2% and grew 28.2%. That year-over-year pace was well ahead of the company's first-half trend, so growth accelerated. GAAP diluted EPS of $14.49 is not a useful comparison, because it reflects a $1.77 billion net gain on the sale of four detention facilities to the Department of Homeland Security for $2.2 billion. The central tension is that the asset sales improved per-share results and the balance sheet, yet they also reduce the run rate the remaining business will carry into 2027.
The quality of the beat deserves scrutiny, though most of it is real. Adjusted EBITDA rose 32.6% to $117.8 million, up from $109.4 million in the second quarter and $110.1 million in the first. Two operating forces drove the gain:
- **Occupancy.** Residential occupancy climbed to 84.0% from 76.7% a year earlier, and federal revenue rose 22.2%.
- **The pharmacy acquisition.** Clinical Solutions Pharmacy lifted Services segment net operating income to $9.6 million from $1.1 million. Because that business was acquired, this part of the growth is inorganic.
The per-share figures also got a large financial assist. Weighted diluted shares fell 13.8%, mostly because of the $500 million accelerated share repurchase, and net interest expense dropped to $7.0 million from $16.6 million. Margins did not expand. Residential operating margin was essentially flat at 22.3% because the four facilities still ramping up are not yet producing fully activated margins.
The call added a less flattering detail. Part of the third-quarter strength came from per diem reductions at the four sold facilities that have not yet taken effect. Management expects those contract modifications, and the fourth-quarter outlook reflects them. Applying that outlook, the CFO's implied EBITDA run rate is roughly $426 million. That is below the roughly $450 million run rate cited in the second quarter, with 2027 framed at roughly $436 million to $450 million once Prairie is included. Fourth-quarter G&A will also stay elevated because of the leadership change and technology spending.
The operating trends themselves remain strong:
- Average daily population rose by 3,302 sequentially to 60,352.
- ICE populations in CoreCivic's care reached 18,283, up from 16,197 at the end of June.
- The ramping facilities were 72.7% occupied, up from 55%.
- Management said ICE has pulled back from warehouse-style alternative detention.
Guidance rose again. Adjusted EPS guidance is now $1.74 to $1.80, up from $1.64 to $1.73, after starting the year at $1.49 to $1.59. Normalized FFO guidance moved up to $2.78 to $2.85 per share, and adjusted EBITDA guidance to $442.5 million to $445.5 million. GAAP net income guidance moved lower, but that reflects accounting for the sale rather than operating weakness.
The forward-looking ledger has substantial items on both sides.
**Catalysts:**
- The 1,600-bed Appleton (Prairie) facility begins intake in the fourth quarter and should reach full activation in the second quarter of 2027. At full activation it is expected to generate about $75 million of annual revenue and roughly $10 million of EBITDA.
- More than $700 million of debt repayment should save over $40 million a year in interest. Net leverage is now negative at (0.1)x.
- With a fresh $500 million authorization, $755.8 million of buyback capacity is available.
- Preliminary talks with ICE about buying more facilities continue, though there is no assurance any sale will happen.
**Risks:**
- CEO Patrick Swindle stepped down for health reasons, and Lucibeth Mayberry has taken over. She says the strategy is unchanged.
- The company no longer owns several of its key ICE facilities. All ICE contracts can be terminated for convenience, and the California City and Midwest contracts expire in August 2027.
- Management flagged post-midterm policy uncertainty around ICE enforcement.
- U.S. Marshals revenue continues to decline.
- A $29.5 million pharmacy earn-out and related capital spending are coming in 2027.
Investors appear to be weighing those risks heavily. Earnings Whispers sentiment fell from a solidly positive 0.43 to a slightly negative -0.08 ahead of the report, a meaningful deterioration. The shares are still up 5.9% since the open after the August report, and at $30.52 they sit about 18% above the 200-day moving average. However, they trade below the $32.27 reference price used for the accelerated buyback. The Earnings Whispers trend readings are mixed: sequential growth is positive while AVWAP is negative.
The bottom line is that CoreCivic posted a genuine beat-and-raise driven by rising ICE occupancy, and it converted asset sales into a net-cash balance sheet and a shrinking share count. Investors should still separate the financial engineering from the underlying earnings power. Pending per diem cuts lower the forward EBITDA run rate below what management previously signaled. A new CEO, contracts on facilities the company no longer owns, and policy risk explain why investor enthusiasm cooled even as the numbers improved.
Read our earnings preview for CoreCivic, Inc.: https://www.earningswhispers.com/article/CXW/21818
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Oct-27 | |
| Oct-06 | |
| Oct-05 | |
| Sep-29 | |
| Sep-25 | |
| Sep-25 | |
| Aug-10 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-20 |
