Global Water Resources Misses As Depreciation Swamps Revenue Growth; Santa Cruz Rate Win Arrives Just As Connection Growth Cools
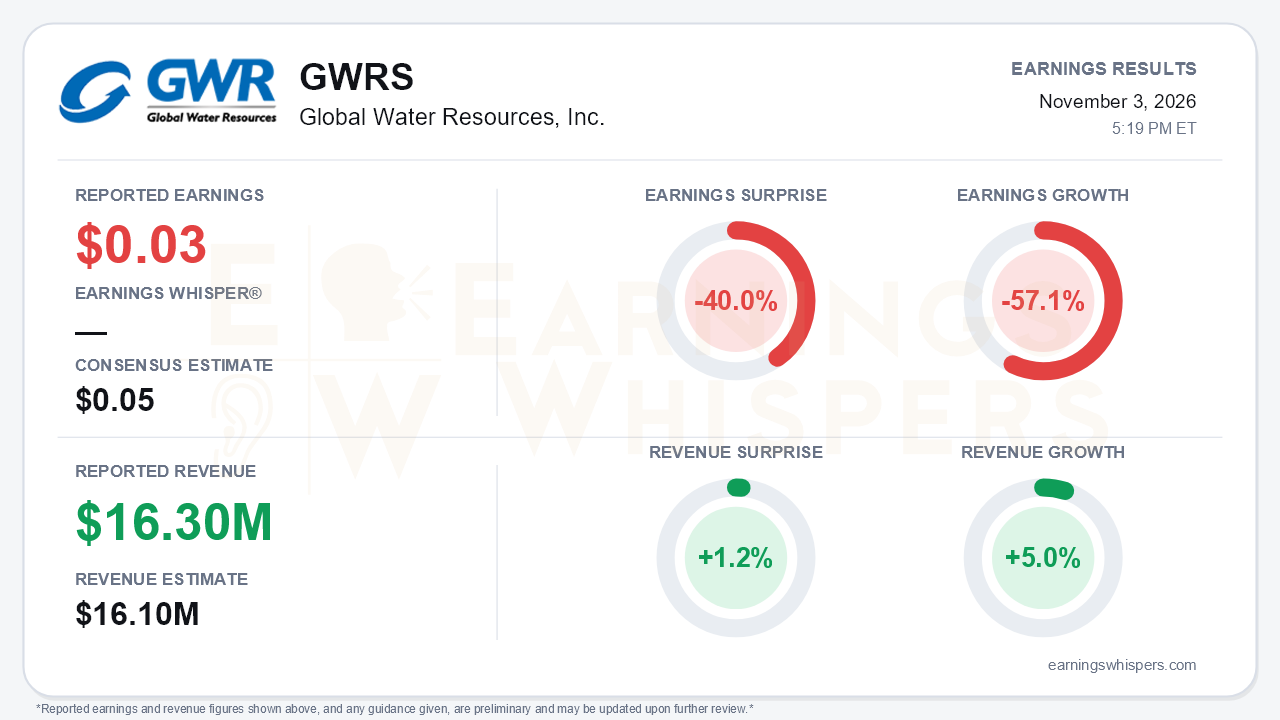
Global Water Resources (NASDAQ: GWRS) delivered a third quarter that split cleanly between a weak income statement and an improving regulatory pipeline. The company earned $0.03 per share, missing the $0.05 consensus by 40.0%, as earnings fell 57.1% from a year ago. Revenue of $16.3 million edged past the $16.1 million estimate by 1.2% and grew 5.0%. That is the central tension. GWRS is spending heavily to build rate base, and the costs of those assets are hitting the P&L well before regulators let the company recover them. This quarter, that gap widened rather than narrowed.
The miss came from cost structure, not demand. Depreciation, amortization and accretion jumped 30.4% to $4.6 million, driven by a 15.3% increase in depreciable assets after the 2025 capital program put a large batch of plant into service. Utilities, chemicals and repairs rose 31.6% as two new wastewater plants and higher electricity rates added operating cost. Interest expense climbed on a December 2025 term loan and revolver borrowings. Total operating expenses grew 10.4%, roughly double the pace of revenue, and operating income fell to $2.4 million from $2.9 million. Adjusted EBITDA was flat at $7.8 million. The non-GAAP view offers no cover: adjusted EPS was also $0.03, down from $0.07. G&A held at $4.8 million, which is the one clear sign of cost discipline. Management also cited medical and liability insurance costs rising at an "unprecedented pace."
The sequential picture is what should concern investors. Regulated revenue growth slowed to 5% from 9.9% in the second quarter, and adjusted EBITDA went flat after a 15% gain in Q2. EPS dropped to $0.03 from $0.10 in the prior quarter. Organic growth is cooling too. Active connections rose 2.4% to 69,797, down from 2.7% organic growth in Q2 and below the 3.2% run-rate management cited last quarter, when it said growth would "accelerate." Maricopa permits swung from up 5.7% year-to-date at the Q2 report to down 2.1%, and Phoenix MSA permits are down 10%. Management blamed mortgage rates near 7.5% and called the slowdown temporary, noting October permits put Maricopa about 2% ahead year-to-date. The tone shifted from "growth is strong" to "despite the headwinds," and management conceded earnings have been "under pressure for the last few years."
The regulatory track did advance. The November 3 release described the GW-Santa Cruz settlement as still awaiting a November 4 ACC vote. By the November 5 call, the commission had unanimously approved it. New rates take effect December 1, slipping from the earlier November 1 target, and add $2.3 million in water revenue. After a $0.4 million Palo Verde reduction, the net annual gain is $1.9 million. Management said the order resolves the long-running Southwest plant asset issue and sets rate base about 50% above the last decision. Four more filings are slated for the first half of 2027 on a 2026 test year, covering Palo Verde, Farmers, Ocotillo and Saguaro. Management is also evaluating formula rates and PFAS or infrastructure surcharges to shorten regulatory lag. The catch is timing. Palo Verde, the larger rate base, won't see new rates until 2028, and management declined to size the upcoming requests or offer guidance.
The balance sheet adds a further complication. The $10 million private placement and the credit line increase to $30 million (undrawn) shore up liquidity. Cash, however, sits at $3.5 million versus $15.3 million a year earlier. Diluted shares rose about 6.6% year over year, so dilution compounds the pressure on per-share earnings while profits are depressed. Capital spending has slowed sharply, to $19.8 million year-to-date from $49.6 million. That should eventually ease the depreciation step-ups.
Investor sentiment turned decisively. It fell from a marginally positive 0.06 to a negative 0.27, a meaningful shift for this scale. The stock has held up better than that mood suggests. Shares are up 5.7% since the open after the August report and sit 3.7% above the 200-day moving average. They closed near the top of the inter-earnings range. Both the $8.21 high and the $7.50 low printed on November 4, which points to a volatile post-report session that ultimately resolved near the high. The Earnings Whispers trend readings are mostly neutral, though AVWAP remains negative.
The bottom line is that GWRS traded a disappointing quarter for a cleaner regulatory runway. Santa Cruz rates help starting in December, but $1.9 million in annual net revenue does not offset the depreciation, interest and insurance costs now running through the P&L. Meaningful relief depends on 2028 rate outcomes and on whether connection growth reaccelerates. Bears have legitimate ammunition in the decelerating growth, compressed margins and dilution. The stock's resilience suggests investors are pricing the rate cycle more than the current earnings.
Read our earnings preview for Global Water Resources, Inc.: https://www.earningswhispers.com/article/GWRS/22111
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-03 | |
| Oct-30 | |
| Oct-28 | |
| Oct-14 | |
| Sep-30 | |
| Sep-01 | |
| Aug-31 | |
| Aug-17 | |
| Aug-12 | |
| Aug-12 | |
| Jul-31 | |
| Jul-22 | |
| Jun-30 |
