AerSale Beats On Revenue But Misses Badly On Earnings As A Q4 Flight-Equipment Bet Collides With Thinning Liquidity
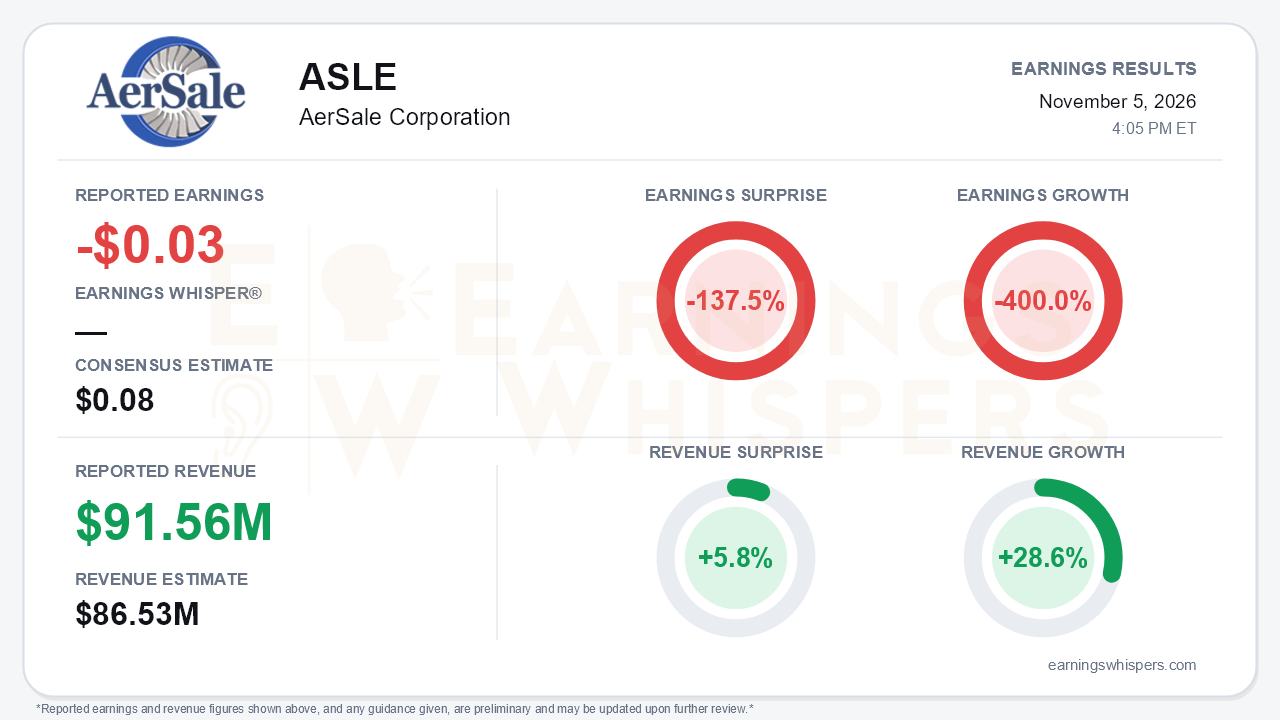
AerSale Corporation (NASDAQ: ASLE) delivered the top-line rebound investors had been waiting for, but the bottom line moved the other way. The company reported a loss of $0.03 per share on revenue of $91.56 million for the September quarter. Consensus had expected a profit of $0.08, so earnings missed by 137.5%. Revenue topped the $86.53 million consensus by 5.8%. Revenue grew 28.6% year over year, a sharp reversal from the roughly 34% decline posted in the second quarter, while earnings fell 400.0%. On a GAAP basis the loss was far larger at $0.31 per share. That figure includes a $13.4 million non-cash goodwill impairment, which wiped out the entire asset-management goodwill and which the call tied to the sustained decline in the share price. The company's own adjusted loss was $0.02 per share, versus adjusted earnings of $0.04 a year ago. The central tension is clear: demand and revenue are recovering, but margins, cash generation and liquidity are still deteriorating, and the turnaround thesis now rests heavily on a fourth quarter that has not yet happened.
The quality of the revenue beat deserves scrutiny. About $9.3 million came from Flight Equipment sales, consisting of a single engine, compared with just $0.4 million a year earlier. Excluding those sales, revenue grew 16.2% to $82.3 million. That is still a genuine improvement after a 4.2% decline in the second quarter and 2.2% growth in the first, and it was driven by leasing, used serviceable material, heavy MRO and AerSafe kit deliveries. Profitability, however, moved backward:
- Gross margin compressed to 22.5% from 30.2%.
- TechOps gross margin was halved to 12.5% from 25.3%, and component MRO shops ran at mostly negative margins.
- Asset Management gross margin slipped to 30.5% from 34.1% on weaker leasing margins.
- Adjusted EBITDA of $8.6 million rebounded sharply from $2.2 million in the second quarter, but it was down from $9.5 million a year ago, and margin fell to 9.3% from 13.3%.
Management attributes the margin pressure to ramp-up costs on new programs that should fade. That is plausible, but for now it remains an expectation, not a result.
The operating story is better than the margins suggest. TechOps revenue jumped 28% to $41.0 million, accelerating from 8.7% growth in the second quarter. Engineered Solutions revenue nearly quadrupled to $8.4 million, and heavy MRO rose to $16.3 million. The call added a stack of demand wins:
- A multi-line 757/767 heavy-check contract with a leading North American cargo airline at Goodyear, a facility running below 20% utilization last quarter.
- Spirit aircraft freed up for heavy maintenance through 2027.
- A third line at Millington, with a possible additional facility and third shift.
- New A330 landing-gear overhaul capability.
Five of seven 757 freighters are now on lease, up from three, and the final two are committed. Management said the MRO operations should become EBITDA contributors starting in 2027. There are offsets, though. Leasing growth slowed to 11% from 50% in the second quarter, and AerSafe demand is peaking ahead of the November 2026 FAA deadline, which creates a tough comparison next year.
The balance sheet is where bears have legitimate ammunition. Liquidity has fallen steadily:
- $71.6 million at year-end
- $41.8 million in the first quarter
- $34 million in the second quarter
- $23.1 million now, including only $3.9 million in cash
Revolver borrowings climbed to $158.7 million from $110.1 million at year-end. Year-to-date free cash flow was negative $49.8 million, and interest expense is rising. Management is counting on fourth-quarter Flight Equipment closings, led by the $35 million Boeing 737 sale to the U.S. Marshals Service, to restore liquidity and deliver a "significantly stronger" quarter. That same sale was previously expected in late third quarter or early fourth, and it has slipped again. Management also declined to provide fourth-quarter guidance and did not explicitly reaffirm earlier expectations for revenue and profitability growth in 2026. The promised stronger second half is now effectively a one-quarter bet.
Investor sentiment heading into the report improved meaningfully, moving from slightly negative (-0.08) to moderately positive (+0.34). The tape tells a less optimistic story. Shares closed at $4.97 before the release, down 15.9% from the $5.91 open following the August report and about 20% below the 200-day moving average of $6.23. The stock hit a 52-week low of $4.54 on October 22 and has recovered only about 9.5% from that level, sitting far closer to the bottom of its inter-earnings range than the $6.09 high. The Earnings Whispers trend signals lean negative, with price and AVWAP trends weak while sequential growth and momentum are neutral.
The bottom line is that AerSale showed real evidence that demand is returning, with accelerating TechOps growth, new heavy-check contracts and a nearly fully leased 757 freighter fleet. Those gains have not yet translated into margins or cash, while the earnings miss, the impairment and shrinking liquidity raise the cost of further delays. Improved sentiment suggests investors are willing to look ahead, but the stock's position near its lows reflects how much now depends on the 737 sale and other Flight Equipment deals finally closing in the fourth quarter.
Read our earnings preview for AerSale Corporation: https://www.earningswhispers.com/article/ASLE/22240
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 6 hours | |
| Oct-28 | |
| Oct-22 | |
| Oct-06 | |
| Sep-16 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Jul-24 | |
| May-21 | |
| May-07 | |
| May-06 | |
| Apr-23 | |
| Mar-31 |
