Funko's Margin-Driven Beat Masks Sharp Slowdown In Sell-Through And Unchanged Sales Outlook
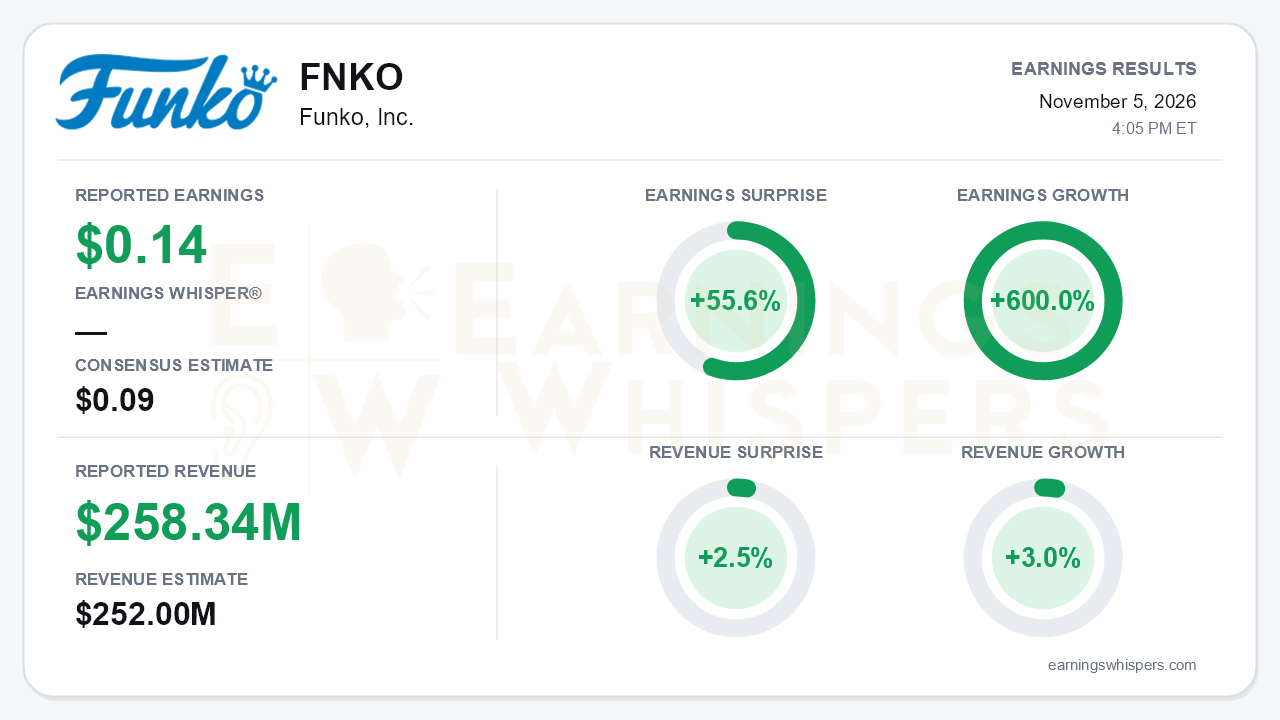
Funko (NASDAQ: FNKO) delivered a clean profitability beat in the third quarter, but sales growth slowed. On Earnings Whispers' normalized basis, the company earned $0.14 per share against a $0.09 consensus, a 55.6% surprise. Earnings grew 600.0% from a year ago. Revenue of $258.34 million topped the $252.0 million consensus by 2.5% and rose 3.0% year over year. The company's own figures were $0.13 per diluted share on a GAAP basis, up from $0.02, and $0.16 on its adjusted basis, up from $0.06. That is the central tension: margins and the balance sheet keep improving while sales and consumer sell-through slow.
The quality of the beat leans heavily on gross margin. Gross margin expanded five points to 45.2% from 40.2%, and it landed above the 42% to 44% range management had guided. Cost of sales fell by nearly $9 million even as net sales rose $7.4 million. That margin gain carried adjusted EBITDA to $32.1 million, a 12.4% margin, from $24.4 million. SG&A ran the other way, climbing to 33.6% of sales from 31.8%, so operating leverage came from product economics rather than cost discipline. The mix beneath the 3.0% total was uneven:
- Core Collectibles grew 4.8%.
- Loungefly fell 9.8% as the company rationalizes SKUs.
- U.S. sales declined 2.4%, offset by double-digit gains in Europe and Other International.
The call made the deceleration hard to ignore. Quarterly net sales growth has gone from +5% in Q1 to +7% in Q2 to +3% now. Core Collectibles growth fell from +17% in Q1 to +9% in Q2 to roughly +5%. Europe, the bright spot, slowed to +12% from +19%. The more important signal is point-of-sale data. Global POS units fell 4% after rising 6% in each of the first two quarters. Within that, U.S. units dropped 10% while EMEA rose 16%. Management attributed the U.S. weakness to a tough comparison against tariff-delayed shipments last year. That is plausible, but direct-to-consumer units also fell 13% as the company pulled back on promotions. Bears have legitimate ammunition: the margin improvement is partly being bought with lower volume.
Guidance reinforces the caution. Funko held its full-year outlook at flat to up 3% sales growth, 46% to 47% gross margin, and $100 million to $110 million of adjusted EBITDA. Both profit targets include a $25.4 million tariff-related benefit booked in Q2. Year-to-date sales are up about 5%, so an unchanged sales range implies a flat-to-down fourth quarter. With $84.3 million of adjusted EBITDA already banked, the full-year range implies roughly $16 million to $26 million in Q4. The CFO called the holiday quarter "tough to predict," hardly the language of a company expecting a strong close.
The catalysts are real, if early. The Pop Mystery launch reportedly sold three times faster than planned with full sell-through, and about a dozen IPs, including Hello Kitty and Harry Potter, are slated for next year. Live commerce is emerging as a new channel through an eBay Live auction, where a one-of-one Babe Ruth figure sold for $26,000, and continued TikTok live-selling tests. Pop Plush and new lines are set to be teased at February toy fairs. The balance sheet is the most tangible improvement:
- Total debt fell to $195.9 million from $241.0 million a year ago, and management cited net debt of $155 million.
- Nine-month operating cash flow swung to a $54.2 million inflow from a $33.2 million outflow.
- Part of that came from stretching payables, and financing activity also reflected tariff-receivable sale proceeds.
The market setup is more complicated than the surprise implies. Shares closed at $6.56 heading into the report, 5.0% below the $6.91 open after the August release. During the quarter they swung between a 52-week high of $7.35 in late August and a low of $5.22 in mid-September. They have since recovered about 26% off that low and sit roughly 27% above the 200-day moving average. The Earnings Whispers trend readings are mostly positive, reflecting that rebound. Investor sentiment, however, stands slightly negative at -0.11, suggesting investors are not positioned for a strong holiday story.
The bottom line is that Funko is becoming a more profitable, less leveraged business, and the quarter proved it again with a margin beat and above-plan EBITDA. But the growth engine stalled in Q3: sales growth, Core Collectibles growth, and sell-through all slowed, and U.S. POS units fell double digits. An unchanged outlook points to a soft holiday quarter. Until new formats like Pop Mystery and live commerce show up in sell-through data, the bull case rests more on margins and deleveraging than on demand.
Read our earnings preview for Funko, Inc.: https://www.earningswhispers.com/article/FNKO/22287
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-21 | |
| Sep-26 | |
| Aug-10 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-31 | |
| Jul-22 | |
| Jun-26 | |
| May-07 | |
| May-07 | |
| May-01 |
