Westwood Holdings: Revenue Climbs 9.4% And Flows Stabilize, But A 24.5% Earnings Decline And A Shrinking AUM Base Cloud The Picture
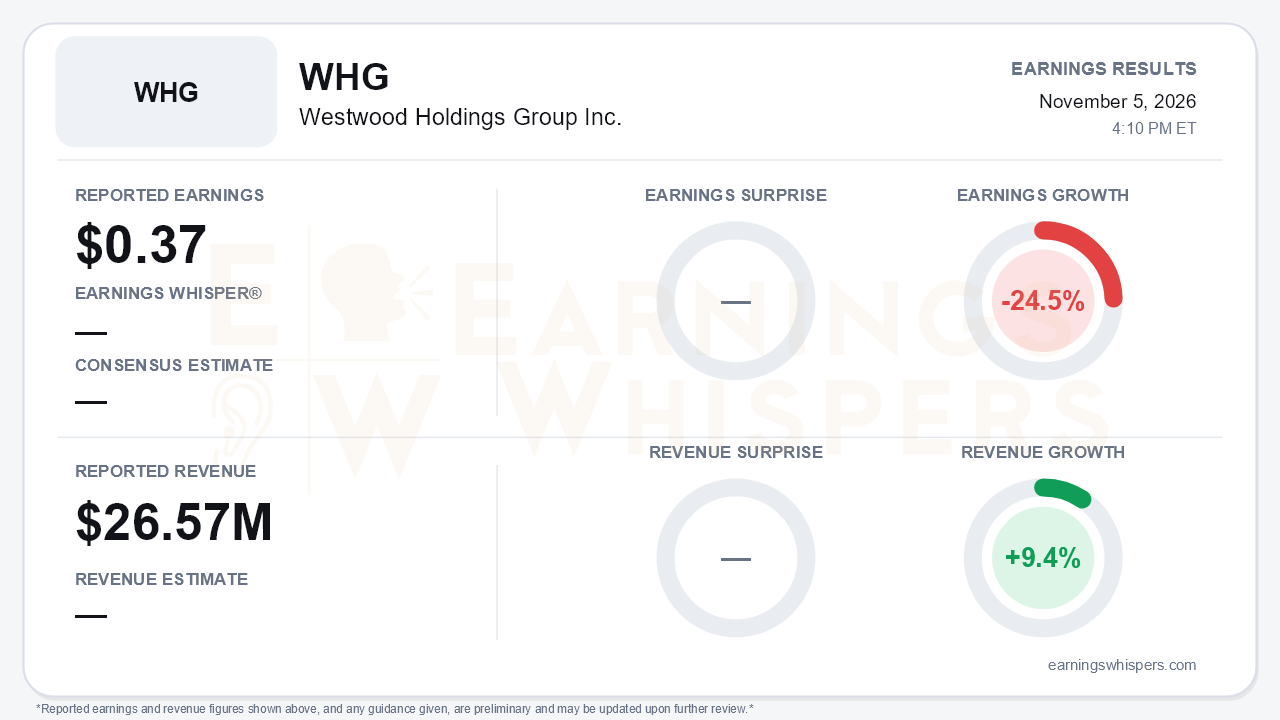
Westwood Holdings Group (NYSE: WHG) reported third-quarter earnings of $0.37 per share on revenue of $26.57 million. Earnings fell 24.5% from a year ago while revenue grew 9.4%, and that split is the central tension of the quarter. The top line is moving in the right direction, but year-over-year profitability is not. There was no published consensus or Earnings Whisper to measure the result against, so the quarter has to be judged on its internal trends. Those trends are more mixed than the sequential rebound suggests.
The per-share figures need some clarification. Earnings Whispers' normalized $0.37 sits between GAAP diluted EPS of $0.34 and the company's non-GAAP Economic EPS of $0.48. On every basis, earnings rebounded sharply from the second quarter, when GAAP EPS was $0.17 and Economic EPS was $0.33. On every basis, earnings also trailed the year-ago period, when GAAP EPS was $0.41 and Economic EPS was $0.64.
The quality of the sequential improvement deserves scrutiny. Pre-tax income of $4.6 million included $2.9 million of unrealized gains on private investments. Those gains came from mark-ups on the company's Texas Stock Exchange (TXSE) stake ($2.55 million) and its Ridgeline stake ($0.33 million), both after higher-valuation funding rounds. Net operating income actually fell to $1.4 million from $2.1 million in Q2 and $2.0 million a year ago.
Two factors drove that operating decline:
- **Severance:** $1.7 million of one-time severance-related compensation, which points to restructuring.
- **Professional services:** costs rose to $2.4 million from $1.6 million a year ago.
Excluding severance, the operating picture looks healthier. The revenue mix, however, shows where the growth came from. Core asset-based advisory fees slipped slightly from the second quarter, to $19.2 million from $19.4 million. Most of the sequential revenue gain came from "Other, net" revenue, which rose to $1.8 million from $0.6 million on private capital distributions. That source is lumpy by nature.
The call offered more encouragement on flows than on assets:
- **Flows:** Firmwide net outflows narrowed to $0.3 billion from $1.6 billion in Q2. Institutional net outflows nearly disappeared, at $3 million versus $1.3 billion.
- **Institutional sales:** Gross sales jumped to $556 million from $382 million, helped by a Fortune 50 company's defined contribution plan funding the SMidCap strategy with more than $450 million.
- **ETF platform:** Assets passed $430 million at quarter-end and reached roughly $460 million after the quarter, up from just over $200 million at the end of 2025. Westwood launched PWRX, an enhanced power and infrastructure ETF, as the first new ETF on the TXSE. It also agreed to move the DVQQ and DVSP defined-volatility ETFs onto its platform, targeted for early 2027 and subject to shareholder approval.
Assets under management still fell to $16.1 billion from $17.0 billion in Q2 and $17.3 billion in Q1. Most of the drop came from $0.6 billion of market depreciation as small/mid caps and bonds declined. That leaves a lower fee base heading into the fourth quarter.
Bears have legitimate ammunition elsewhere as well:
- **Private capital:** New commitments slowed to about $30 million from $147 million in Q2, although roughly $200 million has been raised year to date.
- **Client losses:** Small-cap value lost two public plan relationships.
- **Outlook:** Management described its outlook as "cautiously optimistic." It did not repeat the second-quarter goal of reaching $1 billion each in ETFs, private capital and Managed Investment Solutions (MIS), and it offered no formal financial guidance. Dropping a stated growth target without explanation is a softer signal than investors would want after a restructuring charge.
On the catalyst side, several items are in the pipeline:
- Westwood launched Energy Secondaries Co-Investment Fund 7 and said the energy secondaries team is now fully staffed.
- The MIS real asset strategy is under review for a consultant approved list, with possible inclusion by year-end.
- MDST won approval at a major wirehouse, and WEEI is pursuing approval at the same firm.
- Black Diamond was selected as the wealth platform, with the full wealth and multifamily office transition expected in 2027.
The balance sheet gives management room to execute. Cash and investments rose to $65.0 million from $56.5 million in Q2, the company carries no debt, and the $0.15 quarterly dividend was maintained. One caveat is that the dividend was about 1.3 times GAAP EPS this quarter but was covered by Economic EPS.
Market context is limited for this report. Investor sentiment readings and a current share price were not available. Shares opened at $19.35 following the August report, above a 200-day moving average now at $17.88, but the stock's current position relative to that level cannot be assessed from the supplied data.
The bottom line is that Westwood delivered a better-looking quarter than the second, with rising revenue, sharply reduced outflows and an ETF franchise that keeps compounding. Much of the earnings rebound, however, rested on unrealized investment marks and lumpy distributions, while core fees were flat and the AUM base shrank. Until asset-based fees resume growing and private capital raising reaccelerates, the 24.5% year-over-year earnings decline is a more honest read of the underlying trend than the sequential doubling.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-22 | |
| Oct-12 | |
| Sep-17 | |
| Sep-02 | |
| Aug-20 | |
| Aug-13 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 |
