Nyxoah Narrows Its Loss And Accelerates U.S. Growth, But The Ramp Is Slower Than Promised And Leading Indicators Are Cooling
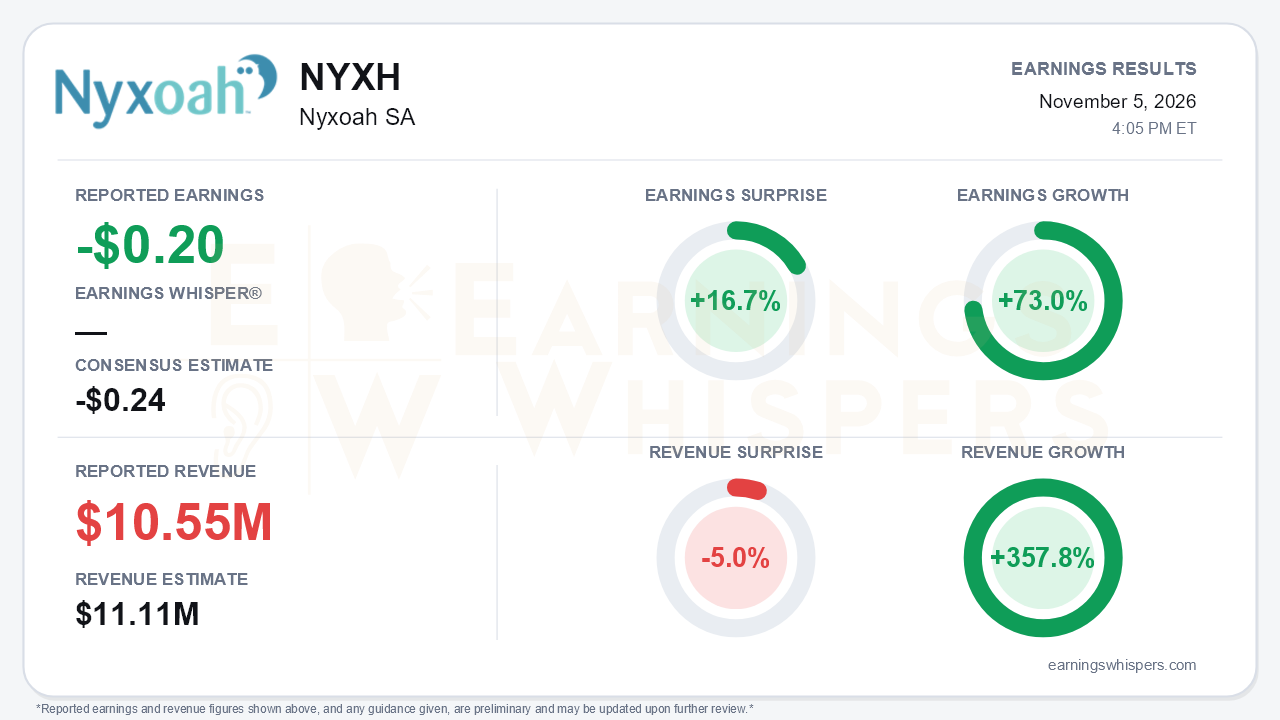
Nyxoah (NASDAQ: NYXH) beat on the bottom line and missed on the top line in a quarter that reads better on paper than in its details. The company reported a loss of $0.20 per share, better than the -$0.24 consensus, a 16.7% earnings surprise, and earnings grew 73.0% from a year ago. Revenue of $10.55 million, or €9.2 million, rose 357.8% year over year but missed the $11.11 million consensus by 5.0%. U.S. revenue grew 29% sequentially, faster than the 22% pace in the second quarter. That is the good news. The central tension is that this acceleration falls well short of the trajectory management had set out earlier in the year. The full-year revenue target has already been cut, both the CEO and CFO have been replaced, and several commercial leading indicators softened at exactly the point the ramp was supposed to steepen.
The quality of the earnings beat deserves scrutiny. Operating loss improved to €21.9 million from €24.4 million, helped by higher gross profit and a cut in R&D spending to €11.8 million from €12.9 million. SG&A, however, climbed to €16.0 million from €12.7 million. The larger swing came below the operating line. Financial income of €7.3 million, against €1.1 million a year ago, did much of the work in narrowing the net loss to €17.8 million from €23.6 million. The per-share comparison is also flattered by a much larger share count after this year's equity raises. The loss per share fell to €0.177 from €0.630, while the absolute loss improved far less. Gross margin is the cleanest positive. It reached 63.1%, up from roughly 60% in the second quarter and 57% in the first, as manufacturing volumes created operating leverage.
The call explained why revenue guidance is now €33-35 million, down from the €36-40 million range reaffirmed as recently as the second-quarter call. The company pre-announced the cut on October 19, so this release maintained an already lowered range that still sits below Street expectations. On the first-quarter call, management had framed third-quarter U.S. sequential growth in the low 40% range, approaching 50% in the fourth quarter. The quarter delivered 29%, and the ramp is now described as more reflective of historical launches of new technology. The pipeline metrics are the bigger concern:
- New account activations slowed to 53 from 89.
- Patients in prior authorization rose only 5% to 447 entering the fourth quarter, after a 77% jump the prior quarter.
- Surgeon training improved to 80 new surgeons from 55.
- The sales force expanded to 55 reps from 40.
For now, the commercial footprint is growing faster than the funnel it is meant to fill. By our arithmetic, the nine-month revenue of €23.2 million implies fourth-quarter revenue of roughly €9.8 million to €11.8 million under the new guidance, a wide band that includes a sharp sequential slowdown at the low end.
The regulatory story is the clearest positive and may matter most over the longer term. The ACCCESS pivotal study met its co-primary endpoints in complete concentric collapse (CCC) patients. It posted a 77.2% AHI responder rate and an 87.7% ODI responder rate, with zero device- or procedure-related serious adverse events. A PMA supplement to add CCC to the U.S. label has been filed. Management estimates CCC covers about one in four evaluated patients, a group competing therapy does not address. The final CMS rule also lifts 2027 facility payments by about 11% for hospital outpatient procedures and 13% for ambulatory surgery centers, though both came in slightly below the proposed rule. On the other side of the ledger, bears have legitimate ammunition:
- Cash fell €20.7 million in the quarter to €77.1 million.
- Financial debt totals about €52 million.
- No 2027 outlook was offered.
- The 80%-plus long-term gross margin target and the sub-€150 million breakeven framework were not reiterated.
- The new CEO, Liam Kelly, is repositioning Nyxoah as a commercially focused organization with an interim CFO beside him.
- Only one analyst asked questions on the call.
The market had largely priced in the disappointment before the release. Shares closed at $0.86 ahead of the report, down 36.8% since the opening after the August report. That leaves them nearly 65% below the 200-day moving average and just 7.4% above the 52-week low of $0.80 set on October 23, after a peak of $1.83 in early September. Investor sentiment remains deeply negative but improved modestly, rising to -0.69 from -0.80. Earnings Whispers trend readings on sequential growth and momentum have turned positive, while AVWAP remains negative, consistent with a stock that has been heavily sold even as quarterly revenue keeps building.
The bottom line is that Nyxoah delivered real progress on revenue growth, gross margin and the CCC regulatory path, but it is no longer the ramp investors were promised. The narrower loss owes as much to financial income and dilution as to operations. Account activations and prior-authorization growth slowed meaningfully, and new leadership has yet to replace the abandoned long-term targets. With the stock near its lows and sentiment only slightly less bearish, the next few quarters of U.S. funnel data will likely decide whether the CCC label expansion becomes a growth catalyst or simply extends the runway debate.
Read our earnings preview for Nyxoah SA: https://www.earningswhispers.com/article/NYXH/22352
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-26 | |
| Oct-19 | |
| Oct-15 | |
| Sep-28 | |
| Sep-23 | |
| Sep-21 | |
| Sep-07 | |
| Sep-02 | |
| Aug-25 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 |
