Applied Optoelectronics Beats And Signs A $1B+ 1.6T Deal, But A Slower Ramp And Lighter Guidance Reset The Story
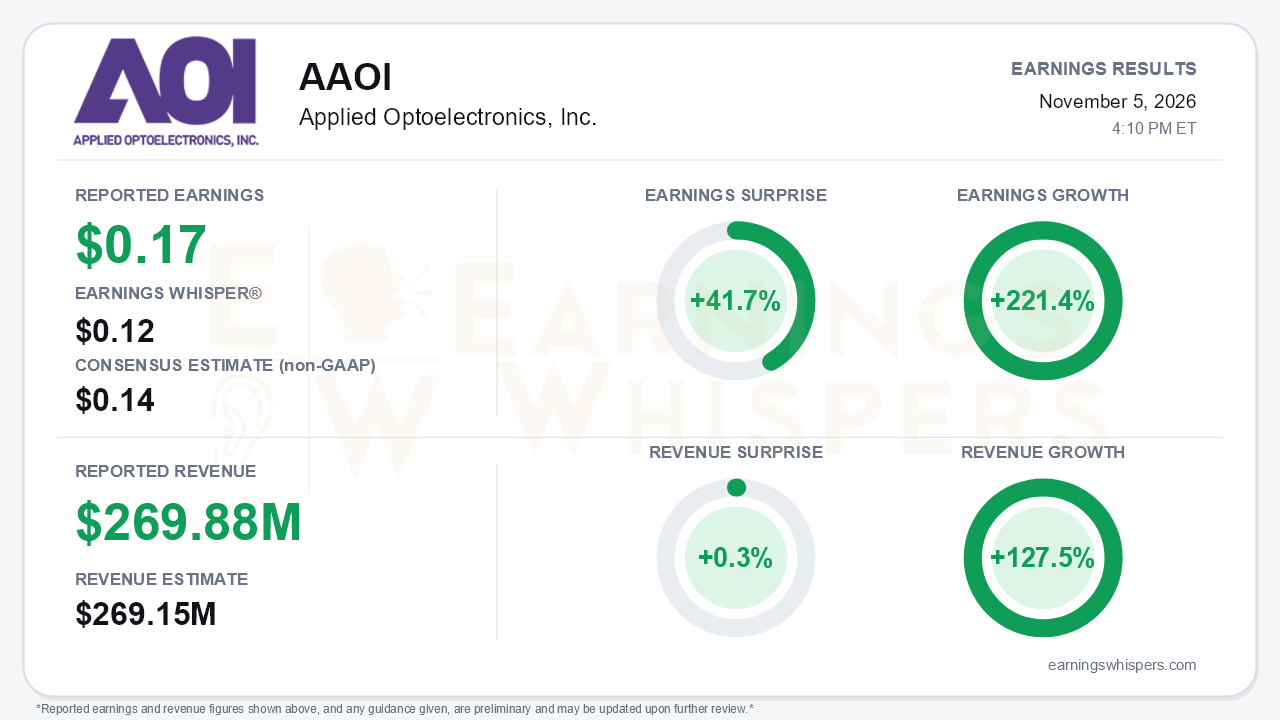
Applied Optoelectronics delivered the quarter bulls wanted on paper and the guidance bears were bracing for. Non-GAAP earnings of $0.17 per share beat the $0.14 consensus by 41.7% and topped the $0.12 Earnings Whisper number. Earnings grew 221.4% from the prior year, when the company posted a non-GAAP loss of $0.09. Revenue of $269.88 million rose 127.5% year over year. It was the sixth straight record quarter, though it beat consensus by only 0.3%. Sequential momentum clearly accelerated: revenue climbed 40.6% from Q2's $191.9 million, after smaller gains from $134.3 million in Q4 2025 to $151.1 million in Q1 and then to Q2. That is the central tension. The quarter itself was strong, but the multi-quarter trajectory management had been selling slipped on nearly every timeline that matters.
The quality of the beat deserves scrutiny. The headline return to GAAP profitability, $6.3 million versus a $22.8 million loss in Q2, came largely from below the operating line. AOI still posted a $1.4 million operating loss. Profitability was rescued by $8.2 million of other income and $3.1 million of interest income on a cash pile swollen by equity raises. The operating loss did narrow sharply from $18.2 million a year ago, which is real progress. Margins moved the wrong way, however. Non-GAAP gross margin of 28.7% missed the 29%–30.5% guide and slipped from 29.8% in Q2 and 31.0% a year earlier. Management blamed a mix tilted toward 400G, which nearly doubled to $93.4 million. 800G grew roughly 3.7x to $47.5 million, short of the roughly 5x sequential increase guided last quarter. CATV was the cleanest bright spot, reaching a record $110.9 million against a $100–110 million guide.
The outlook is where expectations were reset. Q4 guidance of $385–420 million implies about 49% sequential growth and non-GAAP EPS of $0.48–$0.63. Both figures would be impressive in isolation, but the revenue range falls below estimates. It also falls well short of the CEO's Q2-call suggestion that Q4 could exceed $500 million. Implied full-year revenue of roughly $1.015 billion compares with the $1.1 billion-plus framework management had repeated, and the $1.1 billion figure was not reiterated. The problem is not demand. The hyperscale customer pulled forward its shift from 800G to 1.6T, which left AOI short of 1.6T DSPs and raw materials. As a result, Q4 1.6T revenue is guided to only $50–70 million against roughly $450 million of orders in hand. The margin path was also pushed out: Q4 guidance of 29.5%–31% compares with exit-2026 targets of 32%–33% on the Q2 call and 35% on the Q1 call.
The call preserved a credible long-term growth story. AOI signed a multi-year agreement with an existing Tier 1 hyperscaler, exclusively for 1.6T transceivers, with a minimum 10% share commitment through May 2029. Management expects $1.0–1.5 billion of revenue from the deal, and its first 1.6T product has qualified at that customer. Management also said a second agreement, which could be five times larger and span 800G and lasers, is in final stages. Investors should treat that as an expectation, not a contract. The fine print matters too. The signed agreement locks pricing with built-in reductions and carries no customer capital commitment. On capacity, the company raised its end-2027 target to over 1 million units per month from 930,000. However, a roughly seven-month delay in the Phase 2 Texas expansion, driven by power and construction issues, cut the year-end 2026 target to over 500,000 units from 650,000. The same delay pushed the data center run-rate milestone from mid-2027 to the end of 2027.
Bears have legitimate ammunition beyond execution. The top 10 customers account for 99% of revenue, and a single CATV customer represents 41%. Inventory has roughly doubled since December to $378 million. Debt has risen to $148.1 million, and the company completed three at-the-market equity offerings this year, lifting the basic share count from 63 million to 85 million year over year. Management leaned toward debt for future funding and suggested 2027 capex may come in lower than feared. Still, a weak share price constrains the equity option.
The market had already priced in much of the disappointment. Shares entered the report at $59.27, down 58.4% from the $142.48 open after the August release. The stock sat 48.1% below its 200-day moving average and just 3.5% above the inter-earnings low set the day before the report, 63.2% off the August high. Investor sentiment, already negative, deteriorated further from -0.19 to -0.32, a meaningful but not extreme shift. The Earnings Whispers trend signals are mixed: sequential growth and momentum read positive, while price and AVWAP remain negative.
The bottom line is that AOI's demand problem is the kind most companies would want, but its supply, margin and timeline credibility took another hit. The 1.6T agreement and a potential second deal give the long-term thesis more contractual backing than it had a quarter ago. Near term, however, the company must prove it can convert a large order book into shipments and expanding margins before financing pressure and repeated guidance slippage define the story.
Read our earnings preview for Applied Optoelectronics, Inc.: https://www.earningswhispers.com/article/AAOI/22220
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 |
