Artivion Beats On Revenue, But A Margin Squeeze And New 2027 Perclot Headwind Drive A Steep Earnings Miss
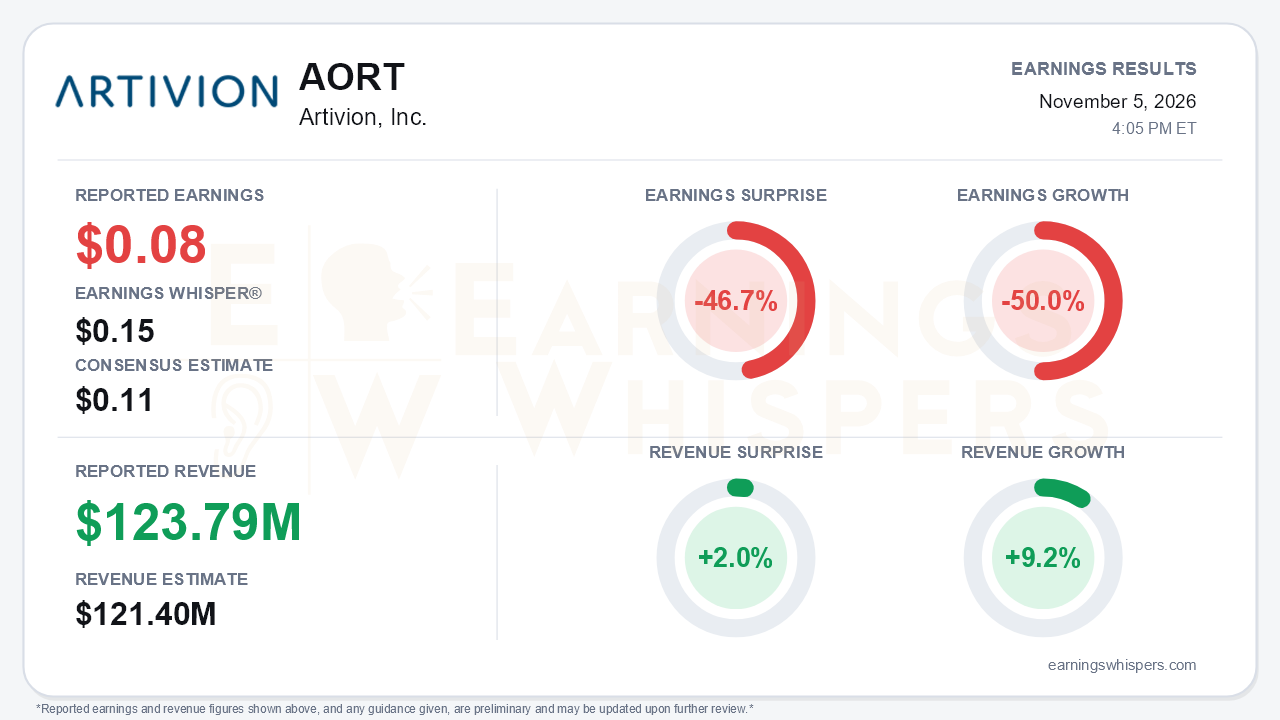
Artivion delivered the kind of quarter where the top line and the bottom line tell different stories. Revenue of $123.79 million rose 9.2% year over year and beat the $121.4 million consensus by 2.0%. Adjusted earnings of $0.08 per share, however, missed the $0.11 consensus by 46.7%, fell well short of the $0.15 Earnings Whisper number, and declined 50.0% from a year ago. On a GAAP basis, the company swung from net income of $6.5 million, or $0.13 per share, to a net loss of $7.9 million, or $(0.16) per share. That is the central tension: demand for the aortic portfolio is holding up, but the cost of growing it is rising faster than revenue.
The weakness sits in margins, not in a few one-time items. Gross margin fell to 61.4% from 65.6% a year earlier and from 64.0% in the second quarter. Product cost of sales rose about 28% while product revenue grew about 12%. Management attributed the decline to mix, On-X and NEXUS ramp costs, and period charges. Operating expenses rose to $73.0 million from $65.4 million. Adjusted EBITDA fell 8% to $22.5 million. That trajectory is worsening: EBITDA grew 26% in the first quarter and 7% in the second before turning negative. Below the operating line, interest expense rose to $8.5 million from $6.1 million after the debt-funded Endospan acquisition. Non-GAAP results also exclude $5.8 million of business development, integration, and severance costs. The quality of the miss deserves attention because it reflects structural cost pressure rather than noise.
The call kept the growth story credible but exposed cracks beneath it. Constant-currency growth of 9% matched the second quarter. Stent grafts grew 12% for a second straight quarter despite a tougher AMDS comparison, and U.S. AMDS implants rose sequentially after the PMA approval. On-X growth, however, slowed to 13% from 18% in the second quarter and 17% in the first. Surgical sealants and preservation services were flat. Management also acknowledged two softer points:
- **Core stent grafts:** growth has dipped into single digits in some quarters, well below historical mid-teens rates.
- **AMDS starter sets:** sales remain stuck on purchase-order and administrative barriers. Last quarter, management expected the PMA to accelerate set sales; this quarter it said the approval did not resolve those bottlenecks.
Guidance was narrowed rather than cut. Full-year revenue is now $484 million to $492 million, or 8% to 10% constant-currency growth, compared with $480 million to $496 million. Adjusted EBITDA guidance is $93 million to $98 million, compared with $92 million to $99 million. Arithmetically, both midpoints are unchanged, so the call's description of a lower midpoint holds only against the year's original outlook. That outlook called for 10% to 14% growth and $105 million to $110 million of EBITDA before the Endospan costs. The current range implies fourth-quarter growth of roughly mid-single digits, with currency turning into a headwind.
The forward catalysts are real and near-term:
- **ARTIZEN trial:** enrollment for ARCEVO LSA reached 56 patients, up from 30 last quarter. First 30-patient data will be presented as a late-breaker at the AATS Aortic Symposium on November 19.
- **NEXUS launch:** the U.S. launch remains on track for January 2027, with surgeon training starting in December.
- **On-X supply:** On-X exited the quarter in its strongest supply position in years after the Austin plant investment.
Management continues to frame the arch portfolio as a roughly $330 million U.S. opportunity. Against that, it introduced a new 2027 headwind: the end of the Perclot supply agreement with Baxter. That change is expected to take about 2 points off revenue growth and about 4 points off EBITDA growth. The balance sheet leaves less room for error than it did:
- Free cash flow was negative $17.6 million in the quarter.
- Cash fell to $48.4 million.
- Long-term debt rose to $363.8 million.
- Net leverage climbed to 3.5x from 1.8x in the first quarter.
- AMDS and NEXUS earnouts come due in 2028-2029, so deleveraging depends on EBITDA growth that is currently going the wrong way.
Investors entered the report cautious. Earnings Whispers sentiment was essentially unchanged and slightly negative, edging from -0.061 to -0.052. Based on the pre-report snapshot, shares at $26.45 were down 1.7% from the open after the August report. They were also 9.3% below the 200-day moving average and 12.2% below the inter-earnings high of $30.14 set August 19. The stock had, however, rebounded nearly 31% from its October 9 low of $20.21, so some recovery was already priced in before a quarter that delivered a profitability miss. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while AVWAP remains negative.
The bottom line is that Artivion's revenue engine and product pipeline remain intact, but this quarter shifted the debate from growth to profitability and leverage. Shrinking gross margins, a third straight quarter of decelerating EBITDA growth, cash burn, and a newly quantified Perclot hole for 2027 give bears legitimate ammunition. The upcoming ARTIZEN data and the NEXUS launch are the events that could change the narrative. Until margins stabilize, though, the revenue beat is unlikely to offset the earnings miss in investors' minds.
Read our earnings preview for Artivion, Inc.: https://www.earningswhispers.com/article/AORT/22234
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-28 | |
| Jul-23 | |
| Jun-29 | |
| Jun-10 | |
| May-18 |
