Alarm.com Beats Consensus But Misses The Whisper As A Fourth Guidance Raise Masks Slowing SaaS Growth
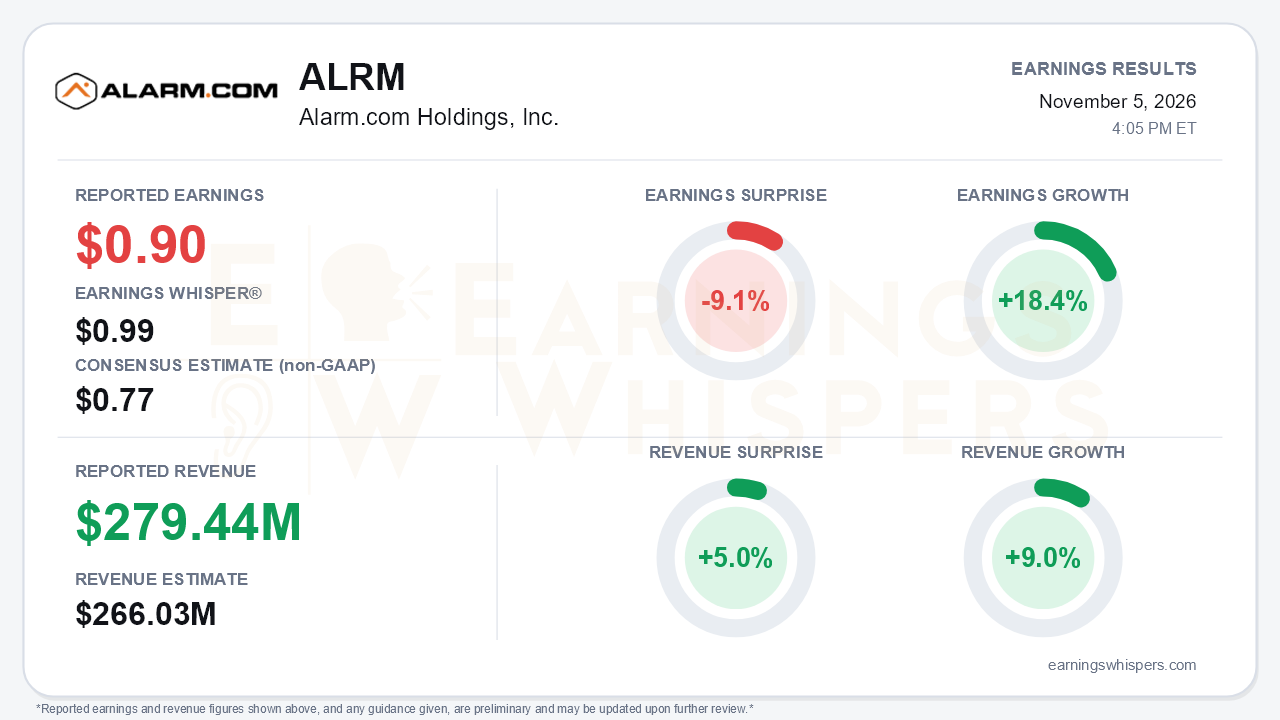
Alarm.com's third quarter cleared Wall Street's bar but not the one that mattered more. Non-GAAP earnings of $0.90 per share beat the $0.77 consensus but fell 9.1% short of the $0.99 Earnings Whisper number. Revenue of $279.44 million topped the $266.03 million consensus by 5.0%. Earnings grew 18.4% year over year and revenue rose 9.0%. Management also raised full-year guidance for the fourth consecutive quarter. The central tension is that the guidance trajectory keeps improving while the recurring-revenue engine keeps slowing. SaaS and license growth was 9.0% this quarter, down from 11.1% in the second quarter and 10.8% in the first, and management guided the fourth quarter to roughly 8%.
The quality of the beat deserves scrutiny. Much of the upside came from hardware, not software. Hardware and other revenue rose to $88.3 million, and hardware gross margin reached 28.4%, but that figure included about $3.8 million of one-time tariff cost recoveries. Meanwhile, SaaS gross margin compressed. Cost of SaaS revenue rose about 21% while SaaS revenue grew 9%. On a GAAP basis, the picture is flatter:
- Net income slipped to $34.3 million from $35.1 million.
- Diluted EPS edged up only to $0.66 from $0.65.
- Interest income fell to $4.9 million from $11.3 million after the company used cash to retire its $500 million convertible notes in January.
- Non-GAAP results exclude $6.3 million of litigation expense, up from $1.8 million a year earlier.
On a positive note, operating income rose to $43.9 million from $37.0 million. Free cash flow reached $69.5 million for the quarter and $156.3 million year to date, versus $102.0 million a year ago. Share repurchases of $58.5 million so far this year helped cut diluted shares to about 56.0 million from 58.5 million.
The call preserved a credible growth story. Full-year SaaS guidance now sits at $756.1-756.3 million, up from an initial $743-745 million. Adjusted EBITDA guidance climbed to $227-229 million from $213-215 million at the start of the year. Non-GAAP EPS guidance rose to $3.02-3.04 from $2.92-2.94 last quarter. Several operating details were encouraging:
- Revenue retention held in the roughly 95% range.
- Blended new-account residential ARPU has risen to about $5.50 from roughly $5 historically.
- The commercial fire communicator now has more than 600 service providers with paying units.
Management's tone was noticeably more upbeat. It framed Thrive Holdings' acquisition of ADT as industry validation, though the ownership change also introduces uncertainty around a large customer.
The preliminary 2027 outlook is the most important forward-looking development, and it cuts both ways. Management sees SaaS revenue of $815-820 million, total revenue of $1.175-1.19 billion and adjusted EBITDA of $240-245 million. The CellGate acquisition, which opens a channel of roughly 6,000 fence and gate contractors, is expected to add $15-20 million of SaaS revenue. Excluding CellGate, organic SaaS growth works out to roughly 5.5-6%. Analysts noted that is a better starting point than the initial 2026 view, but it is still a mid-single-digit growth profile. The implied 2027 EBITDA margin of about 20.5% falls slightly short of the 21% exit-2027 target management had reaffirmed on every prior call. CellGate is expected to dilute EBITDA margin for the next couple of years.
Bears have legitimate ammunition beyond that:
- Fourth-quarter hardware gross margin is guided to about 20.5% as memory costs rise ahead of planned price increases, implying a roughly $6.6 million sequential EBITDA headwind.
- International growth is lagging internal goals amid European consumer pressure.
- Growth initiatives are expected to slow from 25-30% to 20-25% in 2027.
The market setup is more complicated than the consensus beat implies. Shares entered the report at $67.96, up 19.0% since the opening after the August release. The stock sat just 0.4% below a fresh 52-week high of $68.23 set the day before earnings, 30.4% above its late-September low and 35.1% above its 200-day moving average. Investor sentiment moved the other way. It weakened from -0.39 to -0.65, a meaningful deterioration within already negative territory, even as the stock ran to new highs. The Earnings Whispers trend signals were broadly positive heading into the print. That combination of a stretched price and skeptical sentiment helps explain why a whisper miss and tariff-flattered margins could matter more than the headline beat.
The bottom line is that Alarm.com delivered another guidance raise, strong cash generation and a 2027 framework that modestly improves the organic growth starting point. However, its core SaaS growth is clearly decelerating, the margin beat leaned on non-recurring tariff recoveries, and the long-standing 21% margin target now looks harder to reach. With shares priced near their highs, investors will likely weigh those underlying trends more heavily than the beat against consensus.
Read our earnings preview for Alarm.com Holdings, Inc.: https://www.earningswhispers.com/article/ALRM/22232
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-06 | |
| Oct-06 | |
| Sep-10 | |
| Sep-01 | |
| Aug-18 | |
| Aug-07 | |
| Aug-06 | |
| Jul-23 | |
| Jul-23 | |
| Jul-16 | |
| Jun-18 |
