BJ's Restaurants Delivers Its Best Quarter Of The Turnaround, But The Guidance Raise Mostly Banks Q3 Ahead Of A Thinner Q4
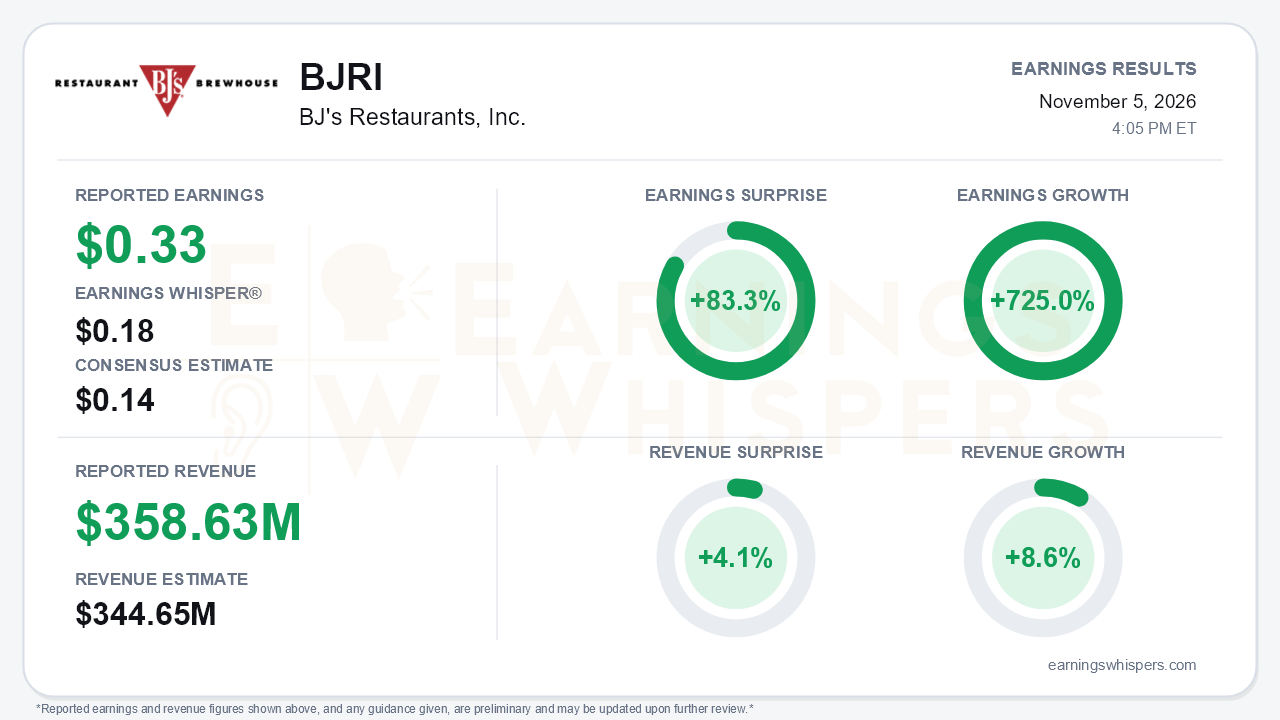
BJ's Restaurants (NASDAQ: BJRI) posted the strongest quarter of its recovery. Adjusted EPS was $0.33, well above the $0.14 consensus and the $0.18 Earnings Whisper number, an 83.3% surprise. Revenue of $358.63 million beat the $344.65 million consensus by 4.1% and grew 8.6% year over year. Adjusted earnings grew 725.0% from the $0.04 earned a year ago. GAAP results show the same improvement: diluted EPS rose to $0.24 from $0.02, and operating income swung to $5.2 million from a $1.0 million operating loss. Management also raised full-year guidance for the second straight quarter. The central tension is that the raise largely reflects the third quarter itself. The implied fourth quarter is far softer, and investors had already turned skeptical before the report.
The beat was driven by operations, not accounting. Operating weeks were identical to last year at 2,847, and the restaurant count was flat at 219. That means essentially all of the 8.6% revenue growth came from existing restaurants. Comparable sales rose 8.1%, with traffic up 8.3%. The gains flowed through most of the cost lines:
- **Labor** fell to 36.2% of revenue from 37.1%.
- **Occupancy and operating costs** dropped to 23.8% from 24.7%.
- **Cost of sales** eased to 25.3% from 25.7%.
As a result, restaurant-level operating profit rose 27.9% to $52.9 million, and margin expanded 220 basis points to 14.7%. Adjusted EBITDA jumped 48.6% to $31.4 million. The gap between GAAP and adjusted EPS comes mainly from a $2.75 million impairment and disposal charge that was added back. GAAP net income also benefited from a tax benefit. Neither item changes the core story.
The call showed clear acceleration across several measures:
- **Comparable sales** have stepped up from 2.6% in the year-ago fourth quarter to 2.4%, 6.5% and now 8.1%.
- **Restaurant-level margin** went from flat in the first quarter to up 20 basis points in the second to up 220 basis points in the third.
- **Average check** compression narrowed to -0.2% from -1.8% in the second quarter. The renovated pizza, burger and chicken sandwich menu added 40 basis points of check contribution sequentially.
- **Commodity inflation** cooled to roughly 2% from about 5%.
This matters because the earlier recovery was mostly traffic bought with value pricing, and pricing power is now starting to return. One caution: the year-ago third-quarter comparison was only +0.5%, so the 8.1% comp is partly flattered by an easy compare.
The outlook is where the case gets more complicated. Full-year comp guidance rose to about 4.7% from 3% to 4%. Restaurant-level operating profit guidance moved to $233 million to $237 million, and adjusted EBITDA guidance to $149 million to $154 million. However, management said the raise mainly reflects the third-quarter beat rather than higher fourth-quarter expectations. Analyst math puts the implied fourth-quarter comp in the high-1% range, for three reasons:
- **Calendar shift:** Halloween and Christmas timing creates roughly a 100-basis-point headwind.
- **Tough lap:** the quarter laps a strong fourth quarter of 2025.
- **Cost pressure:** occupancy and operating costs are guided to about 23% of revenue versus 22.6% a year ago, driven by marketing, general liability and repairs. Incentive compensation adds another $0.6 million to G&A.
Unit growth is also slipping. Only one of up to two planned 2026 openings will occur, with the Buckeye restaurant moving to the first quarter of 2027. The capex cut to about $80 million from $85 million to $95 million partly reflects a slower remodel and opening pace. On the positive side, management framed 2027 at roughly four to five openings, with faster remodels. The balance sheet is also much cleaner: net debt fell to about $4 million from $61 million at the start of the year. Buybacks were token at about $1 million in the quarter, leaving $84.5 million authorized.
The market setup is more complicated than the surprise suggests. Investor sentiment fell sharply into the report, from +0.28 to -0.12, turning negative. Shares were $61.75 on the eve of earnings. That is 13.2% below the opening price after the July report and roughly 14% under the inter-earnings high of $71.74, which was set the day after that report. The stock bottomed at $55.59 on October 23 and has since recovered about 11%. It remains nearly 21% above its 200-day moving average, so the longer-term trend has held even as the post-July enthusiasm faded. The Earnings Whispers momentum and AVWAP readings are positive, while price trend is neutral. That fits a stock that has been consolidating rather than breaking down.
The bottom line is that BJ's delivered exactly the kind of quarter turnaround skeptics were not positioned for: accelerating traffic, a recovering average check, and real margin leverage from the existing restaurant base. Bears still have legitimate ammunition. The raised guidance points to a sharp fourth-quarter slowdown, cost lines are set to turn less favorable, and unit growth has been pushed into 2027. The third quarter showed the model works. Whether that momentum survives the holiday calendar and tougher comparisons is now the question that matters.
Read our earnings preview for BJ's Restaurants, Inc.: https://www.earningswhispers.com/article/BJRI/22250
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-30 | |
| Oct-29 | |
| Oct-28 | |
| Oct-15 | |
| Oct-01 | |
| Sep-09 | |
| Sep-01 | |
| Aug-25 | |
| Aug-13 | |
| Aug-13 |
