Biodesix Breaks Its Beat-And-Raise Streak As Growth Slows To 10% And Guidance Falls Below The Original Outlook
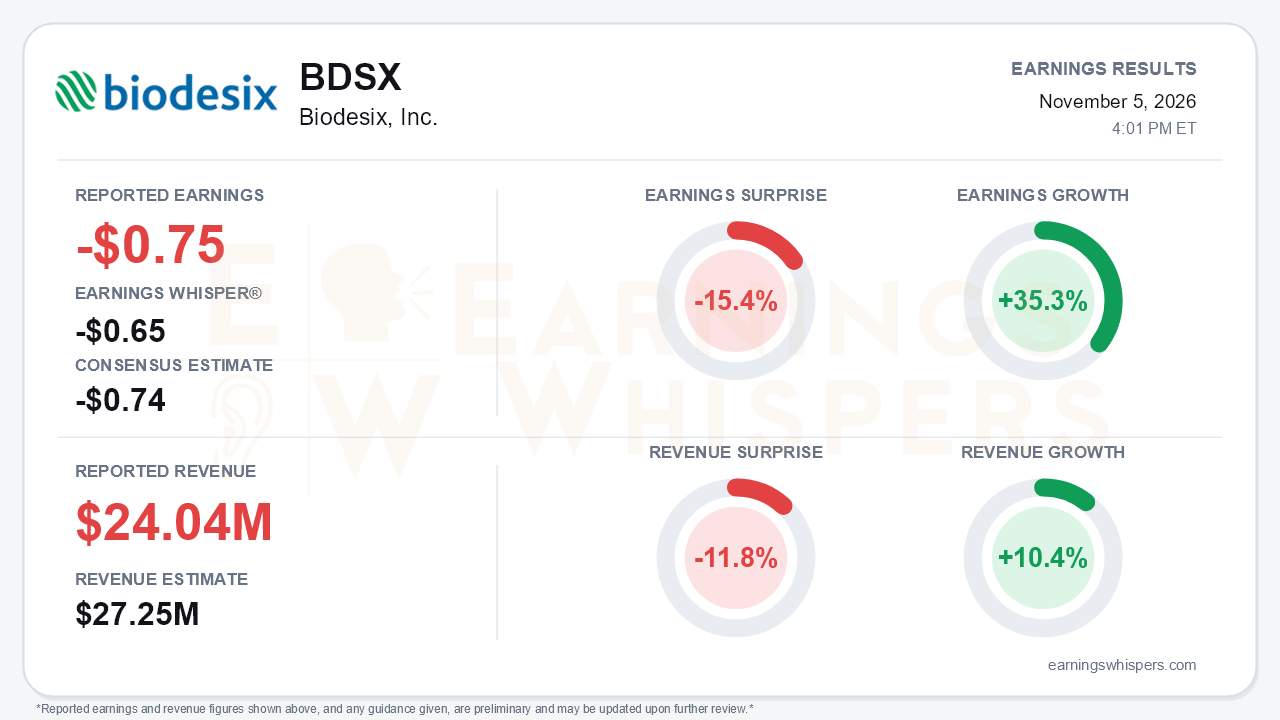
Biodesix (NASDAQ: BDSX) delivered the kind of quarter that resets a growth narrative. The company reported a loss of $0.75 per share on revenue of $24.04 million for the third quarter. The loss was a penny wider than the -$0.74 consensus and well short of the -$0.65 Earnings Whisper number, a 15.4% miss. Revenue missed the $27.25 million consensus by 11.8%. Earnings grew 35.3% year over year and revenue rose 10.4%, but those growth rates are not the story. The story is the guidance. Full-year 2026 revenue is now expected at $101 million to $103 million, down from $108 million to $114 million. That range was raised in the first quarter and reaffirmed in the second, and the new outlook sits below even the original $106 million to $112 million guide. Midpoint growth drops to roughly 15% from about 25%. That is the central tension: a company that had been compounding at 40%-plus is now asking investors to accept that the slowdown is about execution and timing rather than demand.
The quality of the per-share improvement deserves scrutiny. Net loss narrowed only 8%, to $8.0 million from $8.7 million. The much larger per-share gain owes heavily to dilution, with weighted-average shares climbing to 10.66 million from 7.50 million. Adjusted EBITDA loss improved 16% year over year to $3.9 million, but it widened sequentially from $3.2 million. That leaves the company far from the positive $0.5 million posted in the fourth quarter of 2025. Gross margin held at 81%, though that was a tick below the prior quarter's 82%, and management flagged higher shipping and fuel costs. Spending discipline was real. Operating expenses, excluding direct costs, fell 7% sequentially to $25.5 million, but cost control cannot offset a top line that stalled.
The deceleration beneath the headline is steep. Total revenue growth slowed from 42% in the first quarter to 34% in the second and just 10% in the third. Diagnostic Testing revenue grew 16%, down from 42% in the prior quarter. Test volumes rose 24% to 19,400 but actually fell sequentially from roughly 20,900. Average revenue per test was down 6% year over year on mix shift toward Nodify CDT, which management now characterizes as the new normal. Development Services revenue shrank to $1.0 million from $1.9 million a year ago and $3.3 million in the first quarter, with project starts delayed by external customer dependencies. Management expects only about $1 million in the fourth quarter, with some work slipping into 2027.
Management attributed the miss to three factors:
- fewer productive sales reps, with the average falling to 101 from 104 on attrition and poaching by competitors;
- heavier-than-expected primary care seasonality;
- the services timing delays.
The tone shifted noticeably, from talk of exceptional, strong growth to a more defensive framing. CEO Scott Hutton said the problems were not a change in demand, clinical utility, or market opportunity. Bulls can point to the recovery in sales capacity, with headcount back to about 110 reps. October was the strongest month of new physician acquisition this year, and the services backlog edged up to $8.7 million from $8.5 million. Still, bears have legitimate ammunition. The year-end rep target was trimmed to about 115 from 120, and the guide implies normalized fourth-quarter lung diagnostics growth of only about 2%.
The strategic pipeline is the strongest part of the release. The American College of Chest Physicians (CHEST) published a lung nodule program framework that names validated biomarker testing as a core risk-stratification tool. Two West Coast institutions are embedding Nodify testing enterprise-wide. Biodesix also detailed several longer-dated programs:
- a Vanderbilt radiomics/AI nodule test targeted for 2028;
- dual MRD programs with Bio-Rad and Thermo Fisher;
- an ESR1 ddPCR test brought into its lab.
These are long-dated catalysts, however, and the balance sheet keeps them in tension with near-term results. Cash fell $1.6 million to $28.4 million even after $6.3 million of at-the-market proceeds, and continued reliance on the equity program means dilution is part of the funding model.
The market setup is more complicated than the modest EPS miss implies. Investor sentiment entering the report remained positive but softened slightly, to 0.33 from 0.36. Shares closed the pre-report session at $21.49, 1.2% below the open following the August report. That flat reading hides a round trip. The stock ran to a 52-week high of $31.97 on September 28 and then gave back nearly a third of that move, finishing 32.8% off the peak and just 8.7% above the inter-earnings low. Shares still sat 14.2% above the 200-day moving average. Most Earnings Whispers trend readings were positive heading into the print, with AVWAP the negative outlier, but they predate a quarter that undercut the growth momentum the stock had been priced on.
The bottom line is that Biodesix traded a credible acceleration story for a show-me story. The clinical validation and pipeline have rarely looked better, but sales-force execution, services timing, and pricing mix all moved the wrong way at once. The fourth quarter now has to demonstrate that a rebuilt rep count and October's physician momentum can restore growth before the cash runway forces more dilution.
Read our earnings preview for Biodesix, Inc.: https://www.earningswhispers.com/article/BDSX/22248
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-28 | |
| Oct-22 | |
| Oct-19 | |
| Oct-19 | |
| Oct-13 | |
| Sep-24 | |
| Sep-24 | |
| Sep-14 | |
| Sep-03 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 |
