Castle Biosciences Beats And Raises For A Third Time As TissueCypher Carries A Softening Dermatology Franchise
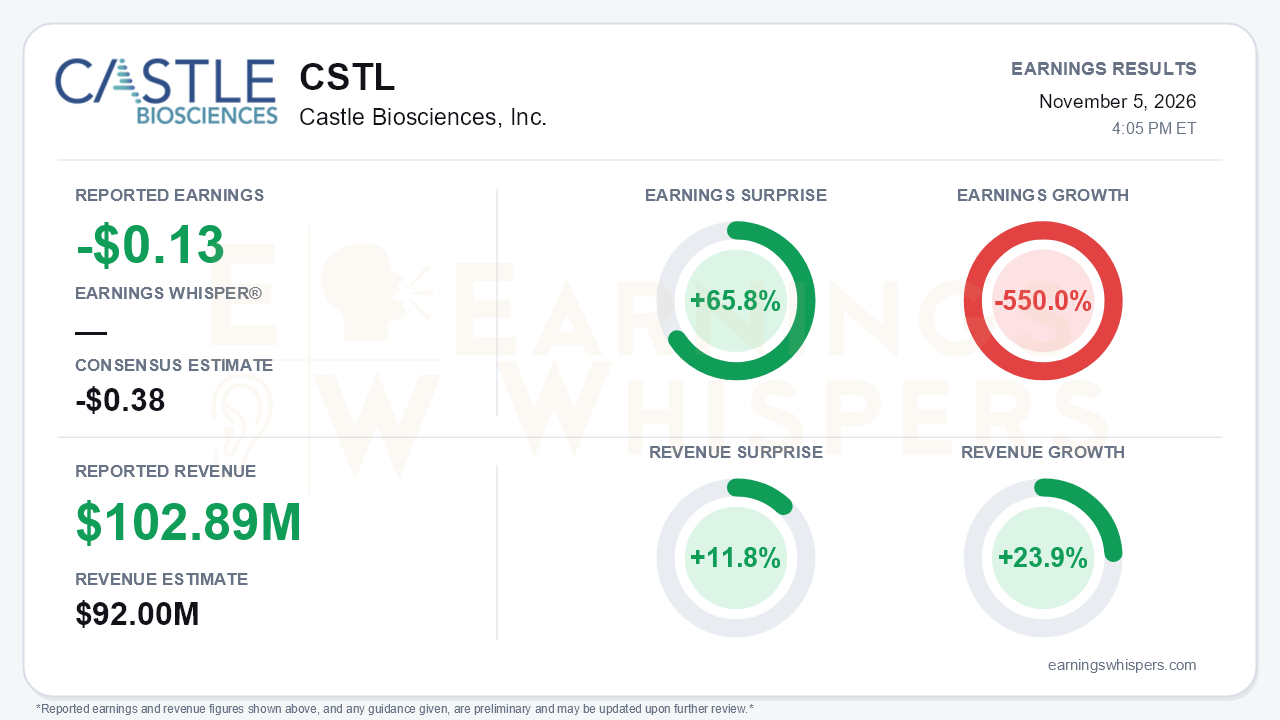
Castle Biosciences delivered a convincing top-line beat and its largest guidance raise of the year, but the quarter increasingly rests on one product. The company reported a third-quarter loss of $0.13 per share, well ahead of the -$0.38 consensus, a 65.8% earnings surprise. Revenue of $102.89 million topped the $92.0 million estimate by 11.8% and grew 23.9% year over year, faster than the roughly 20% pace of the second quarter. Management lifted full-year revenue guidance to $385-395 million from $365-375 million. That is the third straight increase and leaves the midpoint $45 million above where the year began. The central tension is that TissueCypher is doing almost all of the heavy lifting while the legacy dermatology engine slows and two reimbursement catalysts have slipped.
The headline loss deserves context. Earnings fell 550.0% year over year as the net loss widened to $4.1 million from $0.5 million. Operationally, however, the quarter improved. The operating loss narrowed to $2.7 million from $6.8 million. Adjusted EBITDA rose to $12.7 million from $9.2 million. The deterioration in net loss came largely from below the operating line: a $3.4 million loss on equity securities replaced a $3.6 million gain a year ago. The beat also does not appear to be flattered by prior-period revenue true-ups. Adjusted revenue of $101.9 million was slightly below GAAP revenue, meaning prior-period adjustments were a modest drag rather than a tailwind. Spending discipline is less convincing. Total operating expenses rose about 18%, with R&D up 22% and cost of sales up 28%. Adjusted gross margin of 76.5% was essentially flat year over year.
TissueCypher explains the beat. Test reports rose 47% to 15,574, penetration reached a roughly 15% run rate versus about 11% exiting 2025, and management reiterated 50-52% full-year volume growth. Equally important, management characterized recent ASP gains as durable, reversing its second-quarter framing that the pricing lift was non-recurring. Growth is decelerating against tougher comparisons, though, down from 63% and 58% in the prior two quarters. Management also flagged rising seasonality. Elsewhere the portfolio is soft:
- DecisionDx-Melanoma reports slipped to 10,177 from 10,459, and full-year growth guidance was trimmed to mid-single digits from mid-to-high single digits.
- DecisionDx-SCC reports fell 7%.
- MyPath Melanoma reports fell 31%.
AdvanceAD-Tx did add 1,109 reports, up from about 650 in the first quarter.
The forward risks are concrete. CMS proposed gapfill pricing for AdvanceAD-Tx instead of the crosswalk its advisory panel recommended 21-0, with a final decision expected in early December. That uncertainty is keeping commercial focus on melanoma. The hoped-for second-half 2026 draft LCD restoring SCC Medicare coverage has also slipped. Management now assumes no SCC Medicare revenue in 2027 and has moved it into the 2028 plan, though a draft LCD could still appear within a quarter or two. Guidance itself implies fourth-quarter revenue near $100 million, flat to down from the third quarter. Management is also assuming flat ASPs, so the outlook does not bank further pricing upside. On the positive side, the second-quarter TissueCypher sales force expansion should contribute more in the fourth quarter and 2027, and positive adjusted EBITDA for 2027 was reiterated. A $277.7 million cash position and $19.7 million of quarterly operating cash flow remove any funding concern.
The market setup is more complicated than the surprise implies. Shares rallied 24.3% from the $28.75 open after the July report to $35.75 heading into this release. That leaves the stock about 25% above its 200-day moving average and about 30% above the inter-earnings low set the day after the last report. The stock had already pulled back about 8% from its $38.73 quarter high on October 29, however. Investor sentiment moved the opposite way, falling from -0.23 to -0.41, so it was negative before the report and became meaningfully more so as the price climbed. Price, momentum and AVWAP trend readings are positive, reflecting a stock that has re-rated faster than investor conviction.
The bottom line is that Castle delivered a genuine beat-and-raise driven by TissueCypher volume and firmer pricing, with improving operating profitability beneath a GAAP loss distorted by investment marks. Bears still have legitimate ammunition: TissueCypher growth is decelerating, melanoma is stalling, implied fourth-quarter revenue is flat, and both the AdvanceAD-Tx pricing and SCC coverage catalysts have weakened. After a strong run into the print and with sentiment souring, the December CMS decision and early-2027 TissueCypher trends will matter more than this quarter's surprise.
Read our earnings preview for Castle Biosciences, Inc.: https://www.earningswhispers.com/article/CSTL/22268
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-28 | |
| Oct-15 | |
| Oct-12 | |
| Sep-30 | |
| Sep-28 | |
| Sep-24 | |
| Sep-22 | |
| Sep-15 | |
| Sep-09 | |
| Aug-20 | |
| Aug-17 | |
| Aug-03 |
