Celcuity Beats On Loss But Books No Revenue As REVTORPYK Launch Begins With Strong Access And A Rising Burn
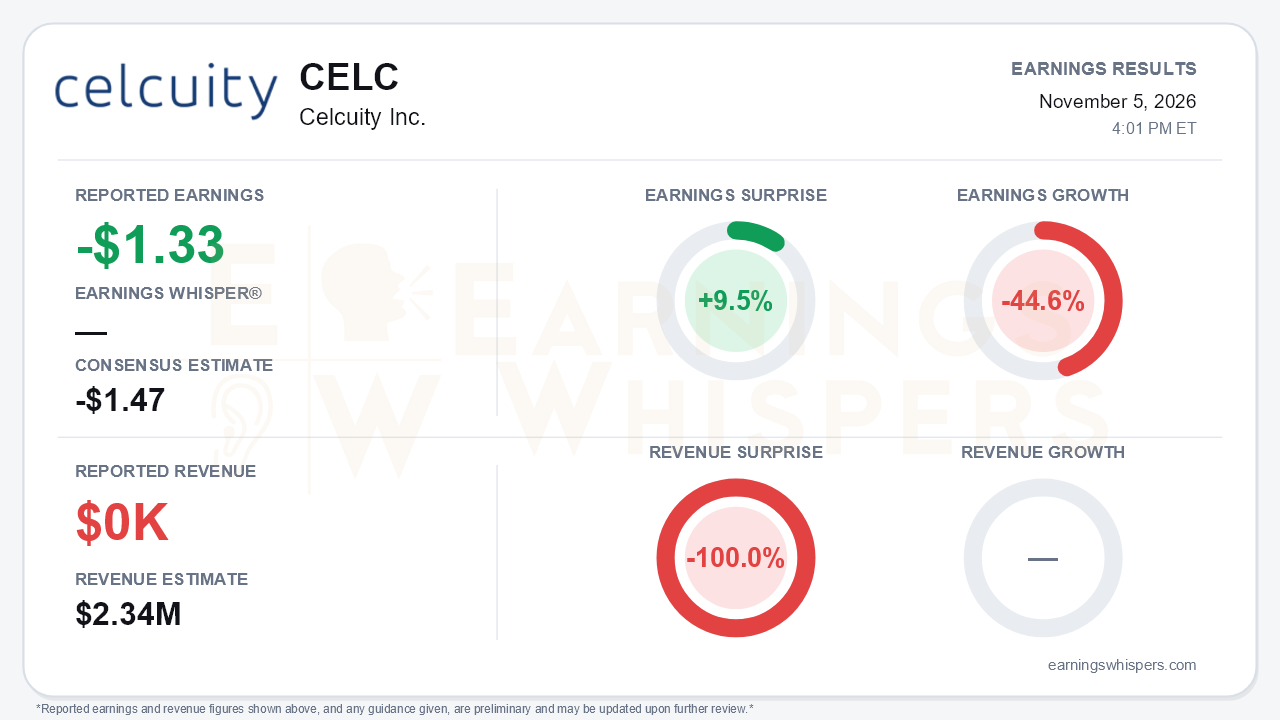
Celcuity's third quarter was less an earnings event than a handoff from clinical-stage story to commercial test. The company reported a loss of $1.33 per share, 9.5% better than the consensus estimate of a $1.47 loss, but earnings fell 44.6% year over year as the loss widened from $0.92 per share. Revenue was zero against a $2.34 million consensus, a 100% miss. The beat is real, but it says little about the launch. The miss is technically stark but largely a timing artifact, and the quarter's real information lies in early access metrics and the widening cost base.
The revenue shortfall needs context. REVTORPYK shipments began on September 30, and because no product reached providers or pharmacies until after quarter-end, Celcuity recognized no sales. Analysts modeling a few million dollars simply had the calendar wrong, so the miss does not show weak demand. It also does not show strong demand. Beneath the headline, spending is rising quickly. SG&A climbed to $39.8 million from $12.4 million a year earlier and from $35.0 million in the second quarter, with $25.3 million of the year-over-year increase tied to commercial headcount and launch infrastructure. R&D rose to $37.5 million. The non-GAAP adjusted net loss widened to $66.8 million from $58.7 million sequentially. Cash and investments fell to $642.7 million from $754 million at the end of the second quarter after $66.2 million of operating burn and a $50 million FDA-approval milestone paid to Pfizer.
The operating story from the release and call was clearly constructive. Within roughly a month of launch, 78% of the top 36 strategic accounts, which represent about half the addressable population, had ordered. Coverage reached 91% of U.S. commercial and Medicare lives, and the drug entered 3 of the 4 largest provider pathways. Only a quarter earlier, payer dossiers had just been submitted. NCCN granted a preferred Category 1 listing about two weeks after approval. Management also raised its second-line market framing to roughly $9 billion on a net basis, up from more than $6 billion last quarter. That figure rests on a $30,000-per-cycle list price and about 80% gross-to-net, which management reaffirmed and said is protected by grandfathering from new 340B changes. Investors should treat the $9 billion as a management sizing assumption, not a forecast.
The pipeline added further support. Updated VIKTORIA-1 data at ESMO showed 21.5 months of median progression-free survival for the triplet in PIK3CA-mutant patients without liver metastases, versus 9.1 months for alpelisib. Discontinuations from adverse events were 5% versus 19%. The mutant-cohort sNDA was filed on schedule, and prostate data improved enough to support a randomized Phase 2 starting in the first half of 2027. Bears still have legitimate ammunition:
- The buy-and-bill channel limits patient-level visibility.
- The permanent J-code does not take effect until April 2027, which creates friction for community sites.
- A second manufacturing site is not expected until mid-2027.
- The breadth of the mutant label is uncertain because the doublet carried no alpha.
- The overall survival readout due in the first half of 2027 may be muddied by crossover.
The next hard datapoint is the fourth-quarter sales flash in mid-January.
The balance sheet has also changed character. Management extended its runway guidance to "through 2029," helped by a $575 million convertible. That brought convertible notes to roughly $754 million and left stockholders' equity at a $74 million deficit. The runway is long, but the launch now has to grow into a meaningfully levered capital structure.
The market had already cooled heading into the report. Investor sentiment swung sharply from modestly positive (0.18) to clearly negative (-0.34), one of the more substantial shifts on the scale. Shares closed at $69.24 on the eve of the release. That is 16.6% below the open after the August report and about 31% beneath the 200-day moving average of $100.10. The stock peaked at $98 in early September and then slid to a 52-week low of $53.54 on October 16. It has since recovered about 29%, leaving it mid-range. Trend readings are mostly negative on price and AVWAP, though momentum has turned positive alongside that rebound.
The bottom line is that Celcuity delivered a narrower-than-expected loss and launch access metrics that were about as strong as investors could reasonably ask for one month in. A zero-revenue quarter and an accelerating burn, however, mean the commercial thesis remains unproven. With sentiment soured and shares well off their highs, the mid-January sales flash becomes the pivotal test of whether coverage and account uptake are converting into prescriptions.
Read our earnings preview for Celcuity Inc.: https://www.earningswhispers.com/article/CELC/22457
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-29 | |
| Oct-29 | |
| Oct-24 | |
| Oct-23 | |
| Oct-22 | |
| Oct-05 | |
| Oct-02 | |
| Sep-30 | |
| Sep-01 | |
| Aug-26 | |
| Aug-14 | |
| Aug-13 |
