BARK's Revenue Beat And Commerce Return Strengthen The Turnaround Case, But A Reaffirmed Outlook And Bark Air Exit Keep Skeptics Engaged
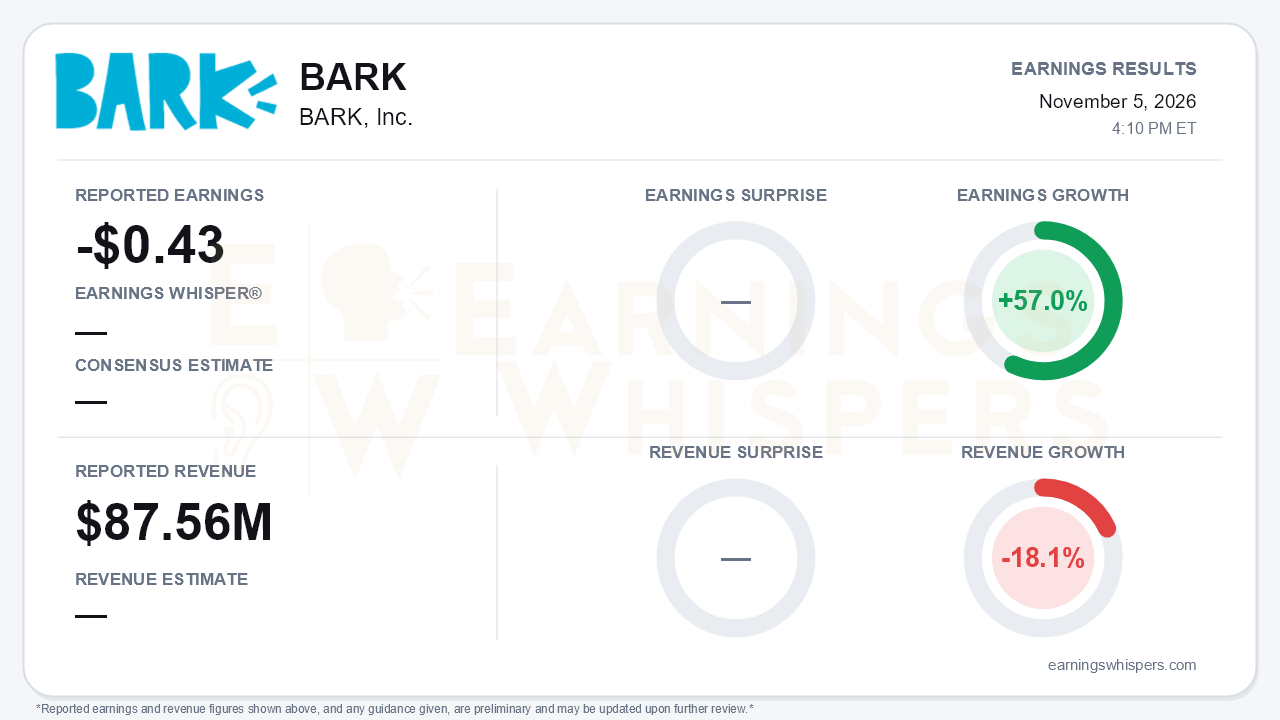
BARK, Inc. delivered its clearest evidence yet that its shrink-to-profitability strategy can stabilize. Fiscal second-quarter revenue of $87.56 million cleared the top of its $83.0 million to $85.0 million guidance range, a wider beat than the first quarter's $78.8 million, which landed at the high end of guidance. The net loss narrowed to $0.43 per share from $1.25 a year earlier, a 57.0% improvement in earnings. No consensus EPS or revenue estimate was available, so the useful benchmark is the company's own guidance. The central tension is that operating momentum is improving while the formal outlook is not. Revenue still fell 18.1% year over year, adjusted EBITDA landed only mid-range, and full-year guidance was reaffirmed rather than raised.
The beat deserves some scrutiny. The revenue decline was largely by design: advertising and marketing spend fell to $10.4 million from $15.4 million, and direct-to-consumer revenue fell to $61.8 million from $82.1 million. DTC orders dropped to 1.86 million from 2.54 million. Even so, the quality of what remains improved:
- Subscriber retention rose to 94% from 92%.
- Average order value increased to $31.40 from $30.87.
- DTC gross margin, excluding Bark Air, expanded to 70.1% from 65.6%.
- Consolidated gross margin rose about 100 basis points to 58.9%. According to the call, this figure contains no tariff refunds, unlike the first half's results, which included a $7.4 million IEEPA tariff benefit.
The GAAP picture is less clean than adjusted EBITDA of $2.0 million suggests. The operating loss was still $5.2 million, and interest and other income cushioned the bottom line. Litigation expenses tied to a shareholder class action rose to $1.1 million and are excluded from adjusted EBITDA.
The call supplied the more encouraging inflection. Commerce revenue grew 3.6% to $25.7 million, reversing an 11% decline in the first quarter and an 18% decline in the fourth quarter of fiscal 2026. Management modestly reinvested in marketing, raising spend from $9.5 million in Q1 to $10.4 million. That increase drove a 26% sequential rise in subscriber additions, an early sign that efficient spending can rebuild the funnel. Other operating developments included:
- Licksters, the new enrichment toy line with a refill model, launched in August and was described as a hit.
- The two largest retail orders in company history, a Girl Scouts cookie program and a Harry Potter collection at Costco, began shipping in the fiscal third quarter.
- Collaborations with Liquid Death and Crocs went live.
- A new CFO, Anya Hamill, replaces the interim CFO.
Third-quarter guidance of $88.0 million to $92.0 million extends the sequential climb. Management's tone also strengthened: it now describes the business as trending toward the high end of the $325.0 million to $340.0 million full-year range, even excluding Bark Air.
Bears still have legitimate ammunition. The Bark Air reversal is abrupt. One quarter ago management touted 37% growth for the business; now it has a preliminary deal to sell the assets and license the brand beginning January 1, 2027, citing insufficient returns and the macro environment. Bark Air contributed $3.5 million of revenue this quarter, and the arrangement is not yet definitive. Several other concerns remain:
- Full-year guidance has now been reaffirmed on three consecutive calls without a formal raise.
- Third-quarter adjusted EBITDA guidance of $1.0 million to $3.0 million is flat sequentially.
- A growing Commerce mix carries lower gross margins than DTC.
- Inventory sat unchanged at $72.4 million despite reduction plans, so the promised second-half destocking is a key test of cash generation.
On liquidity, cash rose $2.9 million to $19.0 million on $4.7 million of operating cash flow after $2.0 million of buybacks, and the company carries no debt.
The market had been treating BARK harshly heading into the print. Shares closed at $8.33 on November 4, down 15.5% from the $9.86 open after the prior report. The stock had spiked to $11.32 on that first post-report day and has since surrendered all of it. It hit a 52-week low of $7.40 on October 19 and has recovered only 12.6% from that level. It also remains 23.1% below its 200-day moving average of $10.83, and Earnings Whispers price, sequential-growth and AVWAP trend readings are negative.
Investor sentiment sends a conflicting signal. It swung sharply from -0.34 before the prior report to a reading of 1.87. That reading falls outside the stated -1 to +1 scale, so its magnitude should be treated cautiously, but the direction is clear: expectations turned decisively more optimistic even as the stock slid. That leaves less room for disappointment than the depressed share price alone implies.
The bottom line is that BARK produced a genuinely better quarter: a wider revenue beat, Commerce back to growth, cleaner gross margin expansion, rising cash and a credible product and partnership pipeline. Beneath that headline, consolidated revenue is still contracting, profitability remains thin, the Bark Air retreat raises questions about capital allocation, and management has steered toward the high end of guidance without formally raising it. The stock sits closer to its lows than its highs, so execution on the holiday-quarter retail orders and inventory reduction will matter more than the beat itself.
Read our earnings preview for BARK, Inc.: https://www.earningswhispers.com/article/BARK/22245
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-02 | |
| Oct-28 | |
| Oct-22 | |
| Oct-06 | |
| Sep-25 | |
| Sep-15 | |
| Sep-09 | |
| Sep-08 | |
| Sep-02 | |
| Aug-24 | |
| Aug-07 | |
| Aug-06 | |
| Jul-28 |
