ArcelorMittal Beats EPS Consensus Despite Flat EBITDA, Revenue Miss And Ukraine Write-Down, Putting Focus On Europe's 2027 Price Reset
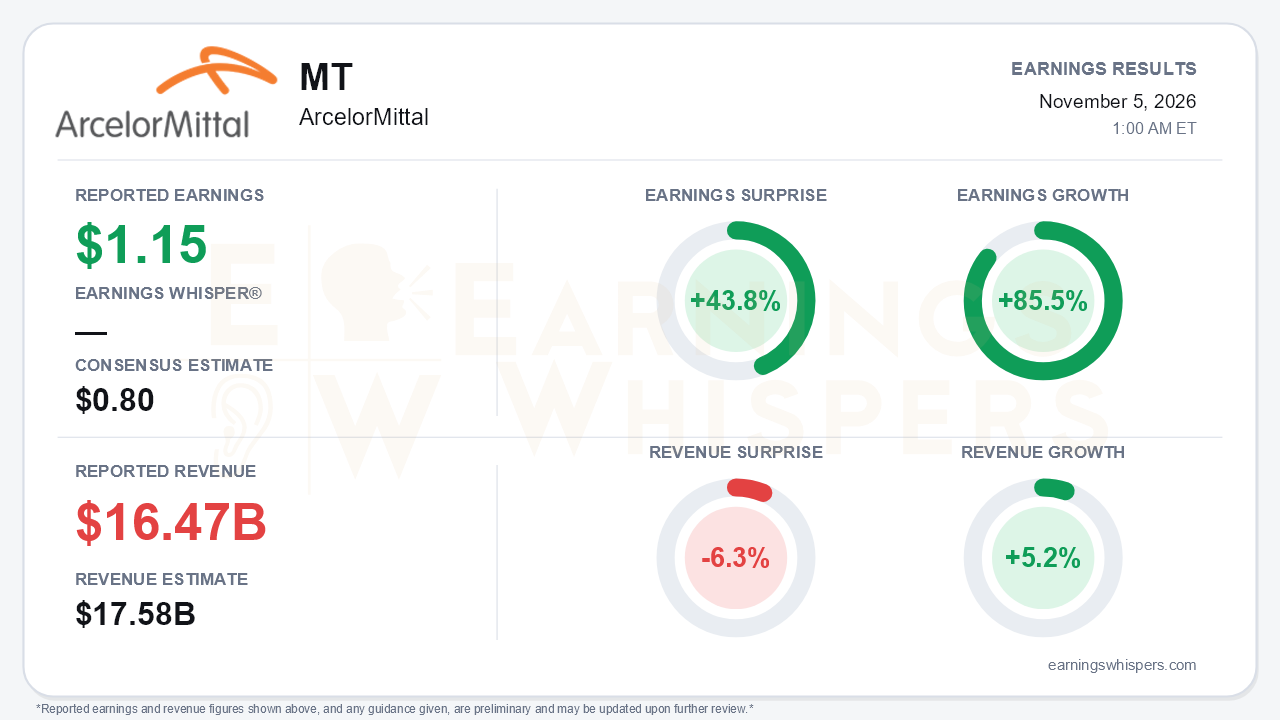
ArcelorMittal delivered a large headline beat for the third quarter, but the operating engine behind it barely moved. Adjusted EPS of $1.15 topped the $0.80 consensus by 43.8% and rose 85.5% from a year ago. Revenue of $16.466 billion grew 5.2% year over year yet missed the $17.58 billion consensus by 6.3%. On a reported IFRS basis, the company swung to a net loss of $391 million, or $0.52 per share, from a $0.90 profit in the second quarter. The loss reflects $852 million of impairments, $293 million of exceptional charges and a $170 million deferred-tax hit tied to idling the Kryvyi Rih operations in Ukraine after repeated missile strikes. That is the central tension: a quarter that looks strong on adjusted earnings, sits flat on operations, and comes with a policy-driven European earnings step-up that is still mostly ahead.
The quality of the beat deserves scrutiny. EBITDA was $2.02 billion, up 34% year over year but slightly below the second quarter's $2.06 billion. EBITDA per tonne held at $155, and steel shipments fell 2.1% sequentially to 13.0Mt. Even so, adjusted net income jumped to $868 million from $683 million. Most of that sequential gain came below the operating line. Foreign exchange and other financing items swung from a $286 million loss to a $10 million gain, helped by roughly $0.1 billion of non-cash mark-to-market gains on energy derivatives. A lower share count also helped. Year over year, the margin improvement is real and structural. Sequentially, the earnings acceleration owes more to financing noise than to steel spreads.
Beneath the consolidated figures, the segments diverged sharply.
- **Brazil:** EBITDA rose 26% to $506 million on a positive price-cost effect.
- **North America:** EBITDA held at $487 million despite a roughly $150 million hit from a Canadian long-products strike and Mexican DRI reliability problems.
- **Europe:** EBITDA fell to $548 million from $697 million. Energy and carbon costs rose faster than realized selling prices, and management also cited a raw-materials basket up about EUR40 per tonne since August.
- **Mining:** EBITDA slid to $128 million from $179 million on weaker iron ore prices and higher freight.
Europe nonetheless produced the most important operating signal. Flat shipments rose 1.1% sequentially, against normal seasonal patterns, in the first quarter under the new tariff rate quota. All European blast furnaces are back in operation.
The call kept the European story credible and gave it firmer milestones. Management guided fourth-quarter European flat shipments to double-digit year-over-year growth, up from the prior quarter's 'stable to higher' framing, and said the fourth-quarter order book is full. More than 25% of European flat volumes, mostly annual automotive contracts, reprice from January 2027, with January price guidelines described as well above the current index. Additional policy support could follow, including CBAM extension to downstream goods and possible inclusion of slabs in the TRQ. The CEO said he is 'even more optimistic than three months ago,' and management signaled that shareholder returns could exceed the policy minimum.
Bears still have legitimate ammunition:
- **Liberia:** 2026 shipment guidance was cut to roughly 16Mt from 18Mt, which trimmed the expected 2026 contribution from strategic projects to about $0.5 billion from $0.7 billion.
- **Delayed ramps:** The Calvert EAF is ramping more slowly than the second-quarter call implied, and Hazira volumes slipped largely into the second half of 2027.
- **Demand and costs:** North American fourth-quarter shipments are guided only flat. Real European demand is flat, with destocking persisting into the fourth quarter.
- **Balance sheet:** Free cash outflow was $442 million and net debt climbed to $10.3 billion from $9.5 billion. Management attributes this to a $2.5 billion year-to-date working-capital build it expects to largely unwind in the fourth quarter. That release now carries much of the cash and buyback narrative.
Investor sentiment improved modestly into the report, rising to 0.25 from 0.20, so expectations stayed positive but not euphoric. The stock has treated the European recovery story less kindly. Shares hit a 52-week high of $79.68 on September 8, then gave back much of that run to trade at $62.49 going into the release. That price is 7.8% below the open after the July report, 21.6% under the high and about 2% below the 200-day moving average of $63.82. The stock sits only 6.4% above its late-October low. AVWAP readings remain negative while the price trend is neutral, which fits a market that has de-rated the shares despite rising per-tonne margins.
The bottom line is that the EPS beat overstates the quarter's operating momentum. Flat EBITDA, a revenue miss, weaker mining results and a Ukraine write-down argue against reading this as an inflection already under way. The more consequential developments are forward-looking: double-digit European flat volume growth in the fourth quarter, January contract repricing, and an expected working-capital release that could fund above-policy returns. With the stock well off its September high and below its long-term average, the setup now depends on whether those 2027 European catalysts arrive before further execution slippage at Liberia, Calvert and Hazira.
Read our earnings preview for ArcelorMittal: https://www.earningswhispers.com/article/MT/22147
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Nov-02 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-21 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 |
