ICU Medical Beats On Record Infusion Systems Sales, But Pulled-Forward Volume And 2027 Cost Pressures Limit The Upside
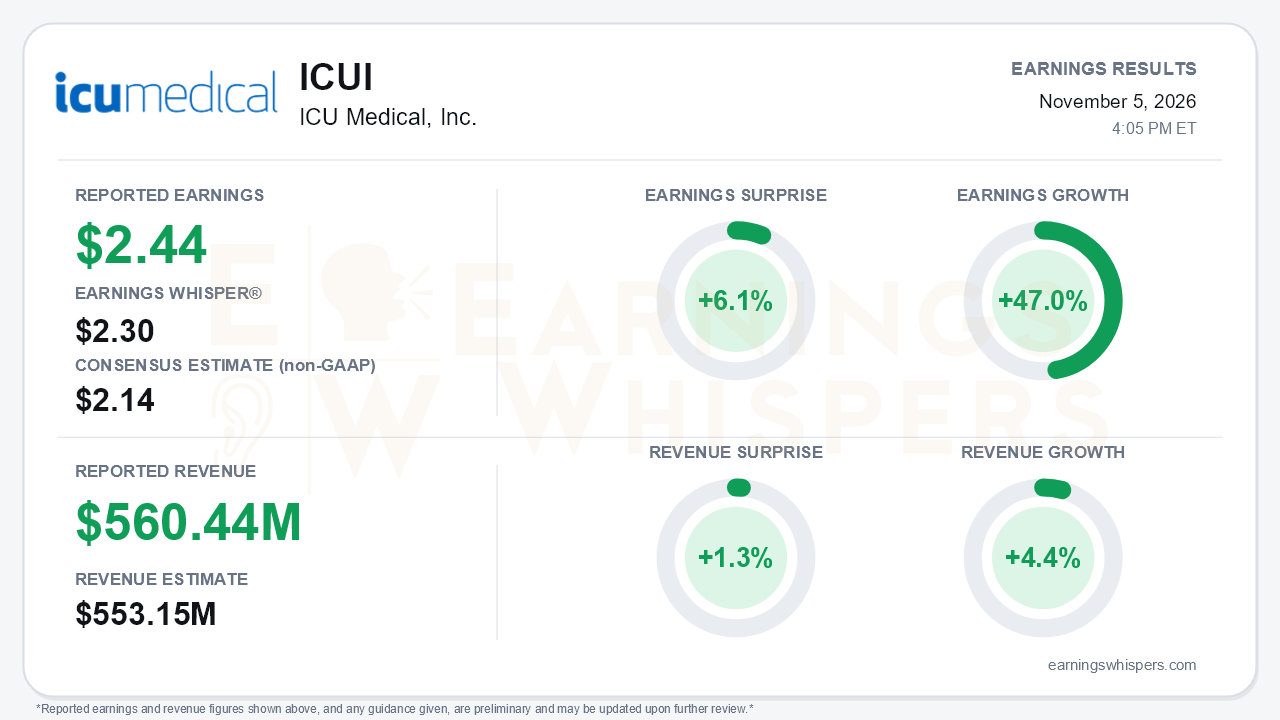
ICU Medical delivered a clean third-quarter beat. Adjusted earnings of $2.44 per share topped the $2.14 consensus by 6.1% and cleared the $2.30 Earnings Whisper number. Revenue of $560.44 million beat the $553.15 million consensus by 1.3% and grew 4.4% year over year. Earnings Whispers calculates earnings growth of 47.0%. On the company's own adjusted figures, EPS rose from $2.03 to $2.44, and the call analysis characterized that as roughly 20% growth. Investors should note that the two measures use different bases. On a GAAP basis, the company swung from a $(0.14) loss to a $1.07 profit. The central takeaway is that the core infusion franchise is executing well ahead of plan, while the guidance and call suggest much of the near-term upside is now visible and 2027 carries real cost headwinds.
The quality of the beat holds up better than a quick read of the reconciliation might suggest. The $10.4 million in IEEPA tariff refunds booked this quarter were stripped out of adjusted results, a $0.32 per-share reduction. A discrete tax benefit was excluded as well. The adjusted number therefore was not propped up by refunds. GAAP gross margin jumped to 42% from 37%, helped by lower charges for quality remediation ($6.6 million versus $13.8 million) and restructuring ($6.3 million versus $13.1 million). Adjusted gross margin improved more modestly, to about 42% from 41% in the first two quarters, which keeps the company on track for its 43% exit-2027 target. Cash generation was the standout. Free cash flow reached $83 million versus $28 million a year earlier, and year-to-date free cash flow of $173 million already exceeds the original $150 million full-year target. Debt paydown brought net leverage to 2.04x, reaching management's roughly 2x goal ahead of the original early-2027 timeline.
Beneath the headline, the business is diverging by segment. Infusion Systems grew 11% to a record $192.5 million, following 12% organic growth in the second quarter and just 1% in the fourth quarter of 2025. Management lifted full-year systems growth to at least high single digits. Consumables also set a record, rising 5%. Vital Care, however, fell 10% organically. Management attributed the decline to logistics consolidation of the legacy Smiths distribution network, which constrained shipments, particularly internationally, and the segment's full-year decline will now be larger than previously guided. Total organic growth eased to 5% from 6% in the second quarter. Management described demand and utilization as stable rather than accelerating.
The forward picture contains both genuine catalysts and legitimate ammunition for bears. On the product side:
- A revised MedFusion 5000 510(k) is expected to be filed within weeks.
- Plum Duo and Solo pumps received European authorization.
- The Otsuka joint venture broke ground on a PVC-free IV solutions plant.
- Capital return, including possible buybacks, is on the 2027 agenda now that the leverage target has been met.
The risks are equally concrete:
- Part of the systems strength reflects volume pulled forward from early 2027 into the fourth quarter, which flatters 2026 at the expense of next year's comparison.
- CADD ambulatory pump clearance trails MedFusion by a couple of months after the FDA requested more testing.
- Tariff refunds, $31 million to date, are largely exhausted, so the free cash flow tailwind fades.
- Management flagged Section 232 tariffs, a stronger euro, inflation, and diesel costs as threats to 2027 margin expansion, and it offered no 2027 outlook.
Guidance itself was reaffirmed rather than raised outright. Management now expects to land toward the high end of the adjusted EBITDA range of $415 million to $435 million and the adjusted EPS range of $8.60 to $9.00. Both ranges had already been lifted in the second quarter. That is incremental confidence, not a new leg higher.
The market setup is more complicated than the surprise implies. Shares spiked to a 52-week high of $192.85 the day after the August report, then slid to $151.33 by mid-September. At $172.62, the stock entered this report 5.3% below its post-August opening price but 16% above its 200-day moving average, sitting near the middle of its inter-earnings range. Investor sentiment improved modestly, from slightly negative (-0.073) to slightly positive (0.038), a shift toward cautious optimism rather than enthusiasm. The Earnings Whispers trend readings are mixed, with momentum positive while AVWAP remains negative, consistent with a stock that has not regained its post-August highs.
The bottom line is that ICU Medical's third quarter validated the turnaround's core pillars: rebounding infusion systems growth, steadily improving margins, strong free cash flow, and leverage reduced ahead of schedule. Vital Care's logistics problems are self-inflicted and likely fixable. The harder questions concern 2027. Pulled-forward pump volume, fading tariff refunds, and new tariff and currency pressures mean the next leg of the story depends on product approvals and margin execution, not on another quarter of upside surprises.
Read our earnings preview for ICU Medical, Inc.: https://www.earningswhispers.com/article/ICUI/22309
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Aug-27 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-23 | |
| Jul-10 | |
| Jul-09 | |
| May-07 | |
| May-07 |
