ICF Beats On Earnings But Cuts Revenue Outlook As Utility Affordability Politics Stalls Its Commercial Energy Engine
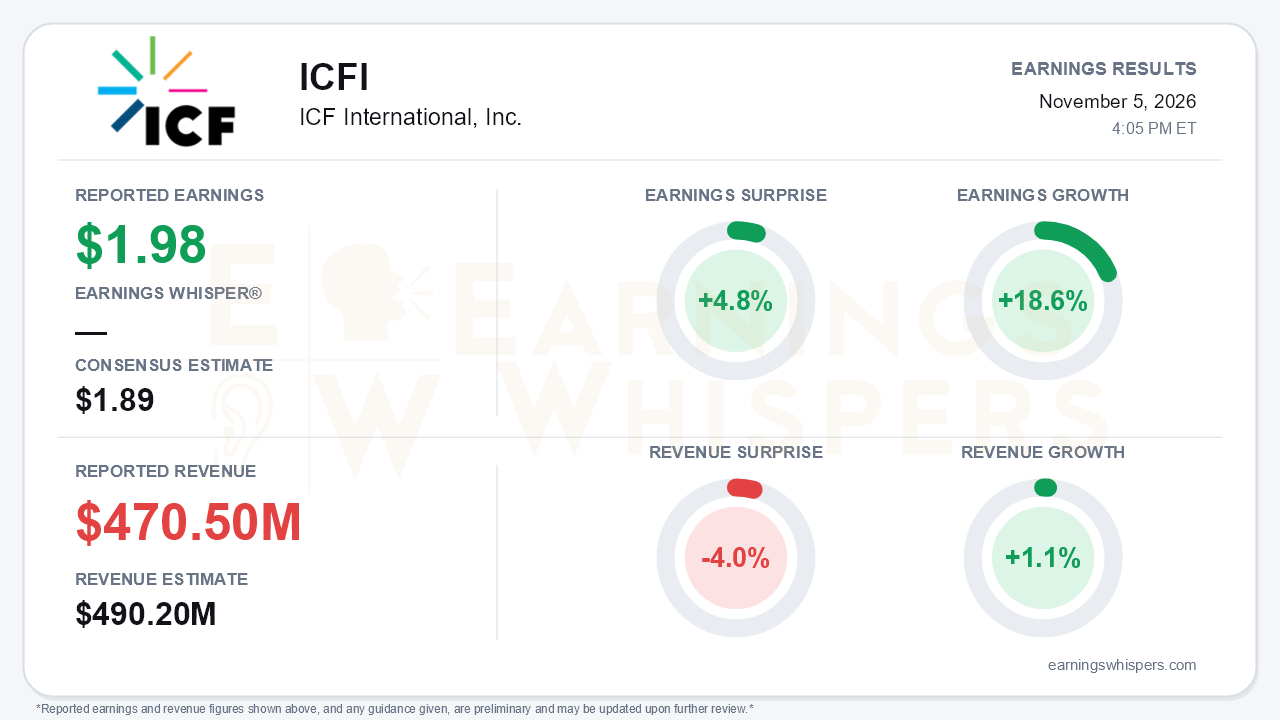
ICF International delivered a third-quarter earnings beat, but the revenue line carries the more consequential message. Non-GAAP EPS of $1.98 topped the $1.89 consensus by 4.8% and grew 18.6% year over year, faster than the roughly 12% pace in the second quarter. Revenue of $470.5 million rose 1.1% but missed the $490.2 million consensus by 4.0%. Management also lowered full-year revenue guidance to about $1.87 billion, roughly flat with 2025, from a prior $1.89 billion to $1.96 billion range. The "reaffirmed" label applies only to the $7.10 non-GAAP EPS midpoint. That is the central tension: the earnings target held while the growth story underneath it lost ground.
The quality of the beat deserves scrutiny. The operating margin did improve:
- Gross margin rose 50 basis points to 38.1%, helped by a mix shift toward fixed-price work (50.2% of revenue) and lower subcontractor costs.
- Operating income climbed 13.6% to $43.6 million.
The pre-amortization gains were smaller, though. Adjusted EBITDA rose only about $1 million to $54.2 million, a 10-basis-point margin improvement to 11.5%. Much of the bottom-line acceleration came from below the operating line:
- The tax rate fell to 15.0% from 22.7%.
- The diluted share count dropped to 18.1 million from 18.5 million.
- Interest expense declined.
The same levers support the full-year EPS outlook. Management cut its tax-rate assumption to about 19% from 20.5% and interest guidance to $25 million to $26 million. Those changes allowed it to hold the $7.10 midpoint despite lower revenue.
The quarter did mark a real inflection in the top-line trajectory. Revenue fell 10.3% in the first quarter, was flat in the second and returned to growth in the third, as management had promised. Results by client group were mixed:
- Federal revenue rose 3.4% sequentially, the third straight sequential gain, but remained 3.5% below last year.
- State and local revenue grew 7.6%, reversing a decline in the second quarter.
- International government revenue rose 12%.
The problem is commercial energy, which had been the company's growth engine. That business grew 24% in 2025 and was guided to at least 10% growth on each of the prior three calls. It is now expected to grow only at a low- to mid-single-digit rate in 2026. Management attributed the shortfall to several factors:
- Utility bill affordability became a sharp political issue in the third quarter.
- Utilities abruptly paused the incremental energy-efficiency add-ons that typically lift second-half revenue, costing roughly $15 million in the quarter, with a similar hit expected in the fourth.
- New contracts ramped more slowly than expected.
The forward indicators are mixed. On the positive side:
- Awards reached $746 million, up 4.5%, with more than 60% representing new business.
- Quarterly book-to-bill jumped to 1.59 from 0.85 in the second quarter.
- Backlog rose to $3.5 billion from $3.3 billion.
- Energy advisory revenue grew 14.1%, with expanding work for hyperscalers on data-center power and reliability issues.
- Commercial energy wins are tracking above plan, with six new utility portfolios and ten new logos.
- Management highlighted an OpenAI partnership, defense and national security task orders, and $70.9 million in Los Angeles County energy work orders as new avenues for growth.
- Management called the midterm election results a tailwind for its business.
Bears have legitimate ammunition on the other side:
- The pipeline shrank to $8.2 billion from $9.3 billion last quarter.
- Disaster recovery work remains constrained by funding delays.
- Federal procurement bottlenecks persist.
- The mid-to-high single-digit growth framework for 2027, voiced on the prior two calls, was not repeated. Management pointed instead to a roughly 4% second-half exit rate and deferred formal guidance.
Cash generation was a clear bright spot. Year-to-date operating cash flow excluding restricted cash was $88.7 million versus $30.2 million a year earlier, and leverage eased to 1.87x.
The market setup is more complicated than the EPS surprise implies. Investor sentiment improved sharply, moving from clearly negative (-0.37) after the prior report to modestly positive (+0.08). The stock rose 11.9% from its post-August opening to $96.91 and sat about 23% above its 200-day moving average. It entered the report just 2.6% below a 52-week high of $99.49 set the day before earnings. Price and AVWAP trend readings are positive, while sequential growth and momentum are only neutral. In other words, shares ran up on expectations of a second-half recovery, and the report confirmed only part of that recovery: the return to growth. The acceleration it delivered is smaller than the one investors were positioned for.
The bottom line is that ICF's beat was real but engineered more by margin discipline, a lower tax rate and fewer shares than by demand. The guidance cut and the reset in commercial energy undercut the narrative that had driven the stock to its highs. Strong bookings and backlog keep a credible 2027 growth story alive, but the burden now shifts to evidence that utility spending resumes and that the shrinking pipeline stabilizes.
Read our earnings preview for ICF International, Inc.: https://www.earningswhispers.com/article/ICFI/22308
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Sep-28 | |
| Sep-24 | |
| Sep-09 | |
| Sep-02 | |
| Aug-27 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-28 |
