IBEX Reaccelerates To 16% Growth And Raises Guidance After One Quarter, But Taxes And Customer Concentration Limit The Upside
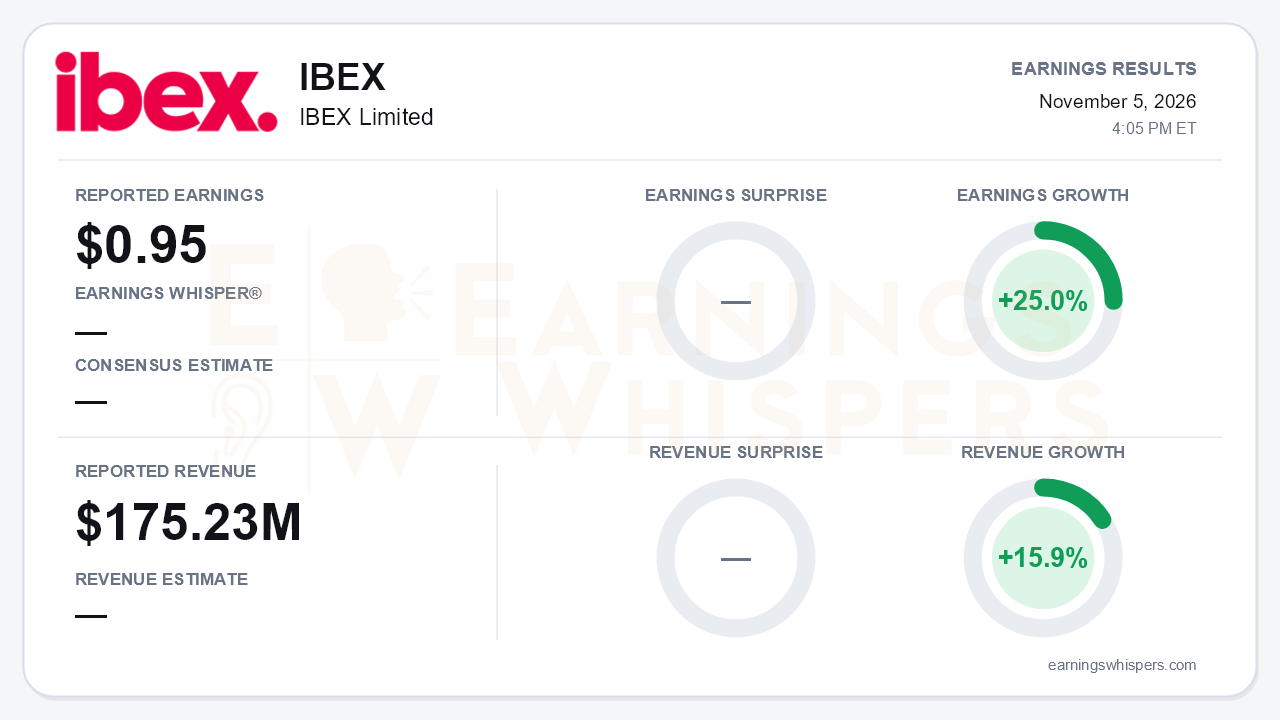
IBEX Limited opened fiscal 2027 with a quarter that reversed the wobble in its fourth quarter. Earnings Whispers' normalized EPS was $0.95, up 25.0% year over year, on revenue of $175.23 million, up 15.9%. The company reported GAAP diluted EPS of $0.99 (+20%) and adjusted EPS of $1.10 (+21%). Investors should know that these three figures are calculated on different bases. No consensus or whisper figure was available, so management's own targets are the most useful yardstick. IBEX cleared them easily. Revenue topped the $168-170 million first-quarter guide, and adjusted EBITDA of $25.2 million beat the $22-23 million target. Management then raised full-year guidance only one quarter after setting it. Revenue growth reaccelerated from 12% in the fourth quarter to 16%, its seventh straight double-digit quarter. That makes it hard to read the fourth-quarter softness as anything more than a temporary disruption.
The margin recovery holds up to scrutiny. Adjusted EBITDA margin reached 14.4%, up 150 basis points from a year ago and well above 12.3% in the fourth quarter and 13.4% in the third. Gross margin improved to 30.4% from 28.6% last quarter, and SG&A fell to 17.2% of revenue. Management credited higher-margin offshore delivery and growth in the AI agent and digital acquisition businesses. Operating income rose about a third, to $18.3 million. The headline masks one meaningful leak: the effective tax rate jumped to 19% from 11%. That lifted the tax provision to $3.5 million from $1.5 million and held GAAP net income growth to 22.7%. A rising diluted share count, about 15.0 million versus 14.6 million, also diluted per-share gains despite $4.4 million of buybacks. Cash generation was solid but less spectacular than earnings. Free cash flow was a record $9.2 million and net cash rose to $35.0 million, but receivables climbed nearly $11 million and days sales outstanding (DSO) ticked up to 72 from 69.
The demand picture is the strongest part of the story. IBEX added four new logos in the quarter, two of them in FinTech. After quarter end it announced four Sierra-powered AI agent wins and three verbal traditional outsourcing wins, all expected to launch in the second quarter. New-logo cohorts drove about half of first-quarter growth, which management called a significant increase versus the prior three years. Three recent logos are on pace to become top-25 clients. Client retention stayed above 99%, and client net promoter score (NPS) rose from 71 to 83. The most strategically telling development is a fiber provider that first replaced its automated phone menu with an IBEX AI agent in six weeks. IBEX is now taking over all of that client's human-agent work from a multi-billion-dollar competitor. That land-and-expand example directly addresses the market's biggest worry for outsourcers, that AI will cannibalize human customer-experience work. Here, AI opened the door to more of it.
The weaker threads are real, even if secondary. HealthTech still grew 40%, but that was down from 54% in the third quarter. Top-10 client growth slowed to 13% from 19% in the third quarter and 22% for fiscal 2026. Telecom was flat. FinTech was roughly flat, with its share of revenue slipping to 9.3% from 11%. Nearshore revenue was also flat. Management guided the tax rate to 21-22% for the year. The CFO also signaled that year-over-year margin gains in later quarters will be smaller than the first quarter's 150 basis points. The raised EBITDA outlook implies roughly 50-70 basis points of full-year expansion. Capital spending is moving to the high end of its range, about $30 million, to fund capacity in offshore regions and the newly announced Egypt site.
The guidance itself extends a credible pattern. Revenue is now expected at $720-735 million (12-14% growth), up from $700-715 million. Adjusted EBITDA is now seen at $96-99 million (17-20% growth), up from $90-94 million. IBEX raised repeatedly through fiscal 2026 and finished that year at $644.1 million, above each interim range. With a second-quarter launch slate already secured, the new guide does not look like a stretch.
Current price and sentiment data were not available, which limits what can be said about positioning. Shares opened at $32.26 after the September report, below the 200-day moving average now at $34.34. The company repurchased stock during the quarter at an average of $35.92, which shows management was willing to buy above those levels.
The bottom line is that IBEX delivered a clean beat-and-raise that restored both growth and margin momentum, and the AI partnership appears to be generating incremental human-agent work rather than eroding it. The quality caveats are a higher tax rate, decelerating growth among top clients and HealthTech, flat telecom, FinTech and nearshore revenue, and margin gains that will narrow from here. None of them undermines the quarter, but they argue for expecting steady compounding rather than a repeat of the first quarter's margin step-up.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Sep-11 | |
| Feb-06 | |
| Feb-05 | |
| Oct-16 | |
| Sep-12 | |
| Sep-10 | |
| Jul-30 | |
| Jun-26 | |
| Jun-18 | |
| Jun-17 | |
| Jun-10 | |
| Jun-05 | |
| Jun-02 | |
| May-28 |
