Halozyme Posts Record Royalties, A Third Guidance Raise And A European Win Against Merck, But The Raise Is Smaller And Growth Is Cooling
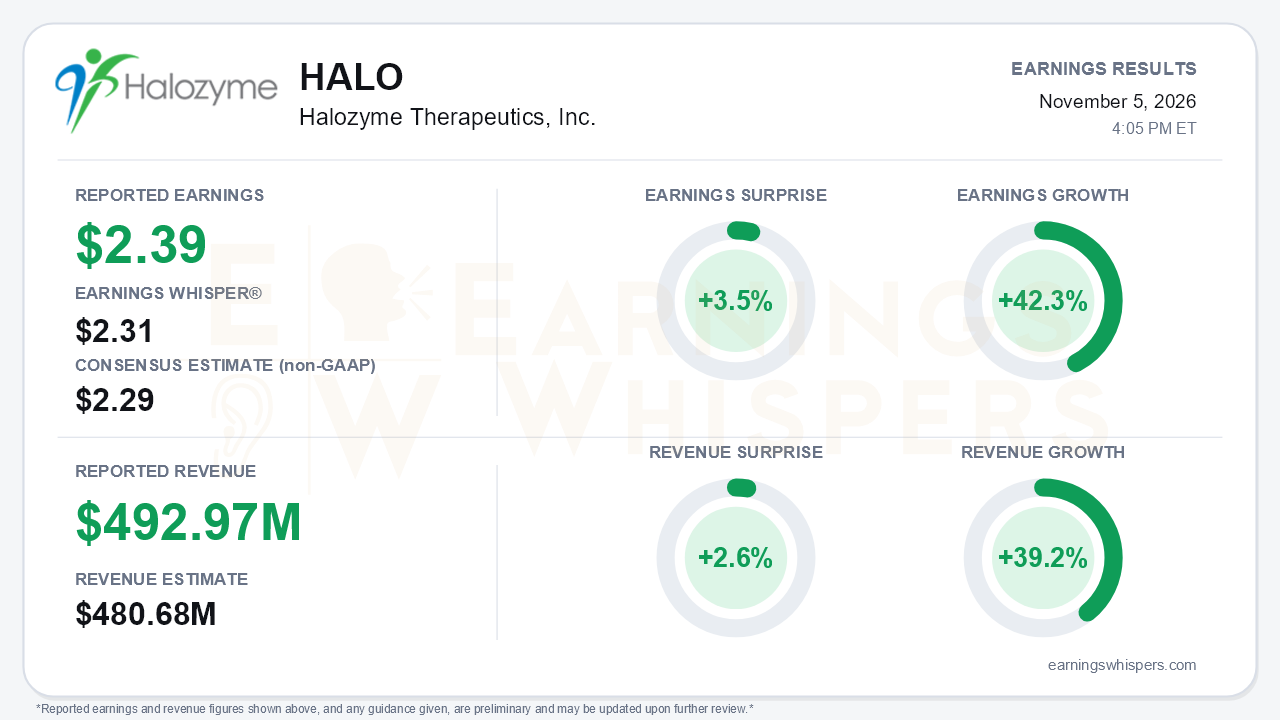
Halozyme Therapeutics delivered a clean beat for the third quarter. Non-GAAP earnings were $2.39 per share, ahead of the $2.29 consensus and the $2.31 Earnings Whisper number, a 3.5% surprise. Earnings grew 42.3% year over year. Revenue of $492.97 million beat consensus by 2.6% and grew 39.2%. Management raised full-year guidance for the third straight time and won a major patent ruling against Merck in Europe. The central tension is that the quarter's momentum is real but moderating. Revenue growth slowed from 48% in the second quarter to 39%, royalty growth eased from 50% to 44%, and the latest guidance raise was a fraction of the prior one. That arrives just as the stock trades near its highs.
The quality of the quarter is strong where it matters most. Royalties hit a record $341 million, up 44%, compared with $308 million in Q2 and $241 million in Q1. Growth also broadened beyond the core franchise:
- Darzalex SC royalties rose a steadier 20% to $153.5 million.
- VYVGART Hytrulo royalties jumped 89% to $88.1 million.
- "Other" royalties climbed 92% to $65.1 million as Ocrevus Zunovo, Opdivo Qvantage and Rybrevant Faspro scaled.
Product sales rose to $137.3 million from $94.2 million. Collaboration revenue was weaker, falling to $14.6 million from $24.0 million, and the year-to-date total of roughly $65 million leaves a heavy fourth-quarter lift to reach the $110 to $130 million full-year target. GAAP diluted EPS was $2.01, below the non-GAAP figure. The gap reflects higher amortization from the Elektrofi acquisition, share-based compensation and $7.5 million of Merck litigation costs excluded from adjusted results. GAAP net income also benefited from flat income-tax expense despite much higher pretax income.
The call reinforced that adoption is deepening. Ocrevus Zunovo reached about 56,000 patients, up from 44,000 in Q2 and 24,000 in Q1. Phesgo conversion rose to 59% from 54%, and Opdivo Qvantage conversion reached 17% from 15%. Adjusted EBITDA of $336 million represented a 68% margin. Management left its full-year margin outlook near 67%, however, so profitability is holding steady rather than expanding further. Current partners nominated four new ENHANZE targets: two from argenx, one from Incyte and one from J&J. Three programs entered Phase 1, bringing the clinical count to 12, with 13 expected by year-end. The pipeline story is credible, though Q3 produced no new collaboration agreements after five in Q2.
The most consequential development was legal. The Dutch court ruled that Keytruda Qlex infringes Halozyme's MDASE patent, rejected Merck's invalidity arguments and imposed an injunction across eight European markets. Combined with the existing German injunction, management said these markets represent roughly 20% of global subcutaneous royalties. A separate suit targets Merck's Italian fill-finish manufacturer. Bears have legitimate ammunition on the other side of the ledger. U.S. post-grant review decisions on multiple MDASE patents went against Halozyme, with an appeal likely running to 2028. Leverage has also moved the wrong way. After the $1.5 billion convertible offering, long-term debt is roughly $3.3 billion and net leverage is 2.4x, versus an earlier target of about 1.2x by year-end. Buybacks of $400 million this year have pushed stockholders' equity into a deficit. Royalty step-downs on legacy products in 2029-30 remain an overhang.
The guidance raise deserves scrutiny. Total revenue guidance is now $1.86 to $1.925 billion, and non-GAAP EPS guidance is $8.75 to $9.05. The revenue midpoint moved up only about $20 million, compared with roughly $110 million last quarter. That raise came in line with estimates rather than ahead of them. Halozyme is still raising, but the upside surprises are shrinking.
That matters because the market setup is more complicated than the surprise implies. Shares opened at $90 after the August report and stood at $130.34 on the eve of this release, a 44.8% gain. That left the stock 54.8% above its 200-day moving average and just 2.7% below the $134 52-week high set on October 30. Investor sentiment swung sharply over the period, moving from slightly negative (-0.11) to solidly positive (+0.50). The Earnings Whispers trend signals are mostly positive, although sequential growth reads only neutral, consistent with the deceleration in quarterly growth rates. Expectations entering the print were far more demanding than they were three months earlier.
The bottom line is that Halozyme's royalty engine is performing, broadening and being defended successfully in Europe, and nothing in the quarter undermines the long-term platform thesis. But the business is moving from upside surprises to steady execution. Growth is decelerating, guidance increments are shrinking, margins are flat, leverage is rising and the U.S. patent fight remains unfavorable. With the stock sitting near its highs after a 45% run and sentiment sharply more optimistic, the report justifies the strength without clearly extending it.
Read our earnings preview for Halozyme Therapeutics, Inc.: https://www.earningswhispers.com/article/HALO/22300
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-23 |
How Halozyme, Up 80% This Year, Is Rivaling Merck And Hitting New Highs
HALO
Investor's Business Daily
|
| Oct-22 | |
| Oct-14 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Sep-30 | |
| Sep-28 | |
| Sep-17 | |
| Sep-16 |
