Green Plains Beats On Tax-Credit-Fueled Record EBITDA, But A Stock Near Its Lows Shows The Market Still Wants Cash, Not Accruals
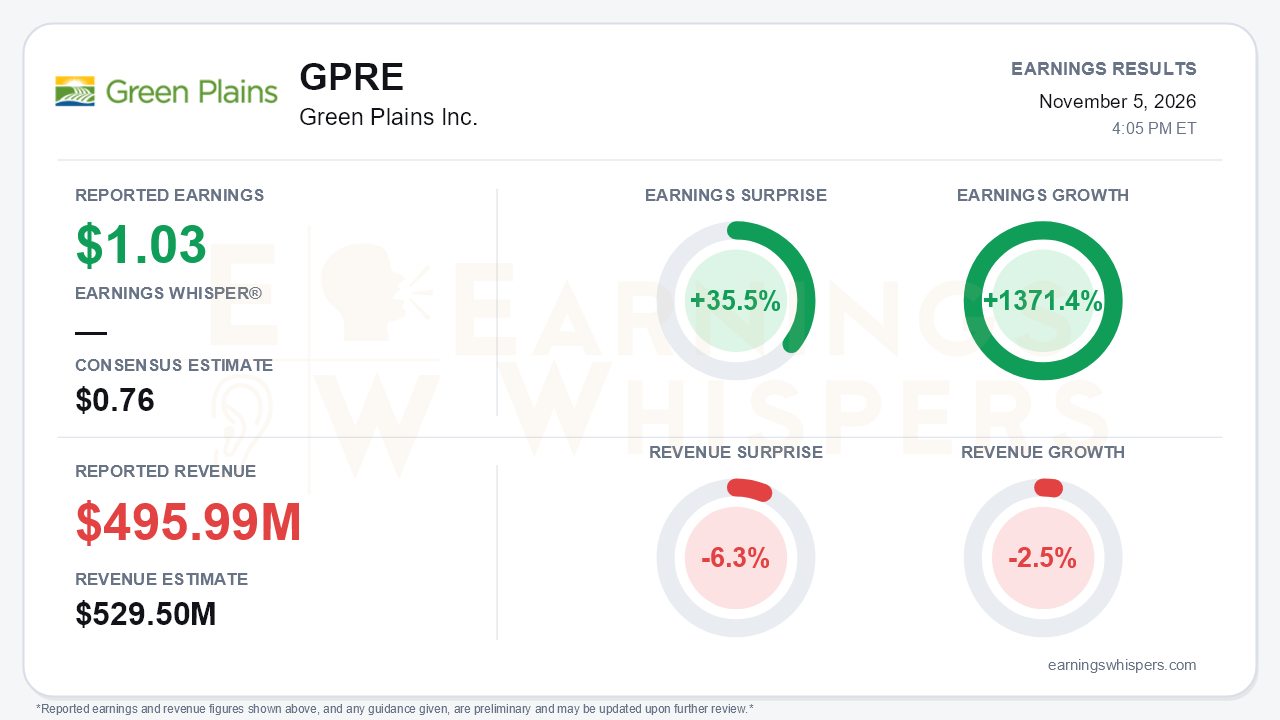
Green Plains delivered the kind of quarter its turnaround case needed, though the composition of the beat deserves scrutiny. The company earned $1.03 per diluted share in the third quarter, topping the $0.76 consensus by 35.5% and rising 1371.4% from $0.17 a year earlier. Revenue moved the other way. At $495.99 million, sales missed the $529.5 million consensus by 6.3% and fell 2.5% year over year, mostly because the Obion, Tennessee plant was sold. Record adjusted EBITDA of $118.0 million, more than double the $52.6 million of a year ago, is the headline. The central tension is that $65.4 million of it came from Section 45Z production tax credits. Those credits are now recorded as a reduction to cost of goods sold, and they had largely not been converted to cash by quarter-end.
The base business still improved meaningfully. Green Plains attributes $52.6 million of adjusted EBITDA to operations outside 45Z. That compares with a prior-year total of $52.6 million that, after the retrospective accounting restatement, itself included $25.0 million of 45Z credits. The consolidated ethanol crush margin rose to $122.8 million from $59.6 million, roughly 70 cents per gallon versus 30 cents, even though ethanol volumes fell 11.3% to 174.9 million gallons. The year-over-year earnings comparison is noisy in both directions:
- The prior-year quarter included a $36.0 million gain on asset sales.
- It also carried $47.8 million of interest expense, inflated by refinancing fees.
- Interest expense fell to $8.1 million this quarter.
One more detail matters. Diluted EPS of $1.03 sits well below basic EPS of $1.23. The diluted share count jumped to 85.5 million from 77.9 million, reflecting convertible debt that management says will be retired in early 2027.
The call marked a clear operational step-up. Adjusted EBITDA has climbed from $49.1 million in the fourth quarter of 2025 to $93 million in the second quarter and $118 million now. Utilization recovered to about 95% after second-quarter downtime at Madison. Production rose 14 million gallons sequentially, and the company posted record ethanol and corn oil yields. Madison had its best quarter ever and qualified for a more favorable 45Z tier, worth roughly $6 million in the quarter. Management credited most of the crush improvement to execution rather than the commodity backdrop. That claim matters because it implies some durability if industry margins soften.
Guidance moved higher again. Expected 2026 carbon EBITDA rose to $230 million to $250 million, from roughly $188 million framed at the start of the year. Management also offered a first 2027 floor of at least $250 million. The bigger development came after quarter-end, when the company signed its long-awaited 45Z monetization agreement. The deal covers $250 million to $325 million of gross face value plus a $30 million buyer option, with about $140 million expected to convert to cash in the fourth quarter.
That cash conversion addresses the bears' sharpest point. Nine-month operating cash flow was just $47.4 million, held back by a $215 million working-capital drag as the production tax credit asset swelled to $209.9 million. Unrestricted cash slipped to $160.0 million from $182.3 million at year-end, while total cash including restricted balances was $225.1 million. Current debt maturities also rose to $69.7 million ahead of the convertible retirement.
Forward risks are real:
- **Seasonality:** Management expects fourth-quarter industry margins below third-quarter peaks, though it still guides gross margins above historical averages.
- **Corn basis:** A delayed harvest and reluctant farmer selling create basis risk.
- **Policy window:** Management does not expect 45Z to be extended in its current form, which limits the window for projects such as Farm Forward and the Central City net-negative carbon-intensity effort.
- **Capital competition:** Growth capex is set to rise in 2027 from about $20 million to $25 million this year, and management explicitly framed buybacks as competing for that capital.
The market has not been rewarding the story. Shares closed at $13.66 ahead of the report, down 14.7% from the $16.01 open after the August release. That leaves the stock 10.5% below its 200-day moving average and just 2.2% above its inter-earnings low of $13.36, set on October 27. It is 17.6% below the August 21 high of $16.58. Price and AVWAP trend readings remain negative. Investor sentiment stayed negative and was essentially unchanged, edging from -0.374 to -0.360. Skeptics were evidently positioned for disappointment, not a record quarter paired with a signed monetization deal.
The bottom line is that Green Plains beat on earnings, raised its carbon outlook and set a 2027 floor, and showed genuine operational progress in the base business. Still, roughly 55% of adjusted EBITDA came from a policy-dependent credit stream that management itself does not expect to survive in its current form. The fourth-quarter conversion of about $140 million into cash is the next proof point. Until those accruals become cash, a stock trading near its lows suggests investors are discounting the durability rather than the size of these earnings.
Read our earnings preview for Green Plains Inc.: https://www.earningswhispers.com/article/GPRE/22295
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-02 | |
| Oct-30 | |
| Oct-28 | |
| Oct-23 | |
| Oct-19 | |
| Oct-01 | |
| Sep-04 | |
| Aug-20 | |
| Aug-06 | |
| Jul-24 | |
| Jun-01 | |
| May-07 | |
| May-04 |
