Fulgent Genetics Beats Sharply As Billing Fix Restores Margins, But Flat Q4 Revenue Implied By Guidance Caps The Recovery
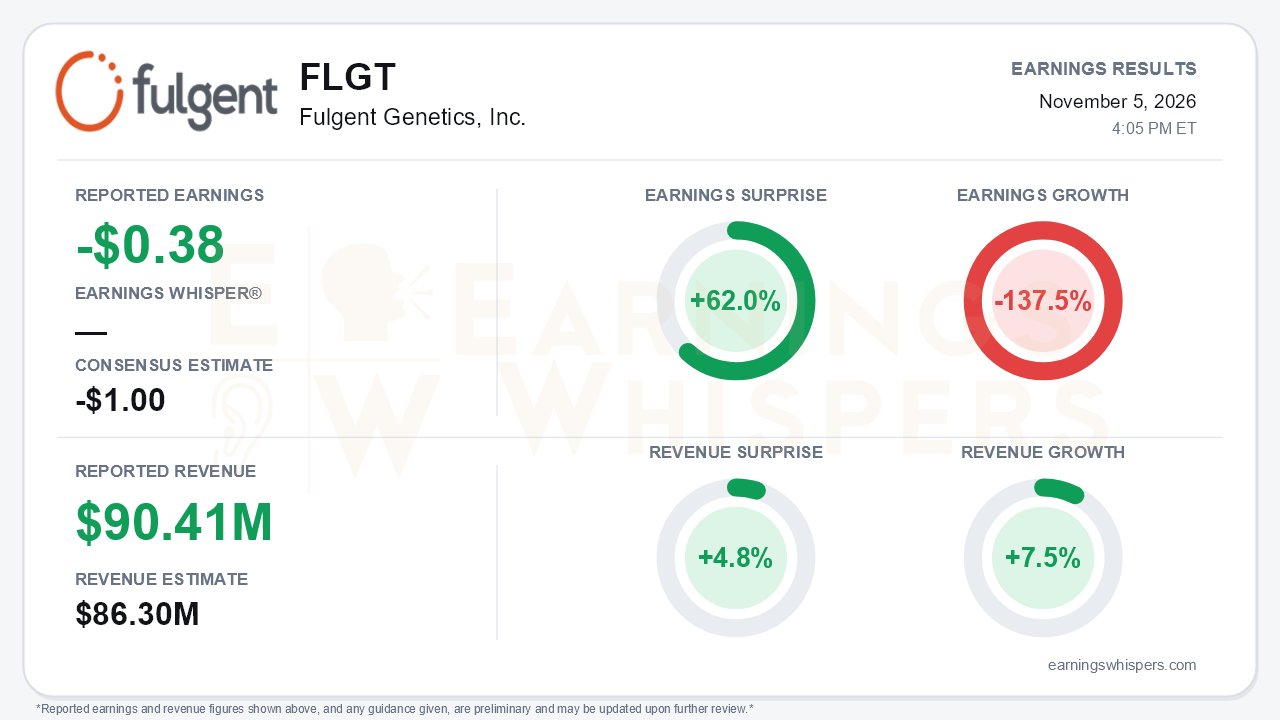
Fulgent Genetics delivered the kind of quarter that changes the near-term narrative without fully resolving the long-term one. The company reported a loss of $0.38 per share on revenue of $90.41 million, against a consensus loss of $1.00 and revenue expectations of $86.3 million. That was a 62.0% earnings surprise and a 4.8% revenue beat. Earnings fell 137.5% from a year ago, while revenue grew 7.5%. The figures depend on the basis used. The company reported a GAAP loss of $0.48 and a non-GAAP loss of $0.09, compared with non-GAAP earnings of $0.14 a year earlier. On any measure, Fulgent remains loss-making where it was profitable on an adjusted basis last year. The central takeaway is that Q3 marked a clear sequential turn after the Q2 guide-down, driven primarily by fixing a self-inflicted billing problem rather than by a demand inflection.
The quality of the beat deserves scrutiny. Non-GAAP gross margin recovered to 36.3% from 31.3% in Q2 and 32.3% in Q1. CFO Paul Kim credited improved collection rates as the company worked through its billing system issue. Non-GAAP operating margin improved to -13.2% from -26.2% the prior quarter. Adjusted EBITDA loss narrowed to $7.5 million from $17.1 million. Measured year over year, however, the picture is far less flattering. Gross margin is still roughly eight points below the 44.3% posted a year ago, and the non-GAAP operating margin compares with -4.2% in the prior-year quarter. Q3 operating expenses also benefited from a $3.2 million bad-debt recovery, which inflates the sequential margin improvement. The headline beat is real, but part of it reflects reversal of earlier damage.
The revenue mix reveals a more uncomfortable trend. Sequential growth was solid: revenue rose 6% from $85.4 million in Q2 and from $71.1 million in Q1. Anatomic pathology jumped 57% year over year to $40.9 million, but the Bako and StrataDx acquisitions contributed $21.8 million of that. Acquired revenue therefore exceeded the entire year-over-year top-line gain, which implies the legacy base contracted. Precision diagnostics fell 18% as the largest customer continued in-sourcing, and management trimmed the top end of that segment's full-year guide to $161-165 million. Biopharma services was a bright spot at $7.7 million, up 19% sequentially, with its full-year range nudged up to $23-25 million. Demand, in aggregate, looks flat.
Guidance captures the same split. Management reaffirmed 2026 revenue of $330-340 million, still well below the original $350 million target, and the midpoint implies Q4 roughly flat with Q3. Everything below the revenue line moved up:
- The non-GAAP loss outlook improved to $1.65-$1.75 per share from $2.22-$2.35 on the Q2 call.
- The operating margin outlook moved to the low negative-20s.
- Year-end cash guidance rose to $630 million from $610 million, aided by a $112.3 million federal tax refund.
- Therapeutic development spend was cut to roughly $21 million from $26 million.
The per-share improvement also benefits from 4.1 million fewer shares following $64.1 million of year-to-date buybacks, although the cash guide assumes no further near-term repurchases.
The forward catalysts are real but carry asterisks. FID-007 completed its end-of-Phase II FDA meeting in August and Phase III preparation is underway. The prior first-half 2027 start was not explicitly reiterated, however, and partnering remains unresolved. The AI pathology platform is scaling, with about 255,000 slides analyzed, up 23% sequentially, four modules in production and five more planned for Q4. Management said the billing fine-tuning is incomplete and gave no timeline for a return to historical collection rates. FY2027 guidance on the next call will be the true test.
The market setup is more complicated than the surprise implies. Shares had climbed 13.6% since the open following the July report to $19.68 heading into this release. That leaves them just 2.1% above the 200-day moving average and 13.6% below the October 6 inter-earnings high of $22.78, after a rally from the $16.05 low set the day after the last report. Investor sentiment remained negative and weakened modestly, slipping from -0.34 to -0.39, so expectations were not elevated going in. Price, sequential-growth and AVWAP trend readings are positive, while momentum remains negative.
The bottom line is that Fulgent proved the billing-driven margin collapse is reversing faster than management expected, and the improved loss and cash outlook is backed by a $652.4 million balance sheet. Bears still have legitimate ammunition: organic revenue is shrinking beneath acquired growth, the largest customer keeps pulling volume, and guidance embeds no Q4 acceleration. Q3 repaired the damage; it did not yet demonstrate durable growth.
Read our earnings preview for Fulgent Genetics, Inc.: https://www.earningswhispers.com/article/FLGT/22285
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-15 | |
| Jul-31 | |
| Jul-30 | |
| Jul-09 | |
| Jun-01 | |
| May-21 | |
| May-02 | |
| May-01 | |
| Apr-22 | |
| Apr-16 | |
| Mar-17 | |
| Feb-27 |
